

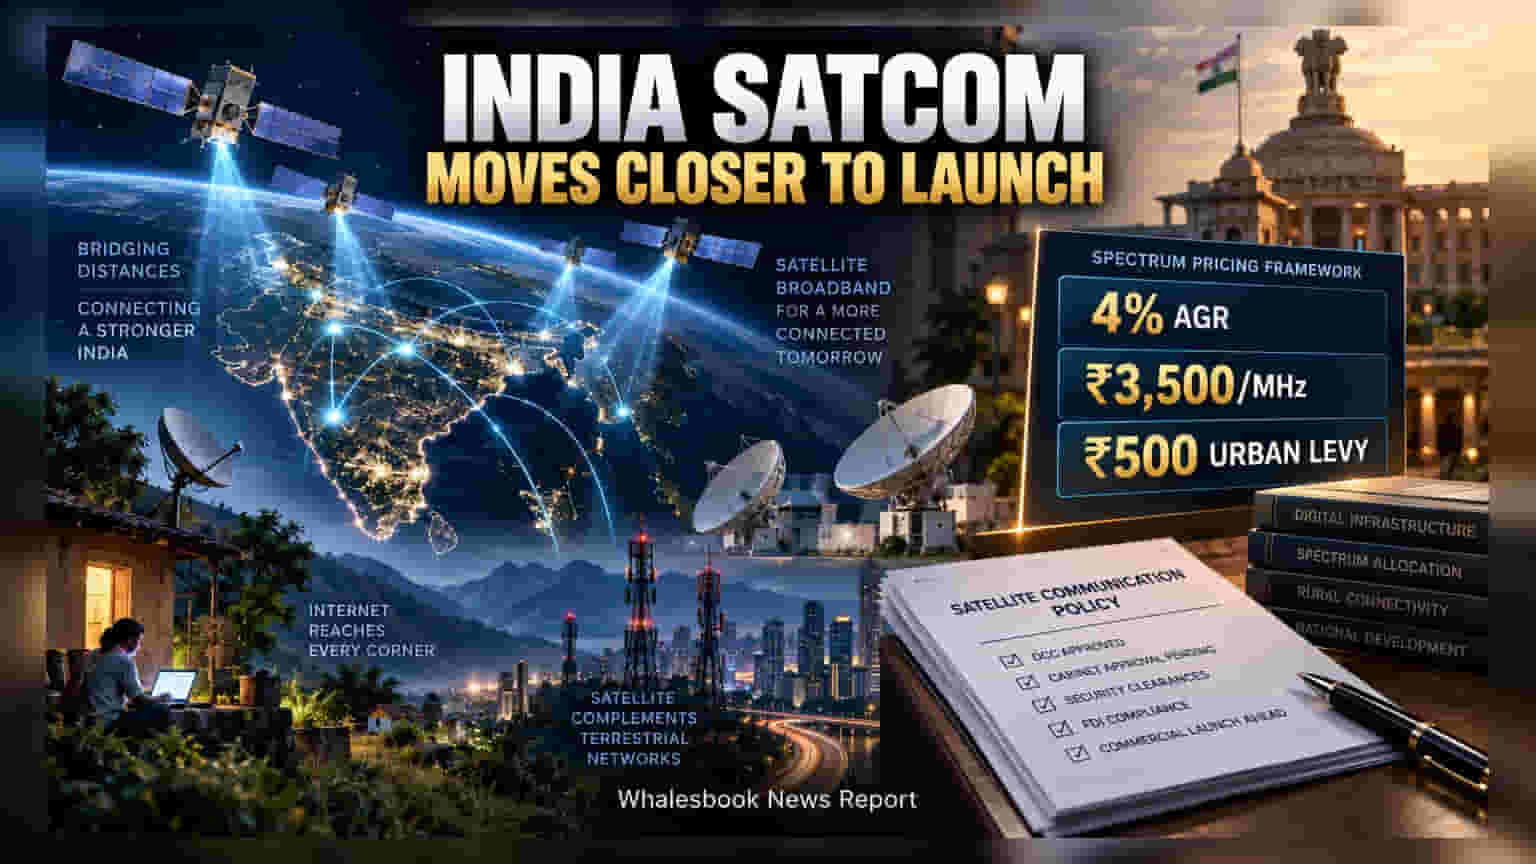
India’s satellite broadband market is closer to launch following the Digital Communications Commission's approval of a 5% revenue-based spectrum charge. Operators like Starlink, Eutelsat OneWeb, and Jio Satellite await final Cabinet clearance and security checks. While this policy milestone clarifies costs, high hardware prices and strict security requirements remain significant hurdles for commercial operations.
The Digital Communications Commission (DCC) has cleared the pricing framework for satellite communication spectrum, setting a 5% adjusted gross revenue (AGR) levy. This marks a significant step for companies like Reliance Industries’ Jio Satellite Communications, Bharti-backed Eutelsat OneWeb, and Elon Musk’s Starlink, who are preparing to enter the Indian broadband market.
The approved structure includes a 5% AGR-based spectrum usage charge, with a 1% discount applied to services provided in rural and remote regions to encourage adoption. Under the new policy, operators will be granted spectrum administratively for an initial five-year period, which can be extended by another two years. The minimum annual charge has been set at ₹3,500 per MHz.
Despite this progress, services are not launching immediately. The proposal must now receive final approval from the Union Cabinet. Furthermore, operators still need to navigate second-stage security clearances and potential foreign direct investment (FDI) compliance checks before commercial operations can begin.
The commercial viability of these services remains a central question for investors. Terminal equipment costs for satellite broadband are currently high, often ranging between ₹20,000 and ₹50,000 per unit. Operators will need to balance these high upfront costs against the ongoing revenue levies. Subsidies or lower-cost hardware solutions may be necessary to make the service affordable for a broader user base, though the current policy focus is on regulatory enablement rather than equipment financing.
Satellite internet is widely viewed as a way to connect areas where building traditional fiber-optic cables is too expensive or technically impossible. However, it is not a direct replacement for existing 5G or fiber networks. Industry capacity limits mean these services are likely to be restricted to specific applications, such as remote enterprise connectivity or government infrastructure, rather than acting as a mass-market residential substitute.
For stakeholders, the primary risks involve the timeline of regulatory approvals and the financial burden of high capital spending required to launch satellite constellations and ground stations. Ongoing security concerns regarding the placement and usage of satellite terminals, as well as adherence to Indian ownership norms, may also influence how quickly these services are permitted to expand. The next important update for investors will be the Union Cabinet’s final decision on the spectrum pricing notification. After that, the focus will shift to which operators can successfully secure their final operational licenses and complete the mandatory secondary security requirements.