

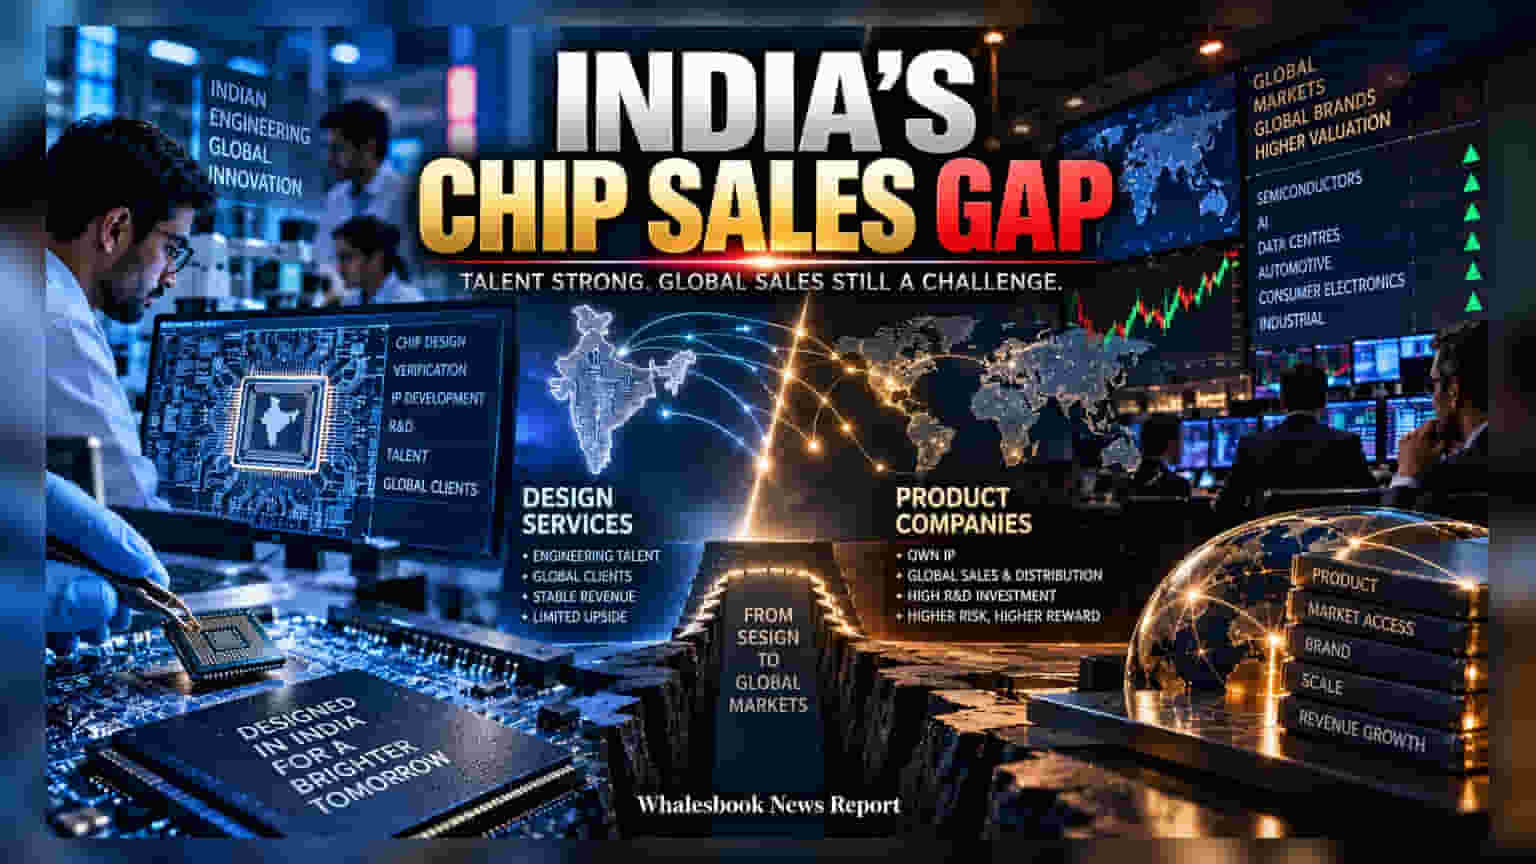
India has established itself as a hub for semiconductor design, working with global leaders like Qualcomm and Infineon. However, industry observers note that moving from a service-based model to creating scalable, home-grown chip product companies remains a significant challenge for domestic startups.
India is now a recognized center for semiconductor design. Local engineering teams have a long track record of delivering complex chip architectures for global giants, including Qualcomm, Texas Instruments, and Infineon. While this technical success highlights India’s strength in engineering, investors and market analysts point to a missing link: the ability to build and sell finished chip products in the international market.
The current model in India is heavily skewed toward design services. This means local companies often act as extended engineering arms for multinational corporations. While this business model provides stable revenue and helps build technical talent, it is fundamentally different from a 'fabless' product company model. A fabless company, like Nvidia or Broadcom, owns the intellectual property, defines the product, manages the supply chain, and handles the global marketing and sales. Moving to this model requires a different set of skills, including identifying market gaps, managing international distribution, and competing directly with entrenched global players.
Scaling a product-led semiconductor firm involves high risks. Unlike the service model, where costs are often covered by client fees, product companies must invest heavily in research and development before seeing any revenue. This creates a high cash-burn profile. Founders must secure long-term capital to sustain years of product development and testing. Furthermore, these companies are entirely dependent on third-party manufacturing facilities—known as foundries—located abroad to print their chips. Securing reliable capacity at these foundries is a complex operational challenge that adds another layer of risk.
Another challenge is the commercial execution. Designing a chip that meets technical specifications is one hurdle, but convincing global clients to adopt a new, home-grown architecture is another. This requires a strong track record, robust support ecosystems, and deep industry relationships. Currently, Indian firms often struggle to replicate the aggressive sales and strategic positioning strategies that have made global fabless companies successful.
The industry is at a crossroads where intent and talent are high, but the number of globally recognized, high-impact chip product firms is low. For investors, the distinction between a company that offers design services and one that owns proprietary chip IP is crucial. Service companies offer predictable but limited growth based on headcount, whereas successful product companies can offer high operating leverage and exponential revenue growth—provided they can execute the commercial side of the business.
Moving forward, the focus for stakeholders will be on how effectively these companies can transition their business models. Key updates to monitor include the ability of Indian firms to secure independent IP, build diversified client bases outside of just design services, and sustain the significant capital spending required for R&D and foundry access.