

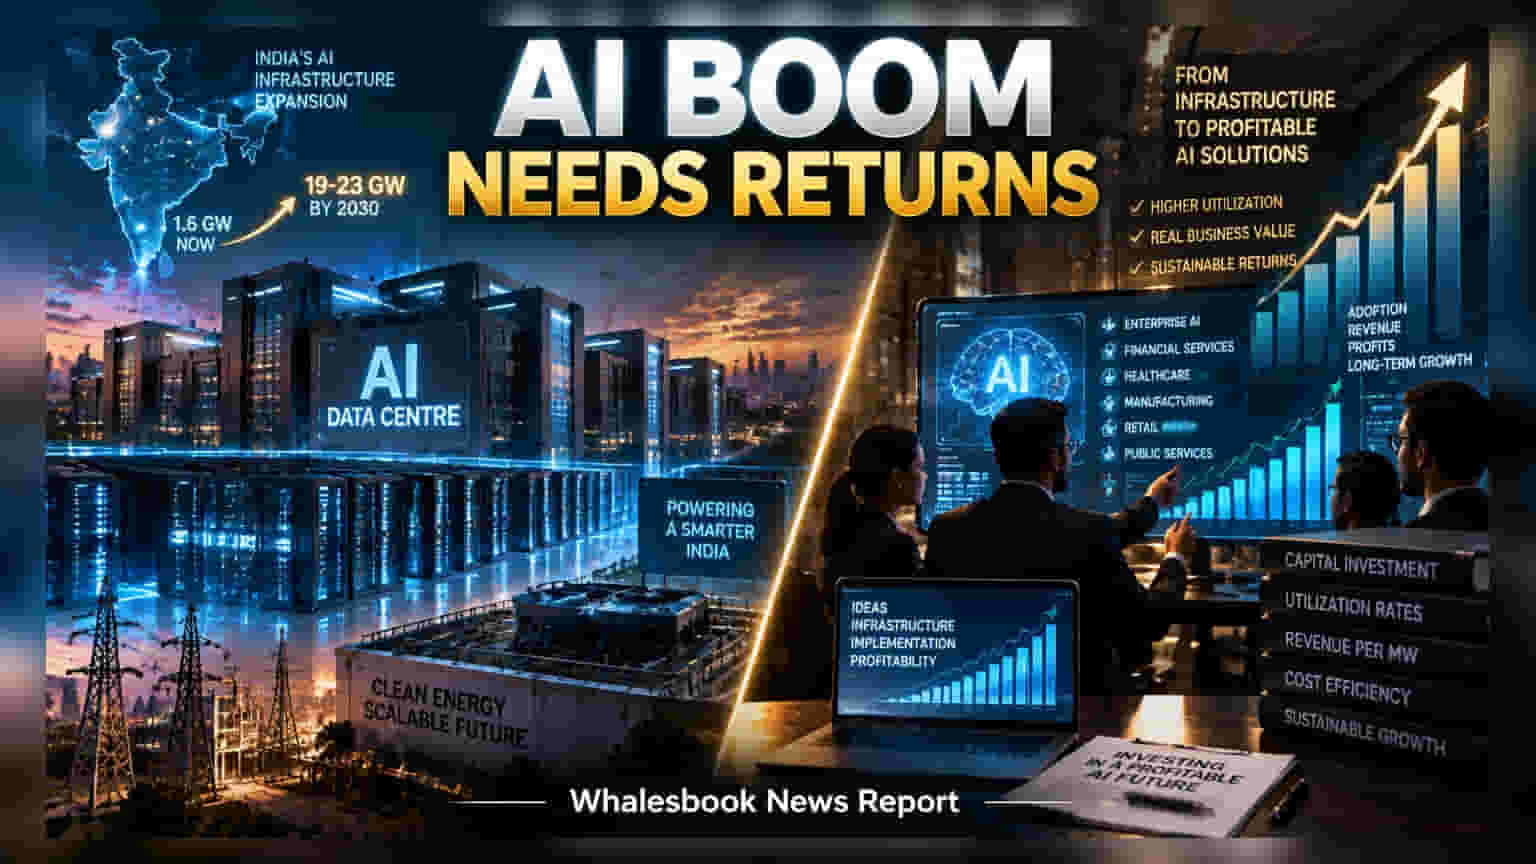
As India targets 23 GW of data-centre capacity by 2030, a new 'profitability test' has begun. While infrastructure spending is massive, recent data shows only 23% of firms see strong returns, leading investors to rotate capital from capex-heavy infra stocks toward established IT services.
India’s aggressive expansion into AI infrastructure is hitting a critical turning point. While the country is on track to scale data-centre capacity from the current 1.6 GW to a projected 19-23 GW by 2030, market sentiment is shifting as investors look for more than just physical expansion. The focus has moved toward whether this massive investment—estimated between $350 billion and $435 billion—can actually generate sustainable business profits.
This transition became visible in the stock markets on September 15, 2026. While the Nifty IT Index rallied 5%, signaling a renewed investor preference for established IT service providers that focus on AI implementation and software services, power and infrastructure companies tied to the heavy AI buildout saw selling pressure. This rotation reflects a growing caution toward companies that bear the brunt of heavy capital spending without clear visibility on returns.
The Efficiency Gap
The central challenge for the sector is that building capacity does not guarantee economic value. Analysis by CRISIL indicates that nearly half of all AI-related capital deployed between 2022 and mid-2026 went directly into infrastructure. However, a recent Dun & Bradstreet survey highlights a significant gap in productivity: while 73% of Indian businesses report achieving some returns from AI, only 23% have seen strong or broad impact across their projects.
For investors, this suggests that the 'build-it-and-they-will-come' phase of AI infrastructure is facing scrutiny. Companies that are spending heavily on data centers, cooling, and high-power computing need to prove that their clients are using these facilities for productive, revenue-generating tasks rather than just experimental workloads.
Infrastructure vs. Utility
The economics of AI are also changing as businesses differentiate between training and inference. Training AI models requires massive, concentrated computing power, but it is often a one-time intensive activity. In contrast, 'inference'—the process where AI models perform everyday tasks like customer service or fraud detection—requires constant, reliable usage. Industry data suggests that the bulk of future demand will come from inference workloads. This shift matters because data centers built solely for short-term training spikes may struggle with utilization if they cannot pivot to the constant demands of inference-based applications.
Furthermore, the total cost of ownership is rising. Beyond the initial setup, companies must manage significant expenses related to energy consumption, water usage, and data management. With data centers requiring six to seven times more capital investment per megawatt compared to traditional facilities, the margin for error in utilization is slim.
What Investors Should Track
As the sector matures, the key monitorable is no longer just how much capacity a company adds, but how effectively it uses that capacity. Investors are likely to track metrics such as utilization rates, revenue-per-megawatt, and how companies manage their high power costs.
The next phase will likely favor businesses that can demonstrate a clear link between their infrastructure spending and client revenue growth, rather than those relying purely on the size of their data-centre footprint. Monitoring management commentary on client adoption rates and operational efficiency will be crucial to understanding which companies can successfully navigate this profitability test.