

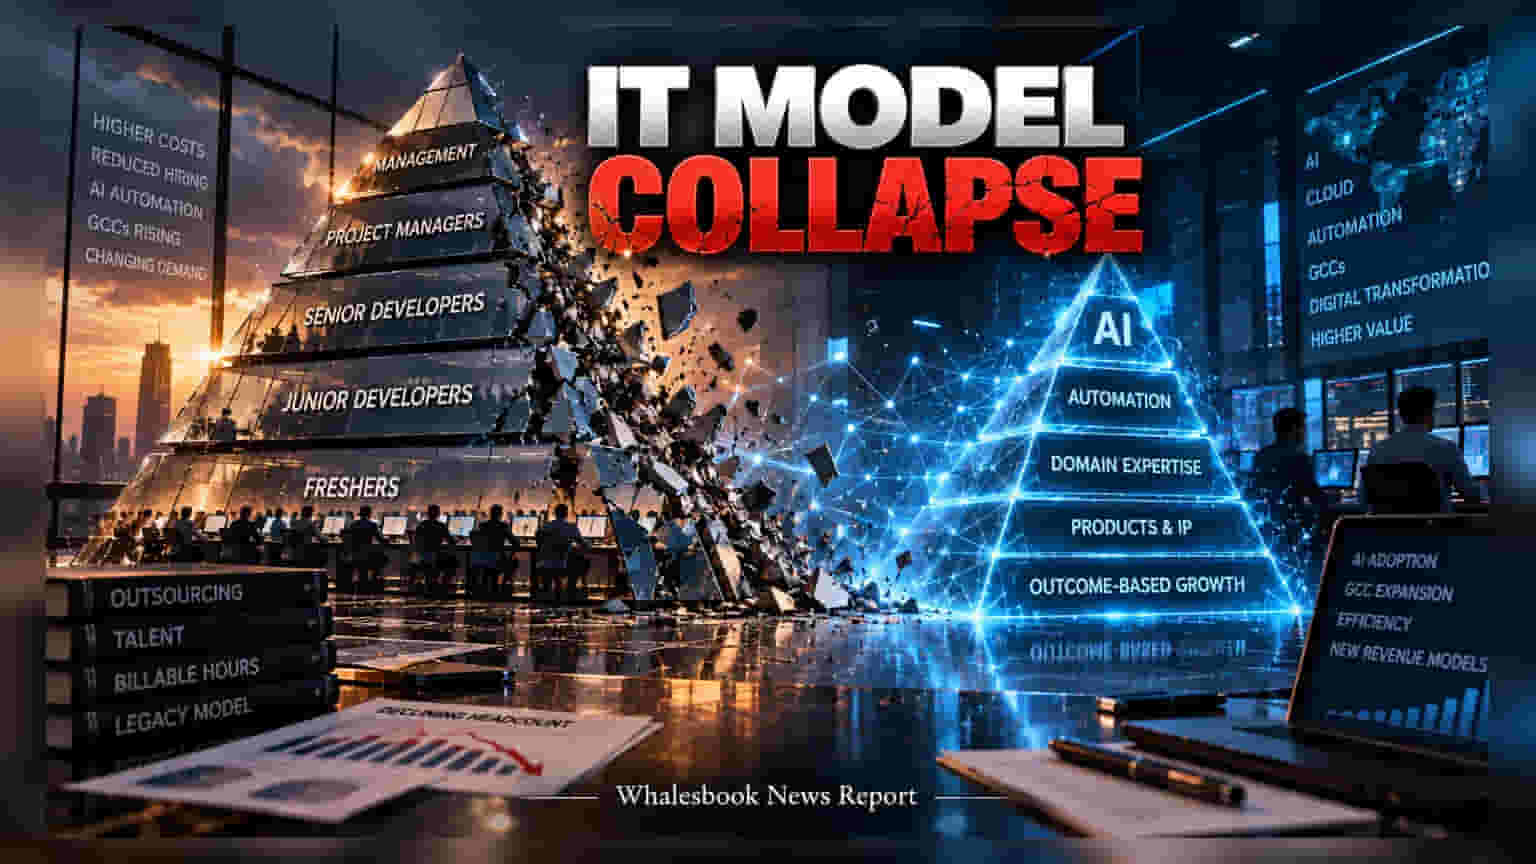
The five largest Indian IT companies saw a net reduction of 6,981 employees in FY26, signaling a structural shift as AI and Global Capability Centres (GCCs) disrupt traditional staffing models. With clients moving technical operations in-house and billing models shifting from hourly rates to outcome-based contracts, the industry faces significant pressure to reinvent its business strategies, creating potential execution risks for long-term profit margins.
The Indian IT services sector is undergoing a major structural change, highlighted by a notable drop in hiring. During the 2026 fiscal year, the five largest domestic IT firms reported a net reduction of 6,981 employees. This decline marks a break from the industry's historical reliance on the pyramid staffing model, which centered on maintaining a large base of entry-level workers to handle high-volume coding tasks. This model is now facing pressure as automation changes how technical work is delivered.
AI and the GCC Challenge
The traditional business structure is currently strained by two main factors. First, AI-driven automation is increasingly capable of managing tasks previously assigned to entry-level staff, reducing the need for large headcounts. Second, global corporations are shifting their strategies by establishing Global Capability Centres (GCCs). These in-house technology hubs allow clients to manage technical work internally rather than outsourcing it to service providers. By utilizing AI tools, these GCCs can operate with smaller, more efficient teams, effectively bypassing the need for large external service armies that were previously standard.
Transitioning to New Revenue Models
Historically, Indian IT companies generated revenue primarily through hourly billing, where profit was directly linked to the number of hours billed by employees. This model is under threat as clients increasingly demand output-based or outcome-based contracts. Transitioning to this new model is complex for service providers. Unlike the old model, which focused on scaling human capital, the new landscape requires companies to possess deep domain expertise and proprietary software tools to deliver measurable results.
For investors, the immediate challenge is that legacy revenue streams are declining while new, high-value contracts take time to materialize. While many firms are using AI tools to improve efficiency and lower costs, this may only provide temporary support to profit margins. The key monitorable for the industry will be the ability of these companies to successfully pivot toward intellectual property-led growth, rather than relying on volume-based service delivery. Success in this transition requires significant investment in research and development and a fundamental shift in business culture, which may impact cash flow and return ratios in the near term.