

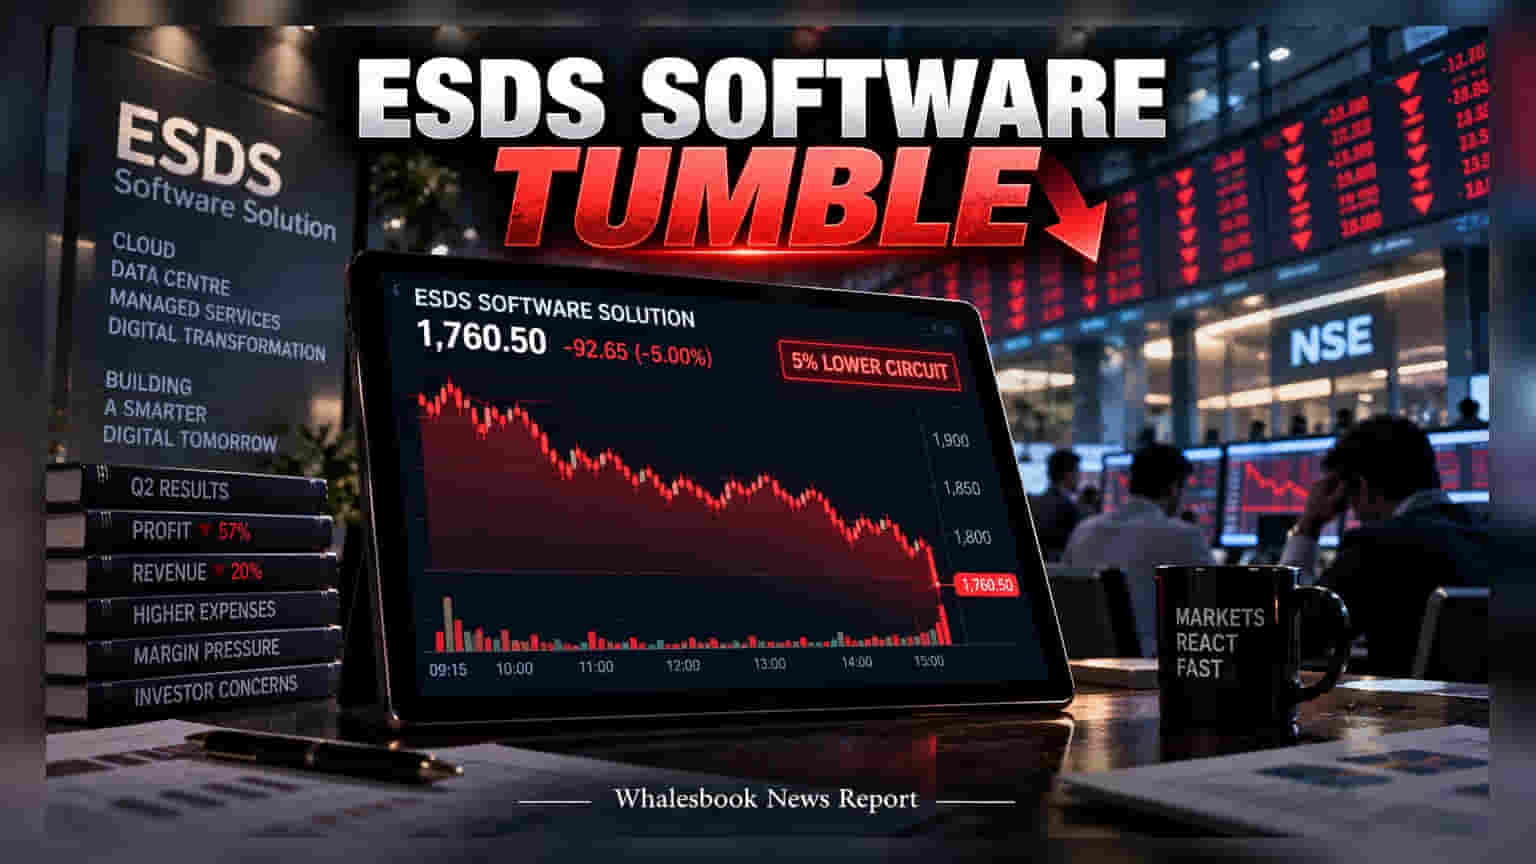
ESDS Software Solution shares locked in a 5% lower circuit on Friday following a 57% sequential drop in June quarter net profit. Revenue also slid 20% as operational costs surged. The sharp decline marks a reality check for the stock, which had rallied over 310% from its initial public offering price since listing earlier this month.
Shares of ESDS Software Solution hit a 5% lower circuit at Rs 1,760.50 during early trade on September 25, reflecting market disappointment over the company's latest quarterly performance. The sharp correction follows the release of June quarter results that showed a significant decline in profitability compared to the previous three-month period.
The company reported a consolidated net profit of Rs 29 crore for the quarter, a 57% drop from the Rs 67 crore posted in the preceding quarter. Revenue performance showed a similar trend, shrinking 20% to Rs 134 crore on a sequential basis. While the company still posted year-on-year growth with profit rising 14% and revenue climbing 7% for the same period, the immediate focus of investors has shifted to the weaker short-term numbers.
A key factor behind the profit decline is a rise in spending. Operational costs, specifically 'other expenses', surged more than 46% sequentially to reach Rs 52 crore. This jump in costs drove total expenses up nearly 17% to Rs 98 crore. For shareholders, the ability of the company to manage these costs while scaling operations will be a critical monitorable in the coming quarters.
The stock's reaction today follows a period of intense volatility and rapid growth. ESDS Software debuted on the NSE on September 4 at Rs 757, marking a 76.46% premium over its initial public offering price of Rs 429. Since listing, the stock had experienced a massive rally of roughly 310%, recently touching a 52-week high of Rs 1,864.35. Given the steep run-up, investors have become more sensitive to any signs of margin pressure or earnings weakness, which appears to have triggered the current sell-off.
Looking ahead, the long-term potential of the company depends on how well it executes in India's growing cloud-services and cloud-GPU markets. Analysts from Choice Broking have previously maintained a positive outlook on the stock based on long-term FY28 earnings estimates, though today's market reaction highlights that short-term financial performance remains the primary driver of price movement. Investors should track whether the recent rise in operational expenses is a temporary cost related to expansion or a persistent trend that could continue to compress profit margins.