

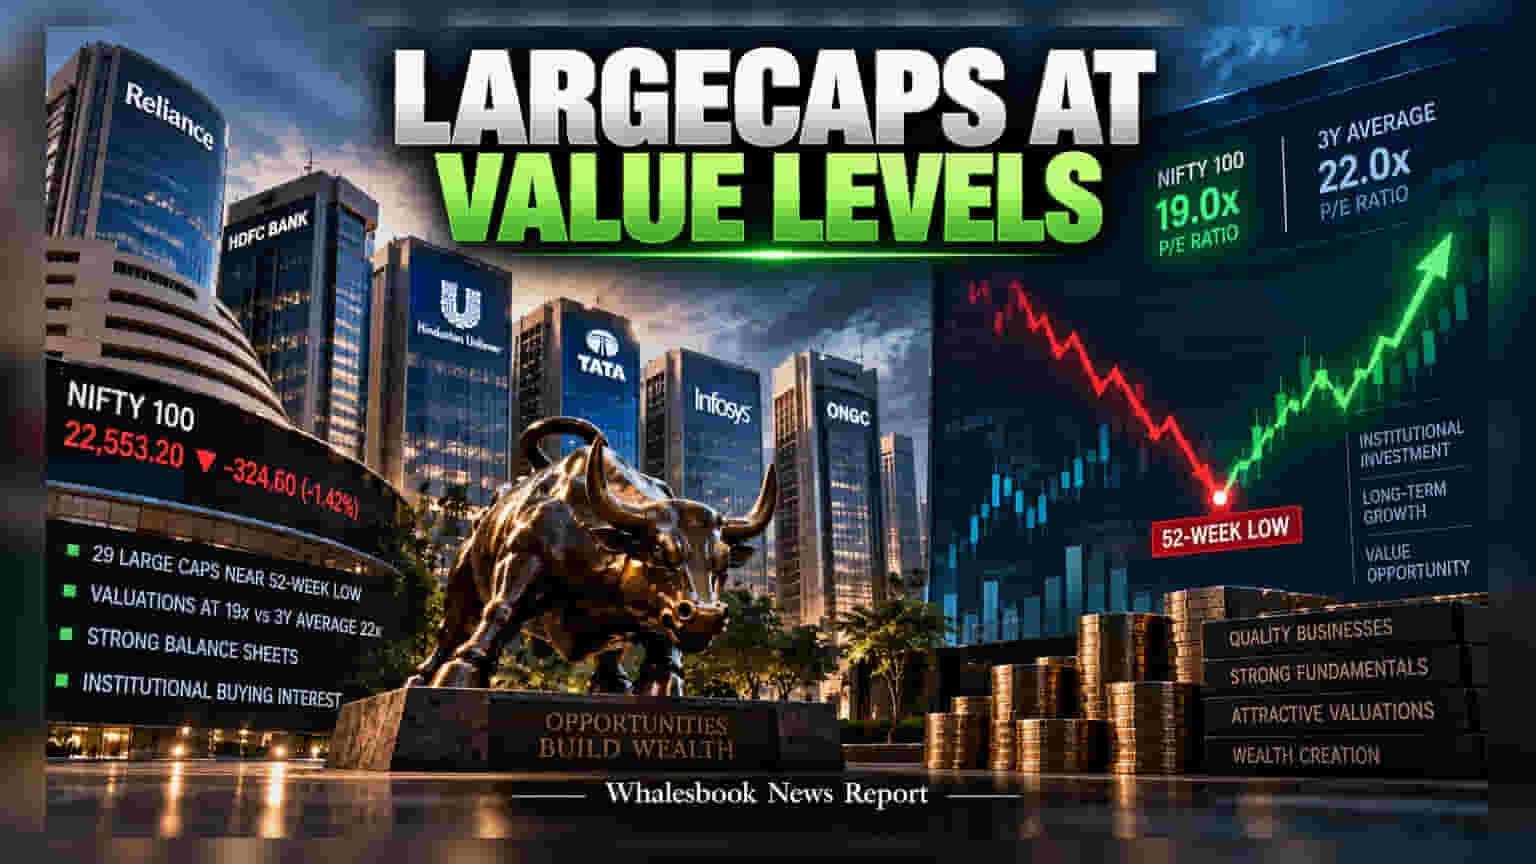
Nearly 30 large-cap stocks are trading close to 52-week lows as valuation multiples compress to 19 times earnings. This trend has sparked a debate between value investors seeking bargain buys in established firms and growth-focused investors who prefer the faster earnings expansion seen in smaller market segments.
The Indian stock market is currently witnessing a divergence in performance, with several Nifty 100 companies trading close to their 52-week lows. Data indicates that valuation multiples for these large-cap stocks have compressed, with the Nifty 100 now trading at approximately 19 times earnings compared to its three-year average of about 22 times. This shift suggests that market expectations for near-term earnings growth in these large companies have softened.
Analysis shows that around 29 of the 100 largest listed companies are currently trading within 10% of their lowest prices over the past year. This list includes prominent names such as Reliance Industries, Hindustan Unilever, Britannia Industries, Maruti Suzuki, Trent, and Power Finance Corporation. The proximity of these established firms to their yearly lows has drawn the attention of market participants, leading to a renewed debate over investment strategies.
The Case for Value Investing
Value-focused investors argue that this compression creates opportunities in companies with strong balance sheets, stable profitability, and reasonable valuations. For instance, Power Finance Corporation is often highlighted by this group due to its low price-to-book ratio and consistent profit growth. Furthermore, the potential merger between Power Finance Corporation and REC is viewed as a development that could form a massive government-backed lending entity. Similarly, some investors are eyeing companies like Oil and Natural Gas Corporation, noting that these businesses hold significant physical assets that may not be fully reflected in their current, lower stock prices.
Financial stocks have also become a point of interest. Shares like HDFC Bank are trading near 52-week lows at moderate price-to-book multiples. Supporters of this approach believe that the current valuations already factor in most of the negative risks, and any improvement in growth could provide a boost to these stocks.
The Growth Counter-Argument
On the other side of the debate, many portfolio managers maintain that a low valuation alone is not a sufficient reason to invest. They argue that some large-cap companies are facing slower earnings growth simply due to their sheer size and maturity. From this perspective, the current valuation compression is justified because these companies are struggling to grow at the same pace as younger, more agile businesses.
These investors prefer to focus on mid-cap and small-cap companies, particularly those involved in sectors like manufacturing, defense, electronics, and capital goods. They argue that these areas offer faster earnings expansion, which can justify paying a higher price. According to this view, the real long-term wealth creation is still happening in businesses that are actively benefiting from structural economic trends rather than those that have already reached a plateau.
The final performance of these stocks will likely depend on future quarterly earnings. Investors are watching closely to see whether the established large-caps can reignite their growth or if the faster-growing mid and small-cap sectors will continue to command a valuation premium in the years ahead.