

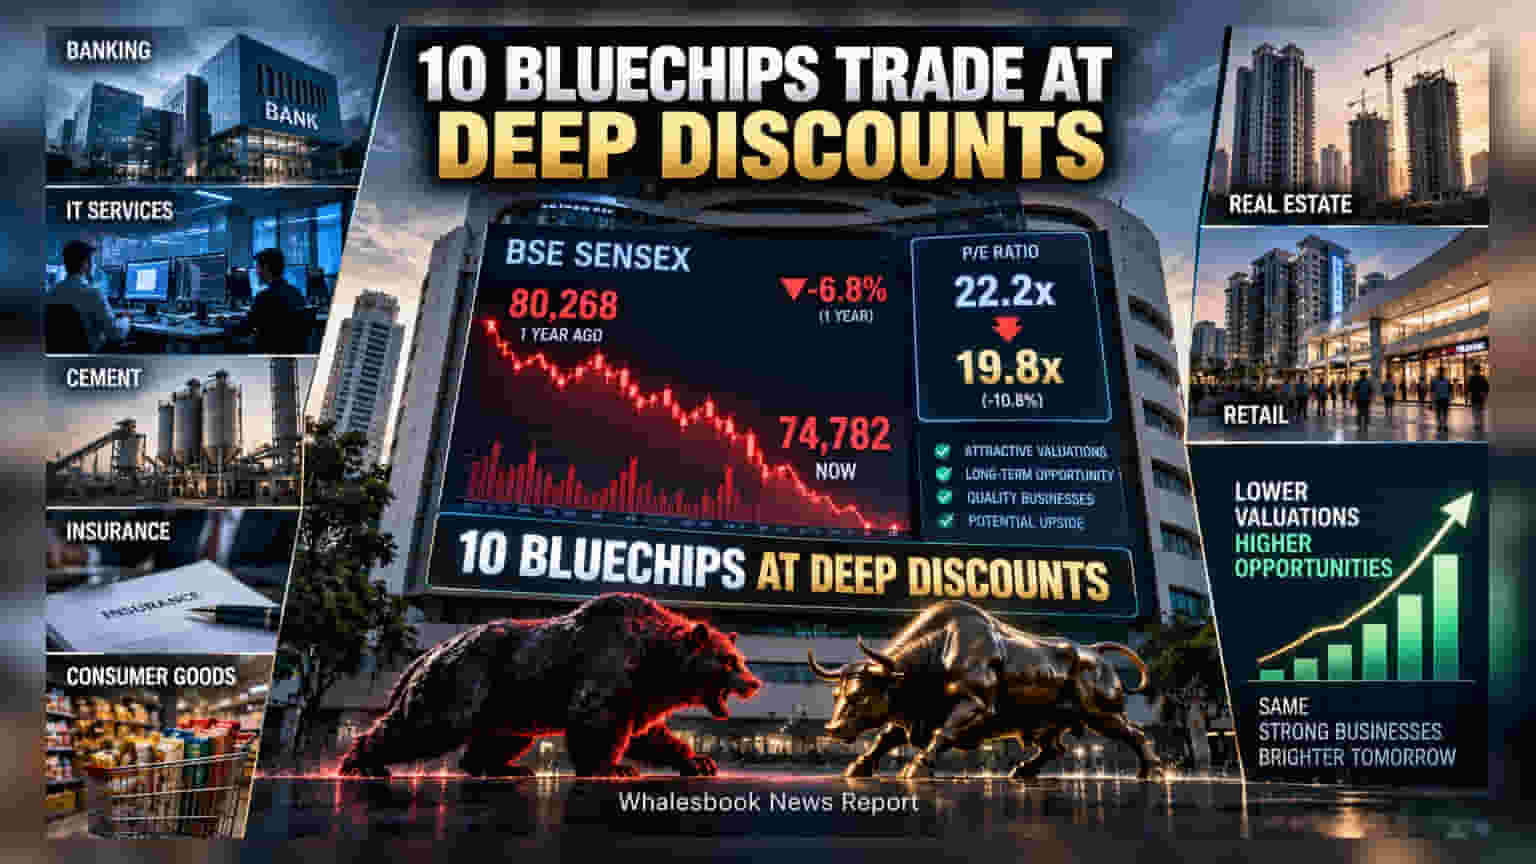
Indian bluechip stocks are seeing a sharp drop in valuations as the Sensex declines 6.8% over the past year. While several major stocks now trade below their historical averages, lower prices often reflect concerns about future earnings growth and sector-specific challenges rather than just market sentiment.
The BSE Sensex has witnessed a noticeable drop in valuation over the past 12 months, closing at 74,782. This represents a 6.8% decline for the index compared to its levels a year ago. More significantly, the market's price-to-earnings (P/E) ratio, which measures the price investors are willing to pay for every rupee of earnings, has compressed by 10.8% to 19.8x. This level is close to the valuations seen in mid-2020, signaling that investors are currently assigning lower values to the future growth potential of many large-cap companies.
This trend of valuation compression is widespread, with several well-known bluechip companies now trading at prices significantly lower than their five-year historical averages. For instance, HDFC Bank is currently trading at a price-to-book value (P/BV) about 36% below its five-year average. Similarly, SBI Cards has seen its valuation drop, trading at a 45% discount to its long-term average P/BV of 7.24x. Other examples include HDFC Life Insurance and Ambuja Cements, both of which are trading at multiples well below their own historical norms.
While these lower price points may appear attractive to some, investors should distinguish between stocks that are undervalued due to market sentiment and those that are cheaper due to fundamental business changes. The current de-rating is often tied to specific operating concerns that have lowered expectations for future profits. For example, Infosys has lowered its revenue growth guidance for FY27 to 1.5%-3.0%, citing weak discretionary spending and uncertainty around technology investment. Meanwhile, companies like Havells are dealing with elevated input costs, and Dabur faces intense competition and slower consumption in the consumer goods space.
Furthermore, the valuation discount does not automatically mean a stock is safe. Avenue Supermarts, for example, continues to trade at a high trailing P/E of 78.5x, even though it faces competitive pressure in the quick-commerce space and a slowdown in bill-size growth. This highlights that the market remains willing to pay a premium only for companies with clear earnings visibility, while penalizing those where growth is slowing.
For investors, the critical factor will be earnings recovery. Historically, periods of valuation compression have been followed by market recoveries, but these rebounds are usually driven by a return to profit growth. The main monitorable for the next few quarters will be whether companies can improve their margins and restore their growth rates. Until there is clear evidence of earnings stabilization, the lower valuations may continue to reflect the market’s caution regarding the broader economic environment and sector-specific headwinds.