

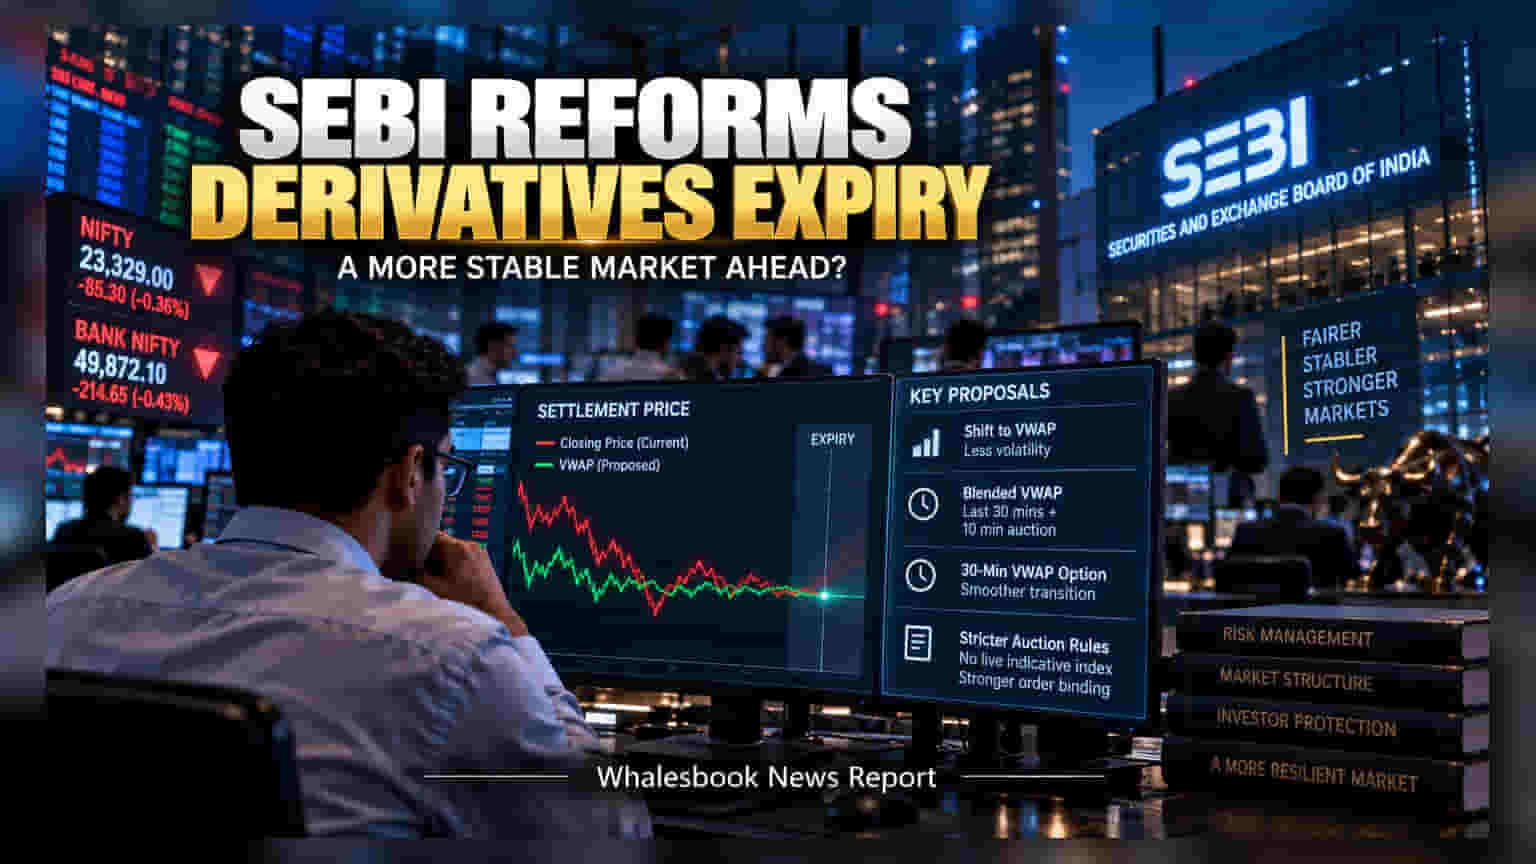
SEBI is considering changing how derivative contracts are settled on expiry days to prevent sudden price swings. The regulator aims to shift from using cash market closing prices to a volume-weighted average price, a move designed to make settlement more stable and fair for all participants.
The Securities and Exchange Board of India (SEBI) has proposed significant changes to the way derivative contracts are settled on expiry days. Currently, settlement prices are largely tied to the closing price of the cash market. This dependency can sometimes lead to sharp, unpredictable price movements in the final minutes of trading, as participants rush to adjust their positions before the market closes. To address these volatility concerns, the regulator is now seeking industry feedback on a new, more stable settlement framework.
The core of the proposal involves moving away from the cash market closing price and shifting toward a Volume-Weighted Average Price (VWAP) calculation. In simple terms, a VWAP takes into account the price of trades and the volume of shares traded at each price point, rather than just the final price of the day. This provides a more accurate reflection of the day’s market activity and reduces the impact of small, last-minute trades that can artificially sway the closing price. By using this method, the regulator intends to create a settlement process that is less prone to sudden distortions.
SEBI has presented two main options for how this new calculation could work. The first option, called Blended VWAP, would calculate the settlement price using a mix of data from the final 30 minutes of the continuous trading session and the 10-minute closing auction session. This option is designed to ensure the price reflects a broader period of market activity. The second option focuses on using only the last 30 minutes of the regular trading session for the calculation. This is intended to be a smoother transition, allowing market participants more time to adjust to the new protocols without immediate, drastic changes to their existing strategies.
Beyond these calculation shifts, the regulator is also looking to tighten the rules for orders placed during the closing auction session. There is a proposal to discontinue the display of live indicative index values during this final window, which could further prevent last-minute speculation. Furthermore, SEBI is planning to make orders placed outside the existing 1 per cent price band more binding on market participants, adding another layer of risk control to the system.
For investors and traders, these changes could mean a more predictable environment on expiry days, potentially reducing the risk of being caught in sudden, volatile price gaps. The final policy direction will depend on the feedback received from the industry and market participants. The most important next step for investors to track will be the official circular from the regulator, which will outline the chosen methodology and the timeline for its implementation across the stock and index derivatives market.