

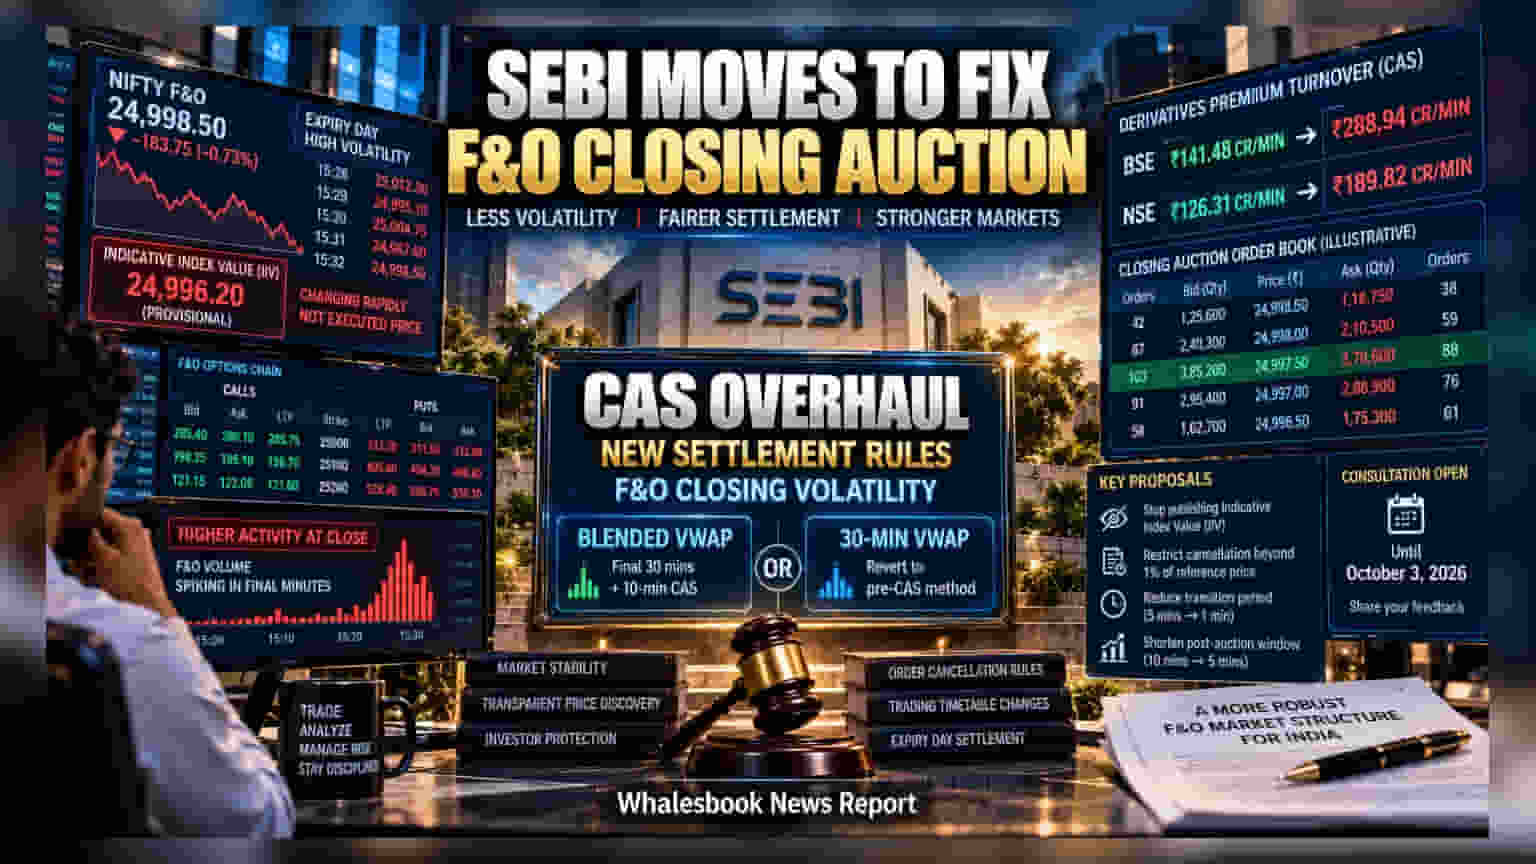
SEBI has released a consultation paper to modify the Closing Auction Session for F&O stocks following reports of sharp market volatility. The proposed changes aim to stabilize price discovery and refine derivatives settlement processes.
The Securities and Exchange Board of India (SEBI) is planning a significant overhaul of the Closing Auction Session (CAS) framework, just weeks after its implementation on August 3, 2026. This move follows market feedback indicating that the new system has led to unexpected volatility and concentrated trading activity in derivatives, particularly during the final minutes of the trading day.
Since the rollout of the CAS, exchanges—most notably the Bombay Stock Exchange (BSE)—have witnessed a massive surge in trading volume during the closing window. Data shows that derivatives premium turnover during this period spiked significantly, raising concerns about the potential for artificial price swings and market instability on expiry days.
To address these challenges, SEBI has proposed a seven-point plan in a consultation paper released on September 12, 2026. The regulator is currently seeking public feedback on these measures until October 3, 2026.
One of the most critical changes involves the settlement of index and single-stock derivatives. Under the current setup, traders have faced confusion due to the Indicative Index Value (IIV) displayed during the auction. This number changes rapidly as orders are placed or cancelled, creating a signal that may not represent actual executed trades. SEBI proposes to stop publishing this value during the auction to prevent traders from reacting to potentially misleading price signals.
For expiry days, the regulator has suggested two potential paths. The first is to implement a blended Volume Weighted Average Price (VWAP) that combines data from the final 30 minutes of continuous trading and the 10-minute CAS period. The second alternative is to revert to the pre-CAS method for a year, which relies solely on the last 30 minutes of continuous trading. This change is intended to make the final settlement price of futures and options contracts more reflective of genuine market activity.
SEBI is also looking to tighten the rules for order cancellations. Currently, extreme orders can be placed and pulled out quickly, which can disrupt price discovery. The proposed rule would prevent the cancellation of orders placed beyond 1% of the reference price, though traders would still be able to modify these orders to improve prices. This is designed to reduce the risk of manipulation while still allowing for legitimate trade execution.
Additionally, the regulator is considering a tighter trading timetable. The current five-minute transition period between standard trading and the CAS could be reduced to just one minute. Furthermore, the derivatives trading window after the auction might be shortened from 10 minutes to five minutes to keep market activity more focused.
These proposals represent a significant attempt to fine-tune the market structure. For investors and traders, the key monitorable will be how these changes affect expiry day execution and whether they successfully dampen the volatility that has defined the post-August period.