

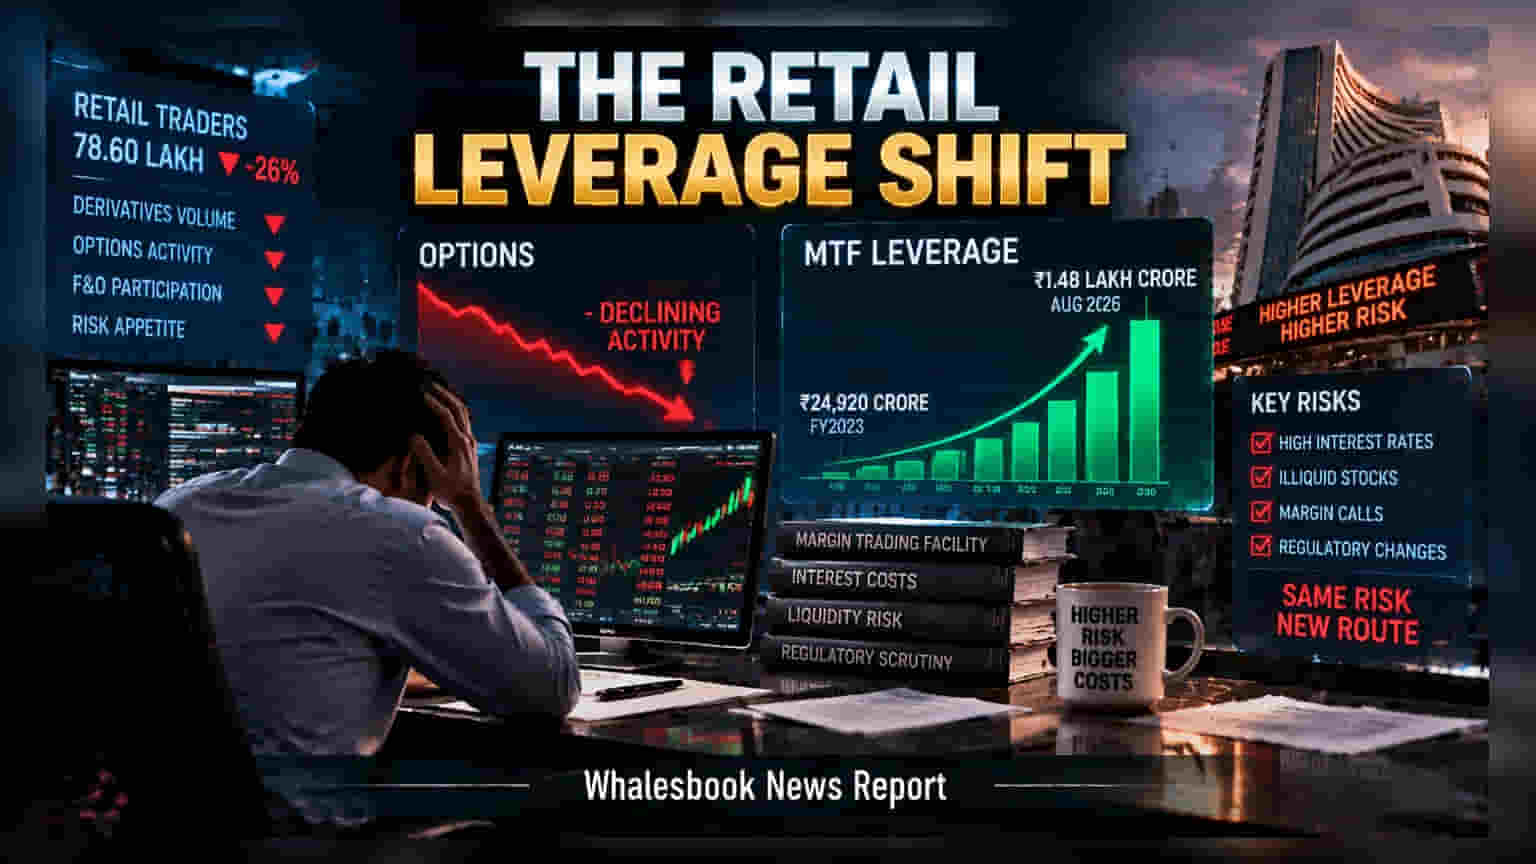
Indian retail investors are moving from equity derivatives to Margin Trading Facilities (MTF), pushing the margin book to a record ₹1.48 lakh crore. While this shift reduces immediate derivatives speculation, it introduces long-term risks, including high interest costs and exposure to illiquid small-cap stocks that can be difficult to sell during market downturns.
The Indian stock market is witnessing a significant change in how retail investors use leverage. As regulatory scrutiny of equity derivatives increases, capital is migrating toward Margin Trading Facilities (MTF). The total value of loans extended under MTF has reached a record ₹1.48 lakh crore as of mid-August 2026, a substantial rise from the ₹24,920 crore reported in fiscal year 2023. While the number of unique retail traders in the derivatives segment has declined to 78.60 lakh for the 2026 fiscal year, this movement indicates that speculative appetite remains high and has simply shifted into a different instrument.
The Hidden Costs of Long-Term Leverage
Many investors view MTF as a tool to increase their purchasing power for delivery-based trades. However, this strategy carries a 'carry cost' that is frequently underestimated. Unlike futures and options contracts, which have specific expiry dates that force traders to exit or roll over positions, MTF positions can be held for much longer periods. Because these positions are funded by borrowed money, investors are charged interest, which often hovers near 15% annually. This financing cost acts as a silent drag on returns. Even if a stock price stays flat, the accruing interest creates a loss that may not be immediately visible, potentially turning a neutral investment into a losing one over time.
Risks of Illiquid Assets
A large portion of the current margin debt is concentrated in stocks that do not have listed derivatives, which typically includes many mid-cap and small-cap companies. These stocks often face liquidity challenges during market stress. If a stock hits a 'lower circuit'—a point where buyers vanish and trading is halted—brokers may be unable to liquidate the pledged shares to recover the loan amount. This creates a significant risk for both the brokerage and the investor, who may find themselves trapped in a position they cannot exit. Current trading platforms often emphasize how much additional purchasing power an investor has, which may obscure the true cost and risk of the accumulated debt.
Regulatory Focus on Transparency
The Securities and Exchange Board of India (SEBI) is currently evaluating structural reforms to improve transparency and stability in this segment. Proposed measures include higher net-worth requirements for brokers and standardized reporting frameworks. These changes aim to ensure that brokers can handle potential defaults and that investors are better informed about their risks. For investors, the most important monitorables include the total interest rate being charged on the margin book, the liquidity of the stocks in their portfolio, and the ability to exit positions if prices fall suddenly. Keeping track of upcoming regulatory updates regarding margin trading transparency will be crucial for understanding potential changes in leverage limits and reporting requirements.