

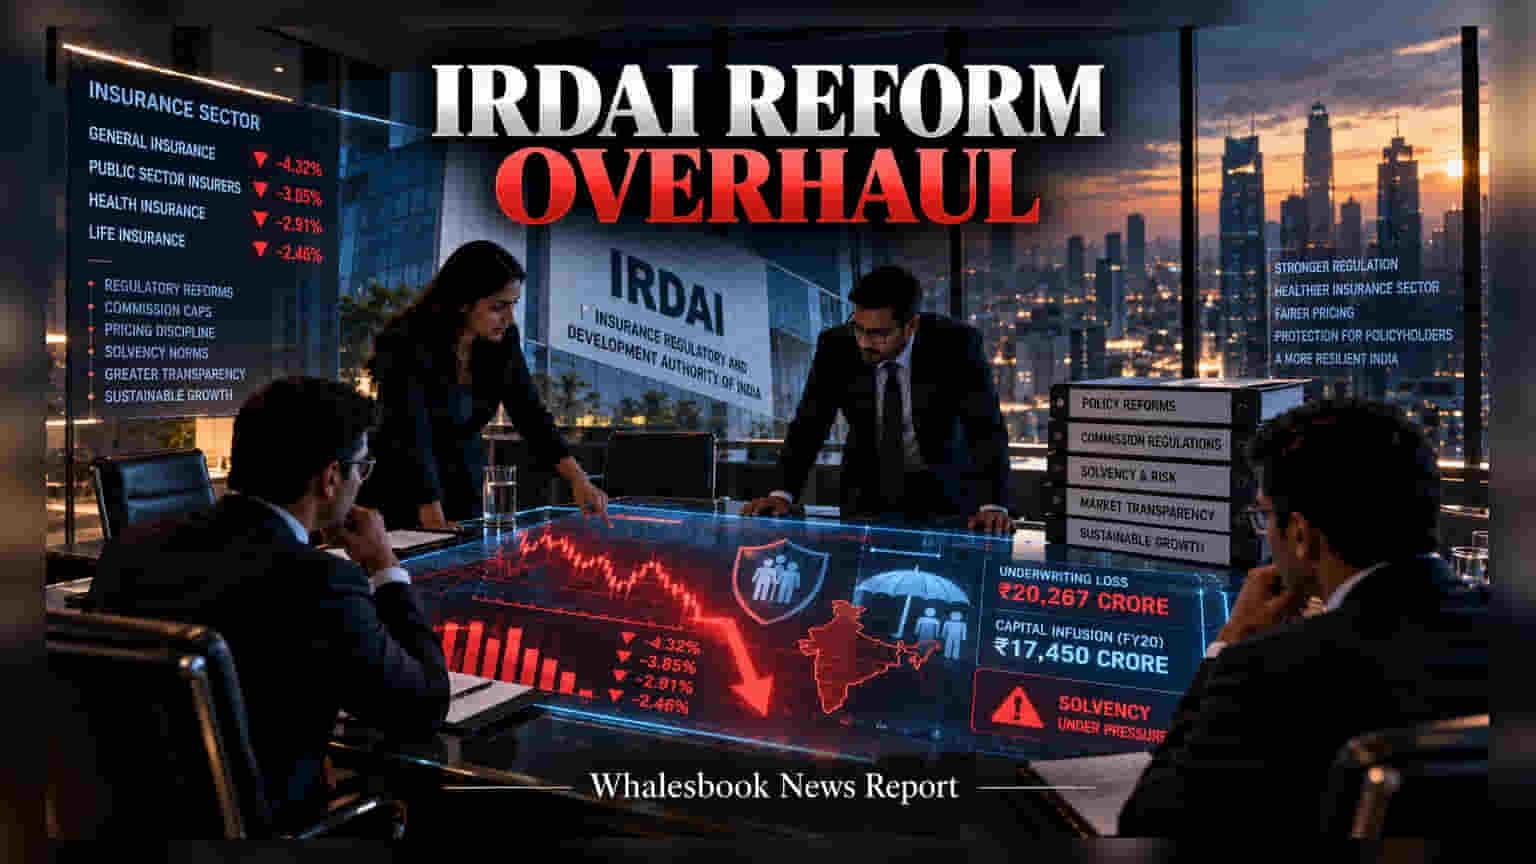
India’s insurance regulator is launching a structural review to fix excessive intermediary payouts and aggressive underpricing. The move follows industry-wide underwriting losses of ₹20,267 crore in FY26 and repeated solvency concerns among public sector insurers. The new rules aim to boost transparency and stabilize financial health across the sector.
The Insurance Regulatory and Development Authority of India (IRDAI) is initiating a significant regulatory overhaul designed to address structural weaknesses in the insurance industry. The regulator is preparing a framework to tackle aggressive market behaviors that have eroded profitability across the sector, with a specific focus on controlling commission payouts and unsustainable pricing strategies.
Financial Stability and Underwriting Losses
The need for this reform is driven by persistent financial pressure. In the fiscal year 2026, the general insurance industry reported underwriting losses totaling ₹20,267 crore. Despite capital injections of ₹17,450 crore since FY20, several public sector insurance firms have struggled to maintain the required solvency ratios, with three major state-owned companies breaching these norms repeatedly throughout the 2025-26 fiscal year. The regulator’s new approach intends to move away from historical enforcement methods toward a stricter, risk-based solvency system that directly links penalties to the severity of violations.
Impact on Pricing and Intermediaries
A central goal of this overhaul is to stop the 'race to the bottom' in product pricing. Insurers have frequently slashed premiums to gain market share, leading to extreme scenarios such as 99% discounts on standard rates in the fire insurance segment. By setting new commission caps and stricter disclosure norms, the IRDAI aims to shift the market toward pricing based on actual risk rather than aggressive acquisition tactics.
Furthermore, the regulator is targeting the distribution channel, which has been identified as a bottleneck for transparency. Market data reveals that just 10 brokers control 70% of the general insurance market. The new guidelines will likely mandate granular disclosures regarding intermediary payments, including indirect commissions often categorized under marketing expenses. This is intended to expose hidden costs and help bridge the trust gap between policyholders and insurers.
Investor and Market Outlook
The move toward Indian Accounting Standards (Ind AS) and the integration of data with the Financial Stability and Development Council (FSDC) are designed to end valuation arbitrage. Currently, some companies mask poor underwriting performance through complex accounting. By standardizing reporting across banks, non-banking financial companies, and insurers, the government hopes to create a more resilient environment.
For investors, the immediate monitorable is how these changes affect the profit margins of general insurance companies. While better discipline may improve long-term profitability, companies that rely heavily on aggressive pricing to grow market share may face near-term pressure. The next steps to track include the official notification of the revised commission caps and the implementation timeline for the new risk-based solvency requirements.