

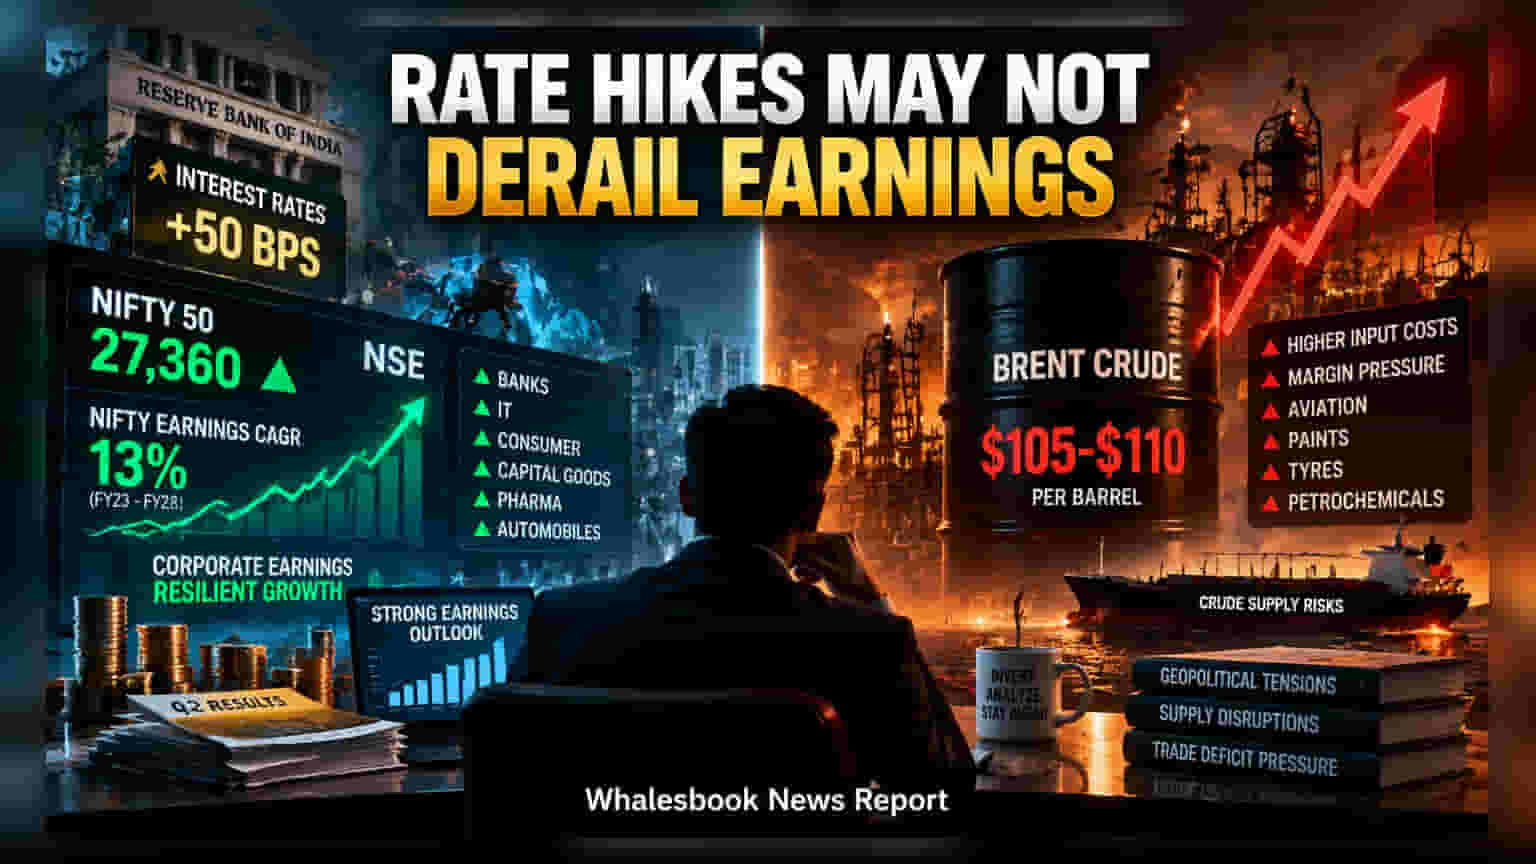
Axis Securities maintains a positive outlook on Indian earnings, setting a December 2026 Nifty target of 27,360. While analysts believe the market can absorb potential interest rate hikes, they warn that the recent surge in Indian crude oil prices to nearly $129 per barrel poses a more immediate threat to corporate profit margins.
Indian corporate earnings are expected to remain on a solid growth path even if the central bank chooses to increase interest rates, according to the latest analysis from Axis Securities. The firm projects a 13% compound annual growth rate for Nifty earnings between FY23 and FY28, supporting its raised December 2026 target of 27,360 for the index. Analysts argue that a potential 50-basis-point increase in policy rates would likely be manageable, as much of this expected adjustment has already been factored into bond market prices.
However, the focus for investors is shifting from interest rates to the volatile energy market. While earlier forecasts suggested crude oil prices might stabilize around $105-$110 per barrel, the reality has been more challenging. As of mid-September 2026, the Indian crude oil basket has climbed toward $128.70 per barrel, driven by geopolitical tensions in the Middle East and disruptions to transit routes. This rise creates a difficult environment for companies, particularly in sectors like aviation, paints, tyres, and petrochemicals, which rely heavily on energy and oil-based raw materials.
For many companies, these high input costs represent a significant hurdle. If energy prices remain at these elevated levels for an extended period, it may force analysts to downgrade their profit forecasts. Unlike interest rates, which the market can often anticipate, oil price shocks act as an immediate squeeze on profit margins for businesses that lack the power to easily pass on these costs to customers. The potential widening of the trade deficit due to these import costs also remains a concern for the broader economy.
Mid-cap and small-cap stocks also face a critical period. Following strong performance in the June quarter, valuations in these segments have reached high levels. With expectations set high, these companies are now under pressure to deliver consistent earnings growth. Any failure to meet these targets in the coming quarters could lead to sharp price corrections, as investors re-evaluate whether these valuations are still justified.
Investors should monitor upcoming quarterly results closely, specifically looking at how management teams plan to handle rising raw material costs and energy expenses. The key monitorable will be whether companies can protect their profit margins despite the ongoing pressure from high crude prices and whether consumer demand remains strong enough to support earnings growth in a high-interest-rate environment.