

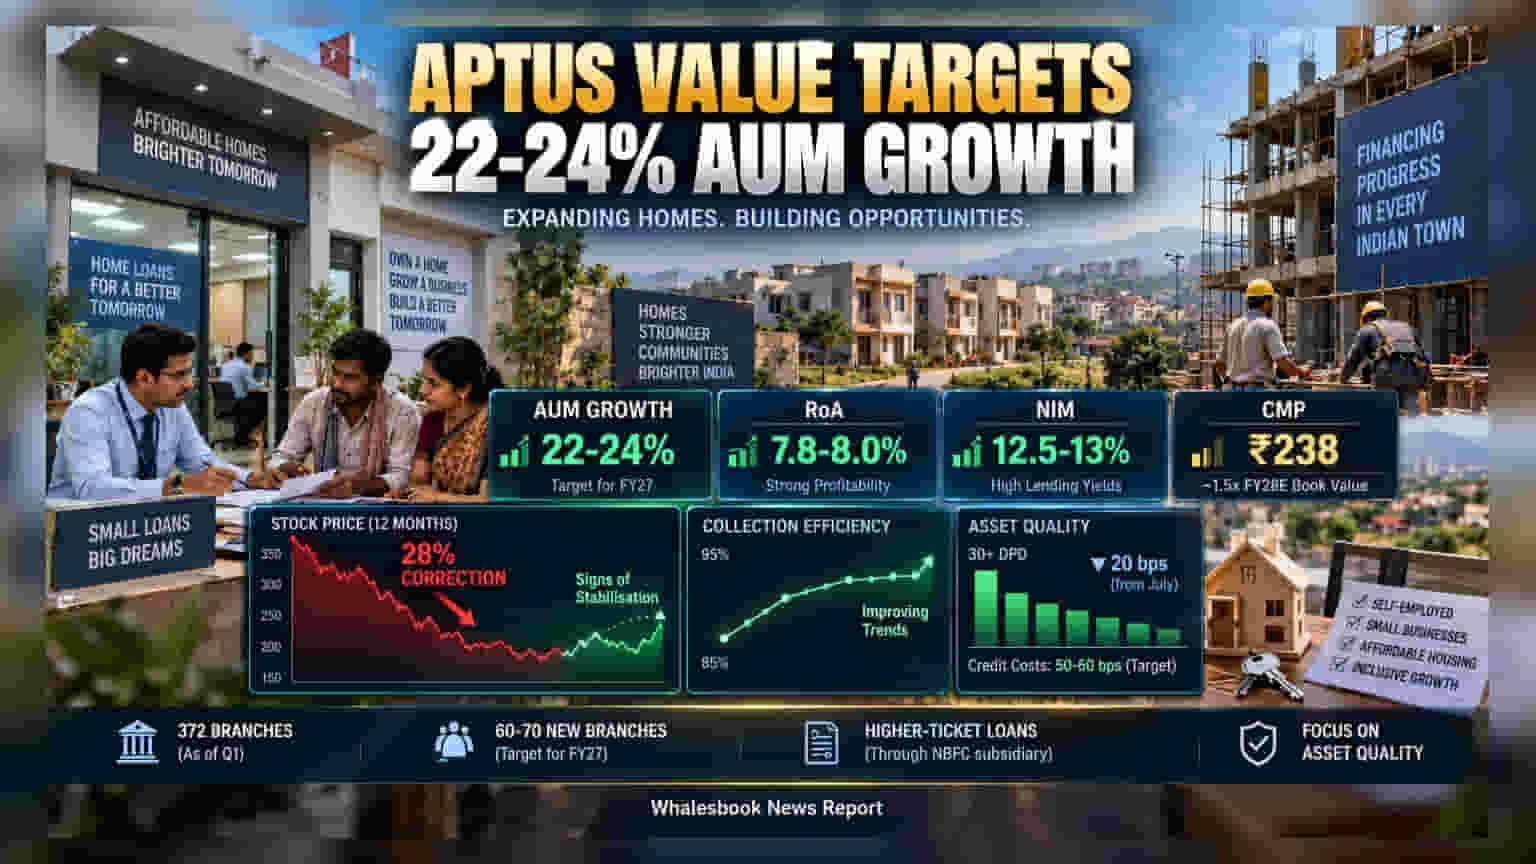
Aptus Value Housing Finance targets 22-24% asset growth for FY27 as collections improve. Following a 28% stock price correction, the company is valued at roughly 1.5 times its FY28 book value. Investors should watch for risks related to geographic concentration and borrower quality in the coming quarters.
Aptus Value Housing Finance India is navigating a period of recalibration, aiming for asset growth of 22-24% in the financial year 2027. The company's stock has faced a notable correction of about 28% over the past twelve months, a shift that has brought its valuation to approximately 1.5 times the estimated book value for FY28.
The lender is focused on expanding its network to drive business momentum. As of the first quarter, the company operated 372 branches, following the addition of 33 new locations. Management is aiming for a total addition of 60 to 70 branches during the full financial year. The company is also testing a higher-ticket loan product through its NBFC subsidiary to supplement its traditional lending business, which currently forms a significant portion of its assets.
Asset quality remains a primary area of focus for the management team. While the company saw rising delinquencies and non-performing assets earlier in its NBFC portfolio, recent collection efforts have started to provide stability. Data from July showed a reduction in the 30-plus-days-past-due metric by 20 basis points, suggesting that collection measures are beginning to yield results. Credit costs, which were around 60 basis points in the first quarter, are expected to stay within a range of 50-60 basis points, provided collection trends remain positive.
The company’s ability to maintain high lending yields continues to support its profitability. Its non-housing products typically yield between 17% and 20%, while housing loans offer 14-14.5%, leading to a combined yield of roughly 17%. With borrowing costs easing following a credit rating upgrade, the company is targeting net interest margins between 12.5% and 13%. Operating costs also remain within management's guidance of 2.6% to 2.8% of assets, helping the company maintain a high return on assets of 7.8% to 8.0%.
Despite these operational metrics, the company faces inherent risks that investors should monitor. A significant portion of the loan book is concentrated in southern India. Furthermore, the company lends to self-employed individuals and those in potentially vulnerable income segments. Future performance will depend on the company's ability to maintain its aggressive growth guidance while managing the quality of its loan book. Investors may follow quarterly updates on collection efficiency, loan disbursement growth, and any shifts in asset quality, particularly within its non-housing loan segment.