

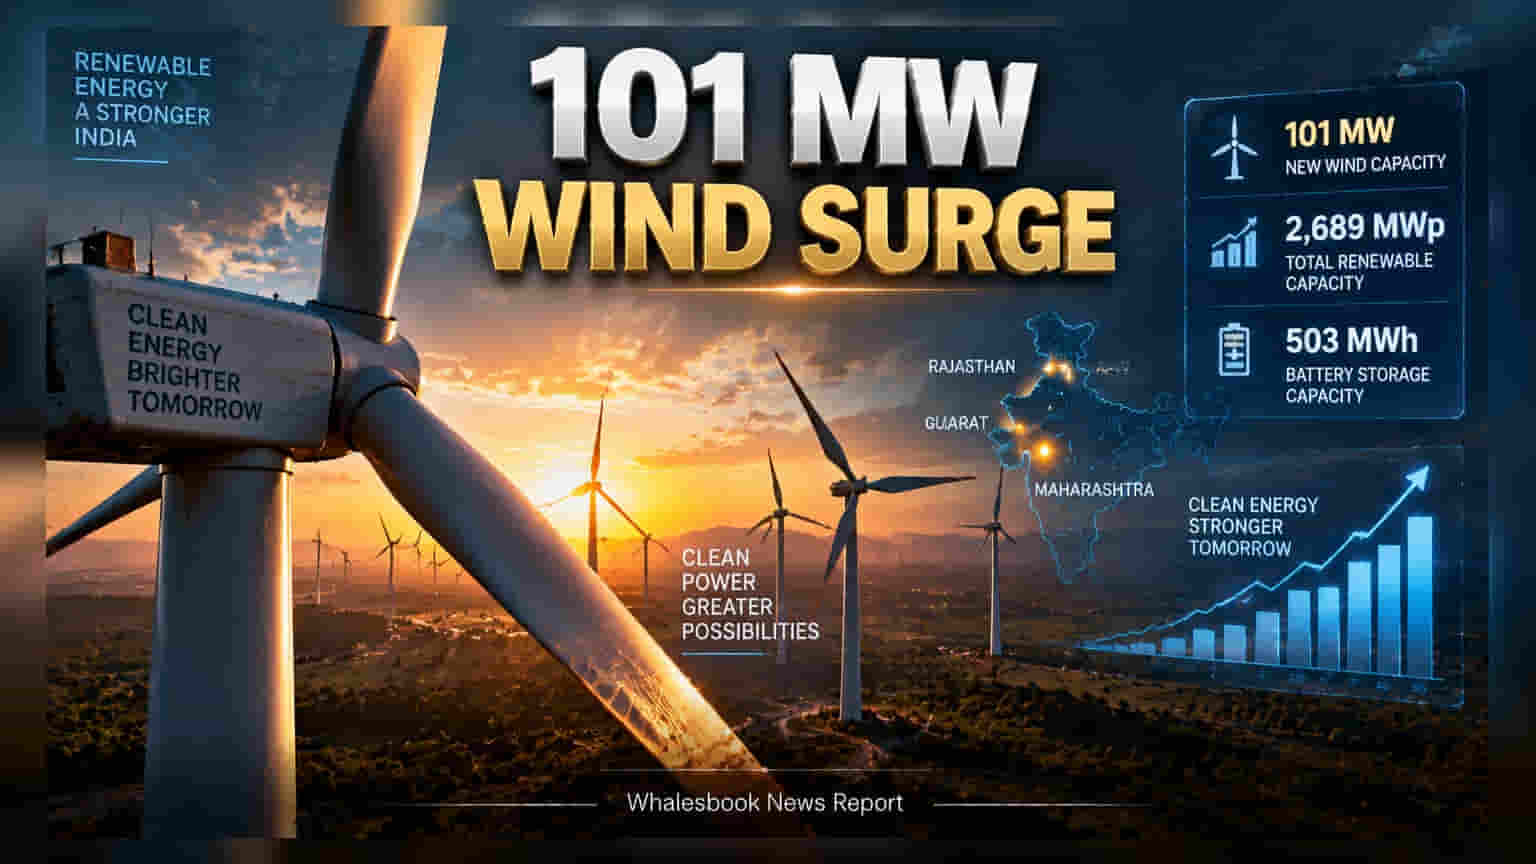
Juniper Green Energy has commissioned 101 MW of new wind capacity across three states, pushing its total operational portfolio to 2,689 MWp. While the early completion of key projects marks a positive operational milestone following its August 2026 IPO, investors should monitor the company’s high debt-to-equity ratio and execution risks tied to its large under-construction pipeline.
Juniper Green Energy has increased its operational footprint by commissioning 101 MW of new wind capacity across Gujarat, Maharashtra, and Rajasthan. This development, occurring in the first half of September 2026, expands the company's total renewable capacity to 2,689 MWp, supported by 503 MWh of battery energy storage system (BESS) capacity.
A standout in this capacity expansion is the full commissioning of a 75 MW hybrid project in Maharashtra. The company completed this project for the Maharashtra State Electricity Distribution Company (MSEDCL) two months ahead of the planned timeline. Such early completions are generally positive for cash flow and contract adherence, especially in the capital-intensive renewable energy sector where project delays can increase borrowing costs and impact project returns.
This expansion follows the company’s stock market debut on August 6, 2026, after raising ₹1,800 crore through an initial public offering. The fresh capital is a critical part of the company's plan to fund its growth and manage its balance sheet. However, the company continues to operate with a high debt-to-equity ratio, which has been reported near 401%. Managing this level of debt while scaling operations will be a balancing act for the management.
While the company is growing its capacity, its financial health reflects an early-stage business profile. Recent performance data indicates a return on net worth (RoNW) of approximately 1.18%. The company is also managing an under-construction pipeline of over 6,000 MW. Delivering this large pipeline on time and within cost estimates is a significant execution risk, as project delays or cost overruns could put pressure on the company's financial flexibility.
Looking ahead, investors may track how the company uses its IPO proceeds to reduce leverage and whether it can improve its return ratios as more capacity becomes operational. The consistency of performance across its current 2,689 MWp portfolio and progress on the 6,000 MW construction pipeline will be key indicators of how the company balances growth with debt management.