

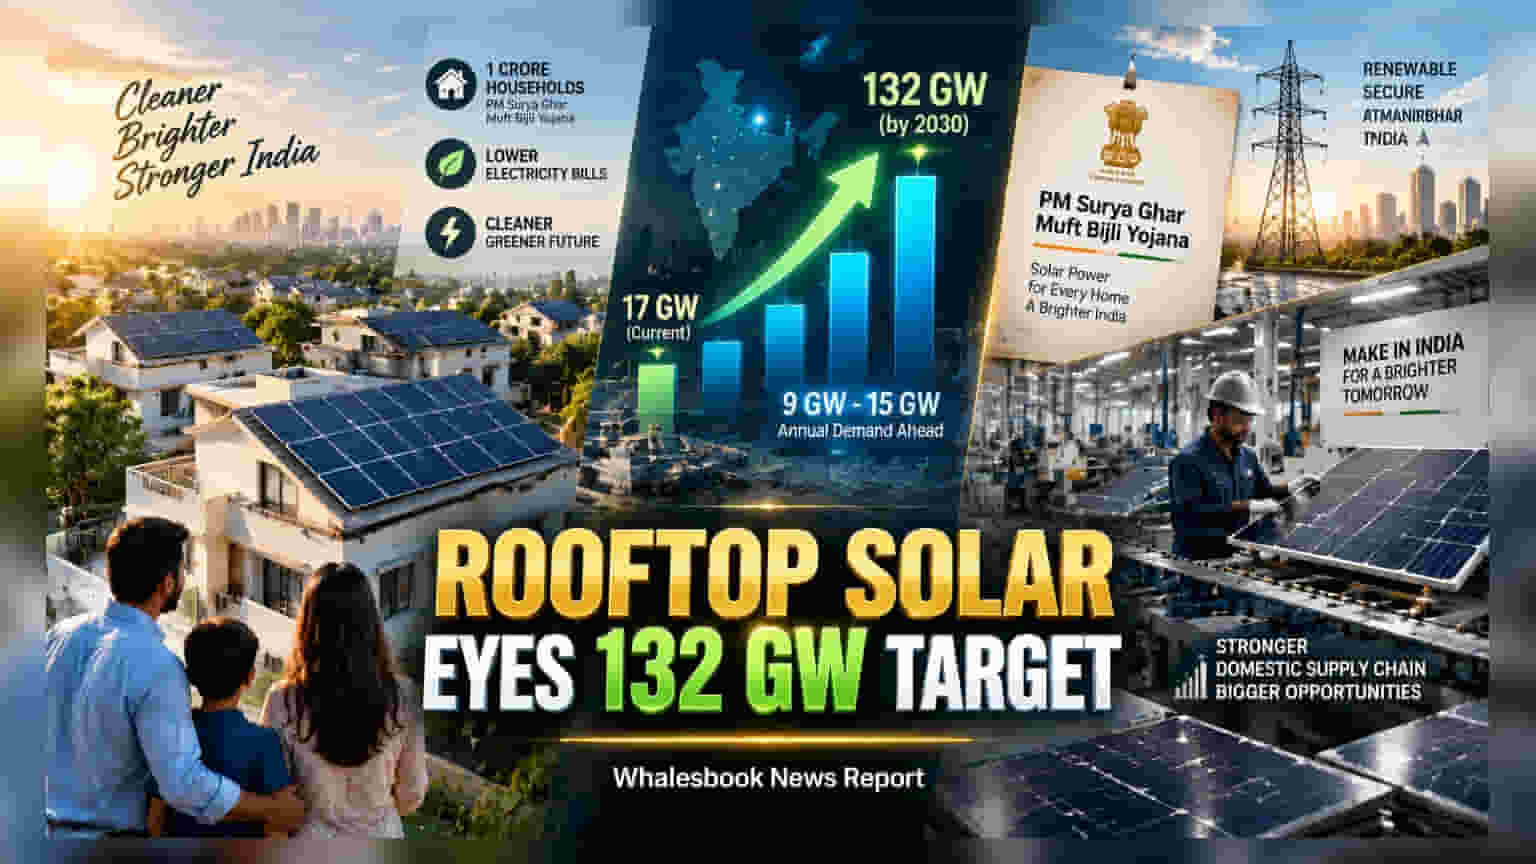
The Indian Solar Manufacturers Association (ISMA) projects the rooftop solar market may grow to 132 GW by 2030, up from 17 GW currently. This expansion is driven by the PM Surya Ghar scheme, creating demand for domestic components. Note: ISMA is an industry body, not a publicly listed company.
The Indian Solar Manufacturers Association (ISMA) has released a new projection estimating that India’s rooftop solar market could expand to 132 GW by 2030, a significant jump from the current installed capacity of approximately 17 GW. The industry body forecasts that annual demand for rooftop solar installations could range between 9 GW and 15 GW over the coming years.
This growth outlook is primarily driven by residential adoption, supported by the central government’s PM Surya Ghar Muft Bijli Yojana. This scheme aims to bring rooftop solar to one crore households by March 2027, effectively pushing solar adoption into markets where the economics were previously considered less attractive for consumers.
Investors should note that ISMA is an industry association representing manufacturers and is not a publicly traded company. It should not be confused with listed entities such as Solar Industries India Limited, which operates in entirely different segments. The ISMA report serves as an industry-wide outlook rather than a corporate financial update.
For investors following the renewable energy space, this projection highlights the potential for sustained demand in the domestic solar supply chain. Companies involved in manufacturing solar modules, cells, inverters, and balance-of-system equipment may see volume benefits if the projected 9-15 GW annual demand materializes. Government policies, such as the Approved List of Models and Manufacturers (ALMM), are designed to prioritize local sourcing, which can support domestic manufacturers against low-cost imports.
However, the path to 132 GW faces specific challenges. A primary concern is policy continuity. Current subsidy frameworks are largely tied to targets set for March 2027. Market participants and industry players will be closely watching for signals regarding a potential extension or a 'Surah Ghar 2.0' phase. Without clear policy visibility beyond 2027, it becomes difficult for manufacturers to plan large-scale capital spending on capacity expansion.
Furthermore, there is a structural imbalance in the Indian solar manufacturing sector. While module assembly capacity is high, the domestic production of upstream components like solar cells and wafers remains less developed. This creates a reliance on imports for raw materials, which can expose companies to price volatility and supply chain risks.
Moving forward, the success of this sector expansion will depend on steady consumer adoption, the availability of financing for residential solar projects, and the ability of domestic manufacturers to scale production while managing costs. Investors may monitor government policy announcements, quarterly results of solar equipment manufacturers, and updates on domestic manufacturing capacity utilization to gauge the progress of these industry targets.