

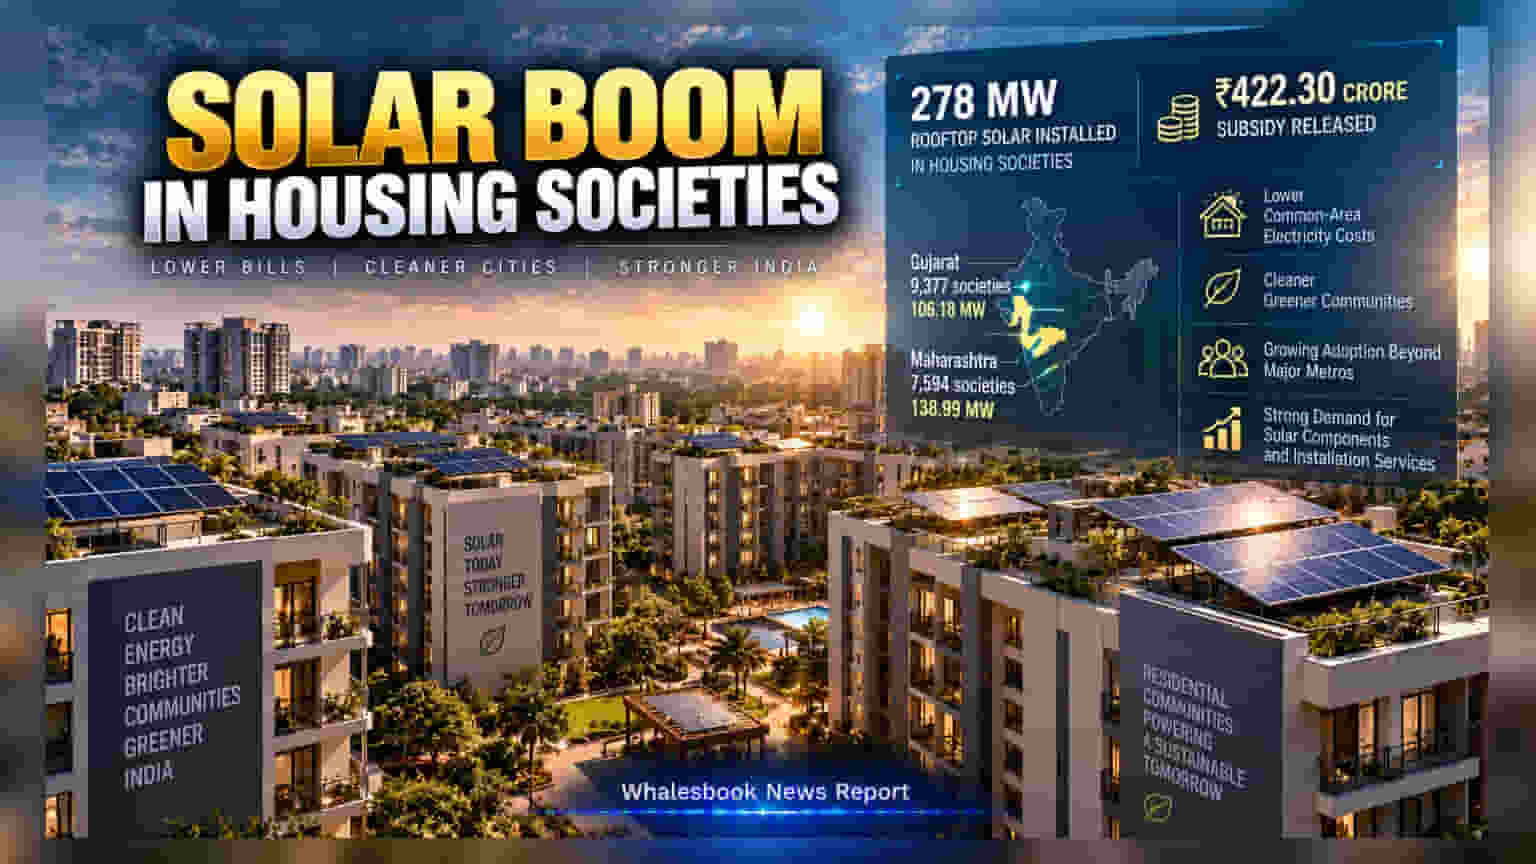
Over 19,000 housing societies have installed 278 megawatts of rooftop solar under the PM Surya Ghar: Muft Bijli Yojana. The government has disbursed ₹422.30 crore in subsidies to reduce maintenance bills for residents. This expansion supports the broader solar equipment supply chain and highlights a shift in urban energy consumption patterns.
Residential group housing societies have reached a milestone by installing approximately 278 megawatts of rooftop solar capacity. This growth, driven by the PM Surya Ghar: Muft Bijli Yojana, is changing how housing complexes manage common-area electricity expenses. The federal government has supported this transition by releasing ₹422.30 crore in subsidies to help housing societies offset the cost of setting up these systems.
Gujarat and Maharashtra currently lead this adoption. Gujarat reports 9,377 participating societies generating 106.18 megawatts, while Maharashtra has 7,594 societies contributing 138.99 megawatts. This regional focus suggests that states with stronger solar policies and efficient state-level implementation agencies are seeing faster adoption rates. The trend is moving beyond major metros, with cities like Nashik, Coimbatore, and Visakhapatnam also showing higher interest as residential management committees look for ways to lower rising energy costs.
Impact on the Solar Ecosystem
The rising installation of rooftop solar is creating a steady pipeline of projects for solar component manufacturers, module suppliers, and installation companies. Increased demand for solar panels, inverters, and mounting structures can influence order books for domestic solar firms. However, investors often watch for execution risks, such as potential delays in subsidy disbursements, documentation hurdles, or variations in state-level net metering policies, which dictate how societies sell excess power back to the grid.
Operational Risks and Monitorables
While the scheme lowers energy bills, there are operational risks that housing societies and investors should monitor. These include the long-term maintenance of solar panels, the quality of installation work by smaller contractors, and the impact of weather conditions on energy generation. Additionally, electricity distribution companies (DISCOMs) often face revenue pressure from rooftop solar, which can sometimes lead to stricter grid connectivity rules or delayed approvals for net metering.
For the industry, the key focus remains on the scalability of these installations. As more societies join, the consistency of technical support and the ability to maintain these systems over a 20-to-25-year lifecycle will be critical. Investors in the renewable energy sector typically look at the sustained order inflows for EPC (Engineering, Procurement, and Construction) companies and the capacity utilization rates of major solar module manufacturers to gauge the long-term health of this residential segment.