

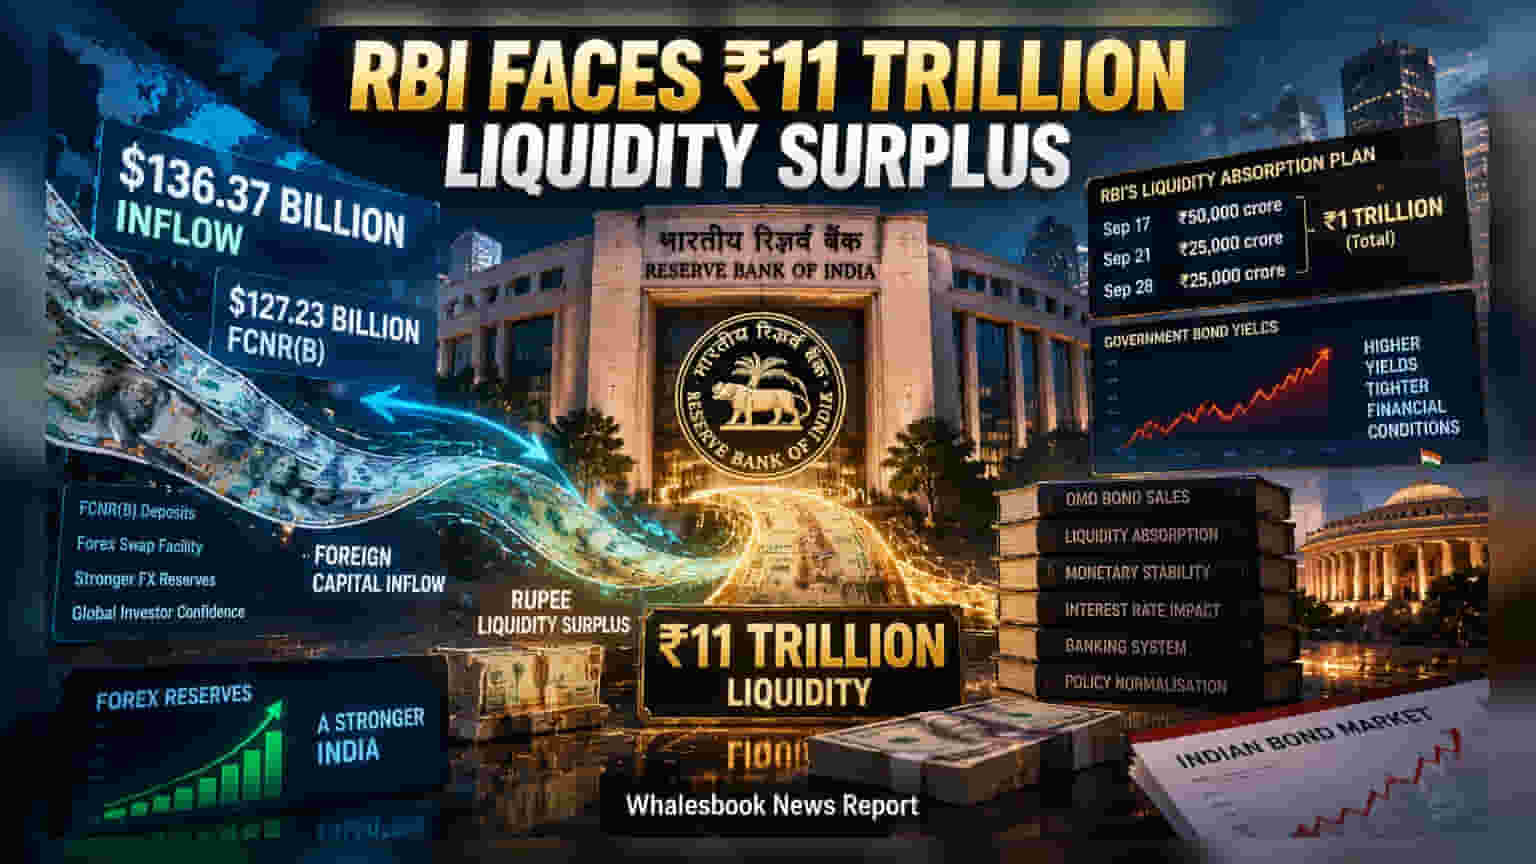
The Reserve Bank of India has begun selling government bonds through Open Market Operations (OMO) to drain excess rupee liquidity. The surplus, which exceeded ₹11 trillion, resulted from a record $136 billion dollar inflow via a special swap facility. This move is expected to influence bond yields and borrowing costs across the economy.
The Reserve Bank of India (RBI) is actively managing a record liquidity surplus that hit a peak of over ₹11 trillion earlier this month. This surplus was triggered by a massive influx of foreign currency, with the banking system receiving $136.37 billion through a special dollar-rupee swap facility that closed on August 31, 2026. The vast majority of this capital, specifically $127.23 billion, entered through Foreign Currency Non-Resident Bank (FCNR(B)) deposits.
While these inflows strengthened India's foreign exchange position, they left the banking system with an excessive amount of rupee cash. To maintain monetary stability and ensure that short-term interest rates stay aligned with its policy goals, the RBI has shifted from temporary liquidity absorption methods to more durable solutions. Starting today, September 17, the central bank has begun selling government bonds through Open Market Operations (OMO).
The RBI plans to drain ₹1 trillion from the banking system in three distinct phases. The first sale takes place on September 17, amounting to ₹50,000 crore. This will be followed by two additional tranches of ₹25,000 crore each, scheduled for September 21 and September 28.
For investors and the broader market, this development is significant because of how it impacts interest rates. When the RBI sells bonds in the open market, it effectively pulls money out of the system. This process usually puts upward pressure on government bond yields, which serve as a benchmark for pricing loans across the economy. Consequently, a period of heavy liquidity absorption may lead to tighter financial conditions for banks and corporations.
Market participants are closely tracking how the bond market absorbs these sales. While the OMO action is intended to stabilize the financial system and control inflation, it also signals a change in the cost of borrowing. Investors should monitor the upcoming tranches to see if bond yields remain stable or if they climb further, as this trend will influence future loan pricing and the overall cost of capital for companies. Future RBI updates will clarify whether further bond sales are needed or if the liquidity will be managed through other tools.