

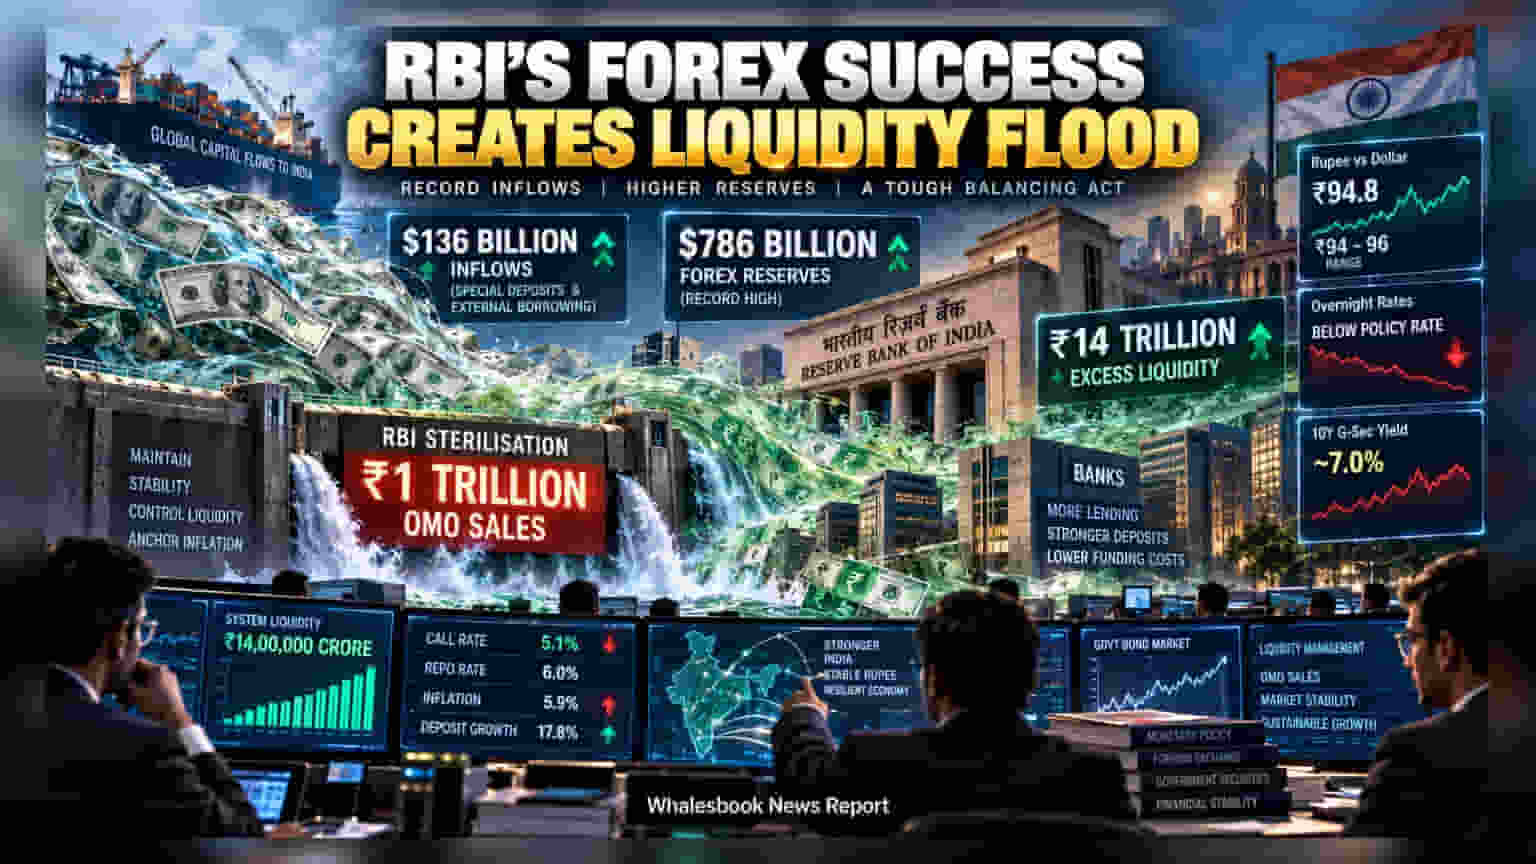
Record foreign inflows of $136 billion have flooded India’s banking system with ₹14 trillion in excess liquidity, forcing the RBI to launch bond sales to drain the surplus. This excess cash is effectively lowering market interest rates, creating a challenge for the central bank as it balances this with rising inflation risks.
India’s recent efforts to boost foreign currency reserves have been highly successful, attracting $136 billion through special deposit windows and external borrowing. This massive influx has pushed India’s foreign exchange reserves to a record $786 billion. While this has helped stabilize the rupee, it has created a new, complex challenge for the Reserve Bank of India: a significant surplus of cash within the banking system.
Currently, the banking system is holding an estimated ₹14 trillion in excess liquidity. When the central bank absorbs these dollars, it releases an equivalent amount of rupees into the economy. This flood of cash has effectively lowered short-term interest rates in the money market, with overnight rates falling below the central bank's policy rates. This acts as a hidden interest rate cut, which is difficult for the central bank to manage given that inflation is currently approaching 6%.
To prevent the economy from overheating, the Reserve Bank of India has initiated a plan to sell government bonds worth ₹1 trillion in September. By selling these bonds, the central bank aims to pull the excess cash out of the banking system. This is a delicate task, as selling too many bonds at once could push government bond yields higher, potentially increasing borrowing costs for the government and businesses.
Banks are currently the biggest beneficiaries of this liquidity. With deposit growth accelerating to 17.8% year-on-year, banks are less dependent on expensive short-term funding from wholesale markets. This environment gives banks more room to expand their lending. However, this creates a secondary risk, as an abundance of cheap cash could encourage aggressive lending practices that may be difficult to control.
For bond market investors, the environment remains tricky. While high liquidity usually helps lower bond yields, other factors are pulling in the opposite direction. High crude oil prices, sticky inflation, and elevated global interest rates are keeping pressure on the 10-year government bond yield, which is currently hovering around 7%. Investors are now watching to see if the central bank can effectively mop up this surplus without causing volatility in the bond markets or disrupting the current bank deposit growth trend. The primary monitorable for the coming months will be how the central bank adjusts its bond-selling operations to balance liquidity without triggering a sharp rise in interest rates.