

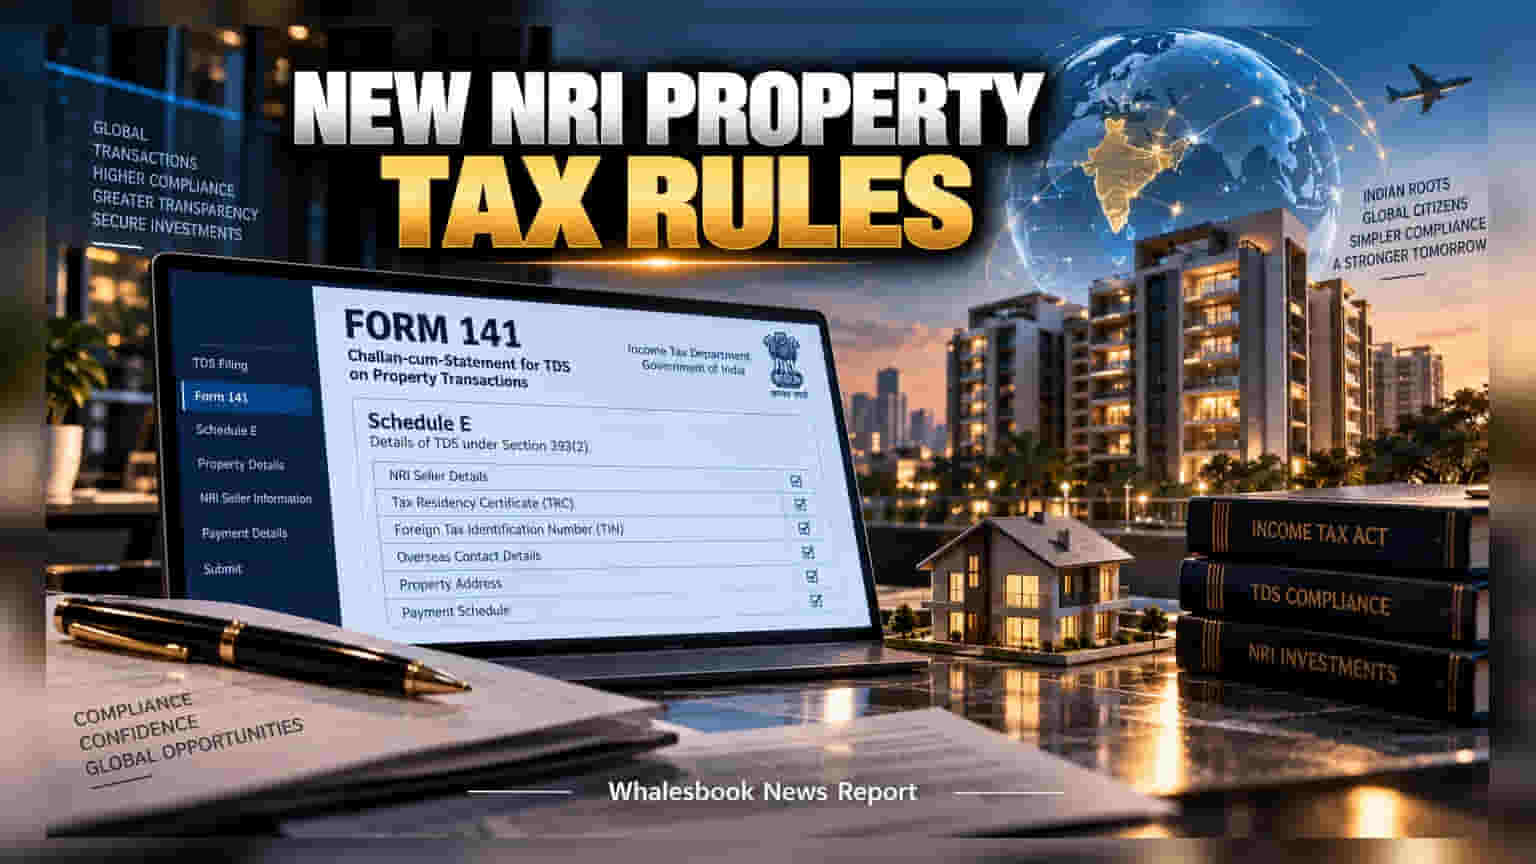
Starting October 1, 2026, residents buying property from NRIs must use an updated Form 141. New rules require detailed disclosures like the seller's foreign tax ID. This change aims to improve transparency but increases the compliance burden on buyers, who are responsible for accurate TDS reporting to avoid potential tax department scrutiny.
The Central Board of Direct Taxes (CBDT) has announced significant updates to the TDS reporting framework for property transactions between resident buyers and non-resident sellers. These changes, which will come into effect on October 1, 2026, aim to create a more centralized and transparent system for tracking such deals.
Under the new guidelines, resident individuals and Hindu Undivided Families (HUFs) will be required to use an updated version of Form 141. This form will act as a unified challan-cum-statement for the transaction. A key part of this update is the introduction of a new Schedule E, which is designed to track tax deductions made under Section 393(2) of the Income-tax Act. This ensures that the tax authorities have a clear trail of the transaction from the moment the sale agreement is executed.
The regulatory update mandates a higher level of transparency regarding the seller's tax status. Buyers must now collect and report specific details from the non-resident seller, including their Tax Residency Certificate (TRC) number, their foreign Tax Identification Number (TIN), and confirmed overseas contact details. Crucially, these disclosure requirements apply even if the seller already possesses a Permanent Account Number (PAN) in India. This requirement is intended to prevent errors in tax withholding that often arise when seller data is incomplete or improperly verified.
For investors and buyers, this change represents a shift toward higher compliance accountability. Beyond simple identity verification, the new Form 141 requires detailed transaction data, such as property address, valuation for stamp duty, and a breakdown of payment schedules, whether paid in a lump sum or installments. In cases involving multiple buyers, each deductor must file a separate form, ensuring that responsibility for accurate TDS filing is clearly assigned to every party involved.
The financial risk for buyers is that the responsibility for accuracy remains entirely with them. Inaccurate reporting or a failure to collect the necessary foreign tax documentation during the initial stages of a deal can lead to notices from the tax department. Since NRI property transactions are high-value and often involve international fund repatriation, incorrect TDS deductions can lead to disputes or delays in finalizing property transfers. Prospective buyers should prioritize collecting these foreign tax documents as a standard part of their due diligence before signing any agreement. The key monitorable for buyers in the coming weeks will be ensuring that their legal and tax consultants are prepared to handle these granular reporting requirements as soon as the system goes live on October 1.