

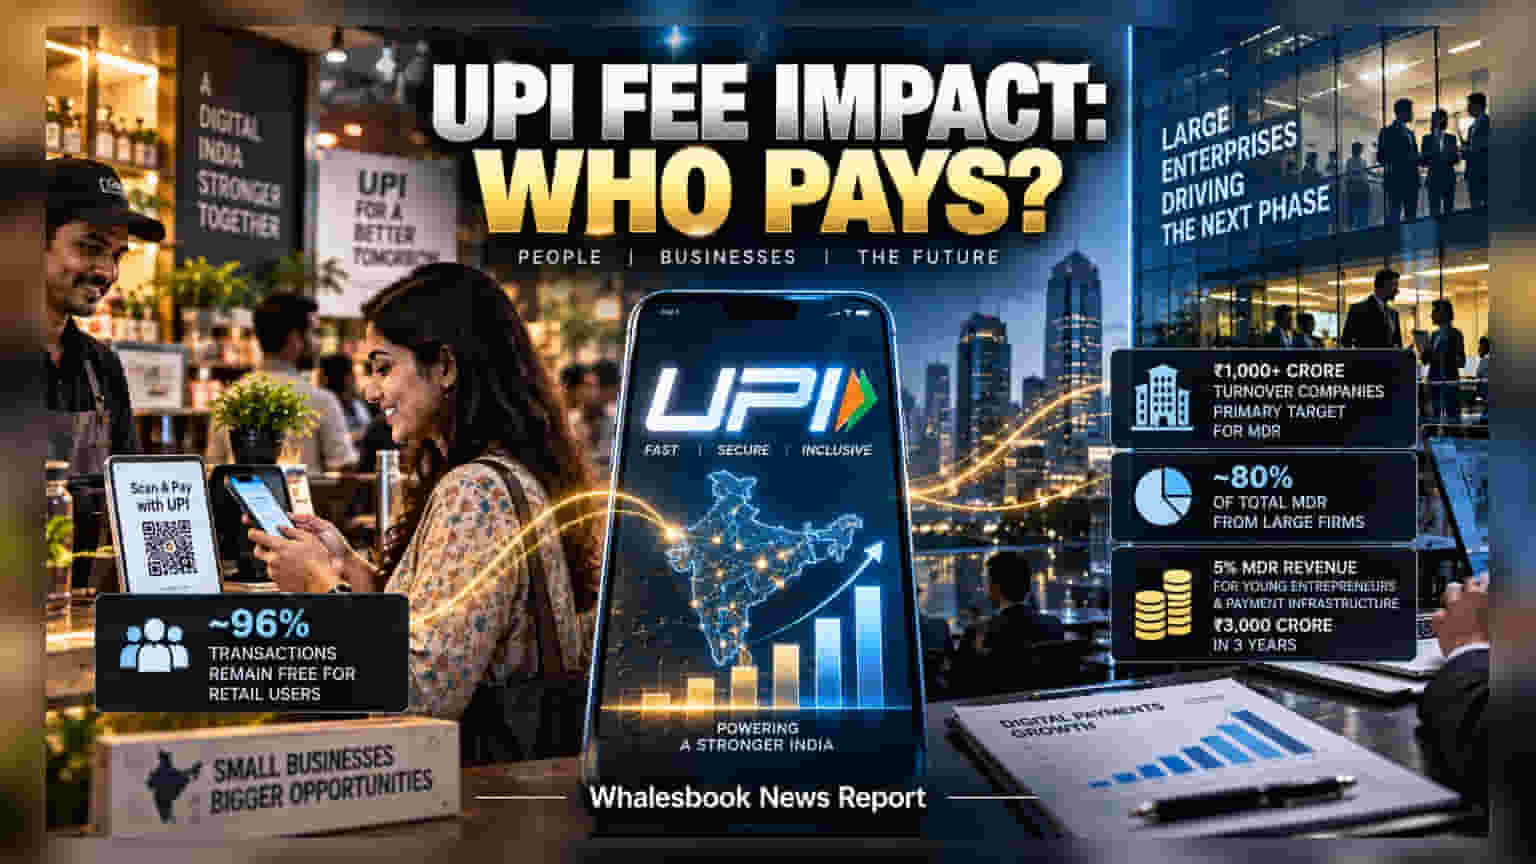
The National Payments Corporation of India (NPCI) has confirmed that the vast majority of retail UPI transactions will remain free. New fee structures are designed for large corporates with annual turnovers above ₹1,000 crore, ensuring that everyday digital payments remain accessible while funding better infrastructure.
The National Payments Corporation of India (NPCI) has addressed concerns regarding the future of UPI transaction fees, confirming that the current free-to-use model for retail customers remains largely unchanged. CEO Dilip Asbe stated that approximately 96% of total UPI transaction volumes and 90% of the total transaction value will continue to be processed without additional costs for standard end-users.
The regulatory framework now focuses on large-scale enterprises with an annual turnover exceeding ₹1,000 crore. These companies, which often maintain complex payment infrastructure and already process high volumes of credit card payments, are the primary target for the revised Merchant Discount Rate (MDR) structure. The NPCI estimates that these large firms will contribute roughly 80% of the total MDR collection. Because these businesses already have systems to handle card processing costs, the expectation is that they will absorb the UPI charges rather than passing them on to retail customers.
Supporting Domestic Networks and Small Merchants
Recent regulatory updates also clarify the role of credit on the UPI network. As of September 15, 2026, the NPCI mandates that credit-based transactions on UPI must be processed exclusively through RuPay cards. This is a strategic move to promote the domestic payment ecosystem and improve competition for Indian platforms against international networks.
Furthermore, the NPCI has outlined a plan to reinvest a portion of these new collections. The organization intends to allocate 5% of all MDR revenue into a dedicated support fund for young entrepreneurs and the development of payment infrastructure. This initiative aims to accumulate ₹3,000 crore over the next three years. The goal is to provide better payment access for small merchants across the country, effectively using fees from large entities to improve the network for smaller players.
Investor and Market Perspective
For investors in the financial and digital payment sector, this clarification resolves uncertainty regarding the sustainability of UPI’s business model. By keeping the system free for the average consumer, the NPCI maintains the high adoption rates that have fueled India’s digital payments growth. The focus on large corporate entities ensures that banks and payment service providers can collect fees where they are most likely to be paid, potentially improving the revenue dynamics for the payment ecosystem.
However, the ultimate impact will depend on how large retailers adjust their pricing models and whether they accept the new fees. Investors should monitor the implementation of these rules, the growth of the support fund, and any changes in the adoption of credit-on-UPI via RuPay, as these will be key indicators of the health and sustainability of the digital payment infrastructure in the coming quarters.