

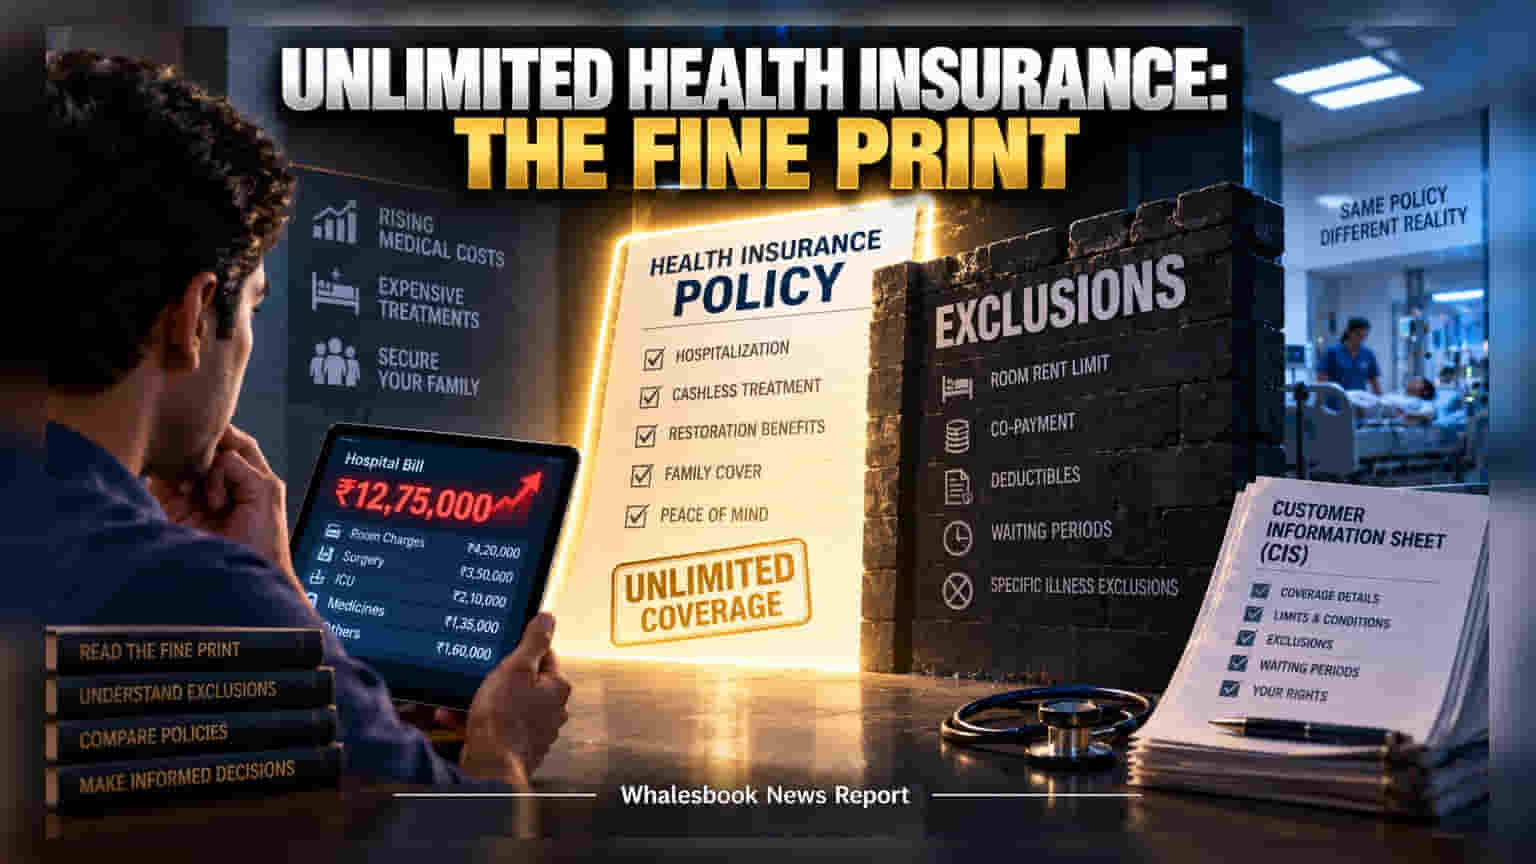
Insurance plans marketed as 'unlimited' often carry hidden conditions that limit actual coverage. Policyholders remain subject to sub-limits, co-payments, and waiting periods regardless of the headline sum insured. Before purchasing, reviewing the Customer Information Sheet is essential to understand potential out-of-pocket expenses and actual policy protection.
The promise of 'unlimited' health insurance is a common marketing pitch designed to reassure families worried about the rising costs of medical care. Insurers often highlight these plans to appeal to those seeking a safety net that covers all potential hospital bills. However, for the policyholder, the term 'unlimited' rarely means a blank cheque for every medical expense. In practice, the total sum insured is subject to specific contractual boundaries that can significantly reduce the actual payout during a claim.
Why 'Unlimited' Doesn't Mean 'All-Inclusive'
When a policy is branded as having unlimited coverage, it generally refers to the aggregate sum insured—often through restoration benefits where the cover refills after being exhausted. Despite this, every claim is governed by strict policy conditions. Even with a high coverage amount, insurers impose sub-limits on various components of medical bills. A common example is the room rent cap. If a policy limits room rent to a certain amount per day, but the patient chooses a more expensive room, the insurer may only pay a portion of the total hospital bill, leaving the policyholder responsible for the price difference. This discrepancy often surprises consumers who assume their entire bill will be covered by the insurer.
Hidden Financial Barriers
Beyond sub-limits, several other mechanisms shift financial responsibility back to the patient. Co-payment clauses require the policyholder to share a percentage of the admissible claim, meaning the insurer does not pay the full amount of even valid medical expenses. Similarly, mandatory deductibles require the patient to pay a fixed portion of the bill out-of-pocket before the insurance coverage officially kicks in. These features are standard risk-management tools for insurers, but they directly increase the financial burden on the family during a medical crisis. Furthermore, waiting periods—which can be as long as 36 months for pre-existing conditions—mean that certain health issues remain excluded from coverage for a significant duration, regardless of the 'unlimited' label on the policy.
The Importance of the Customer Information Sheet
To navigate these complexities, the Insurance Regulatory and Development Authority of India (IRDAI) mandates that insurers provide a Customer Information Sheet (CIS) with every policy. This document is designed to summarize the key features, exclusions, and conditions in a standardized, easy-to-understand format. For any buyer, the CIS is more reliable than marketing brochures or verbal promises from agents. It explicitly outlines what the policy covers and, more importantly, where the insurer’s liability ends. Before committing to any premium, a thorough review of this document is the most effective way to avoid unexpected expenses during an emergency.