

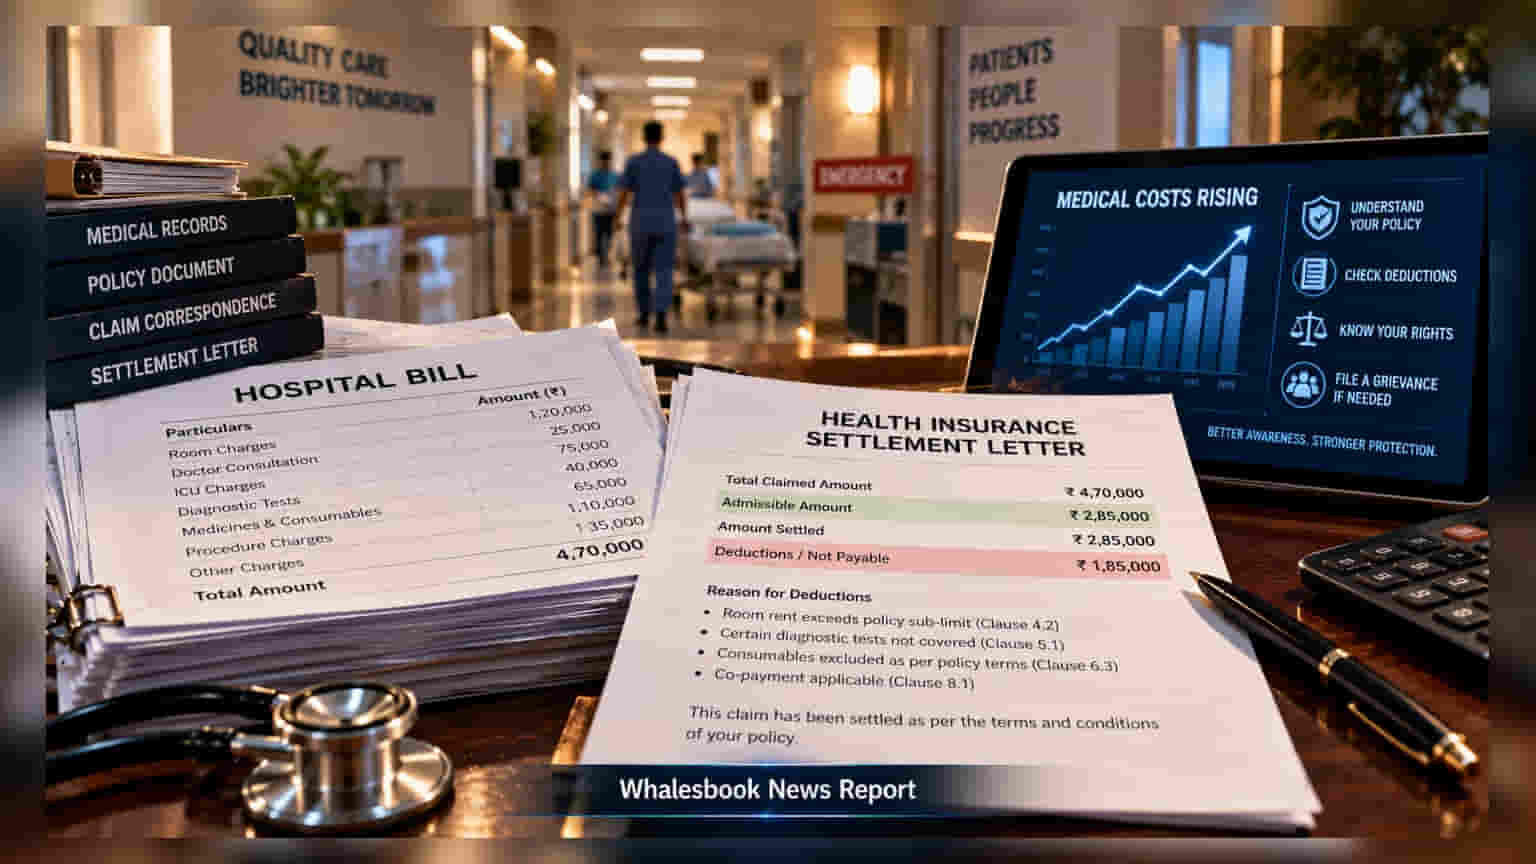
A lower-than-expected insurance payout often stems from policy sub-limits and coverage caps. Understanding your settlement letter is the first step to verifying deductions. Learn how to identify these gaps and follow the formal grievance process, including IRDAI timelines, if you disagree with the insurer’s final decision.
The gap between a total hospital bill and an insurance settlement is a common issue for many policyholders. When the final payout is lower than expected, the settlement letter becomes the most important document to analyze. It breaks down the total claimed amount into what the insurer has approved and what has been excluded based on your policy terms.
The most critical figure in the letter is the admissible amount. This represents the portion of the medical bill that the insurer covers after applying conditions such as sub-limits on room rent, co-payment clauses, or specific coverage caps defined in your contract. Comparing the line items in your hospital invoice against the deductions listed in the letter is necessary to confirm if the insurer has applied the policy terms correctly.
Insurers are legally required to provide a clear, written explanation for any deduction or claim rejection. If a claim is partially settled, the letter must cite the specific clause from your policy document that justifies the decision. Verbal explanations provided by hospital staff or third-party administrators do not hold weight in formal disputes, so always insist on written clarity from the insurance company.
Regulatory standards set by the Insurance Regulatory and Development Authority of India (IRDAI) mandate that insurers must settle or reject a claim within 30 days of receiving all necessary documentation. This timeline can extend to 45 days if the claim undergoes a formal investigation. If an insurer delays beyond these periods or if you believe the decision is unfair, you must initiate a formal written complaint with the insurer’s designated Grievance Redressal Officer.
If the insurer fails to provide a satisfactory resolution within 15 days of your complaint, you can escalate the issue through the Bima Bharosa system. This is the official platform for insurance consumers in India to register and track complaints. Maintaining a documented, evidence-based trail—including your disputed settlement letter, medical records, and clear citations of the policy clauses you are contesting—is essential for any regulatory review process.