

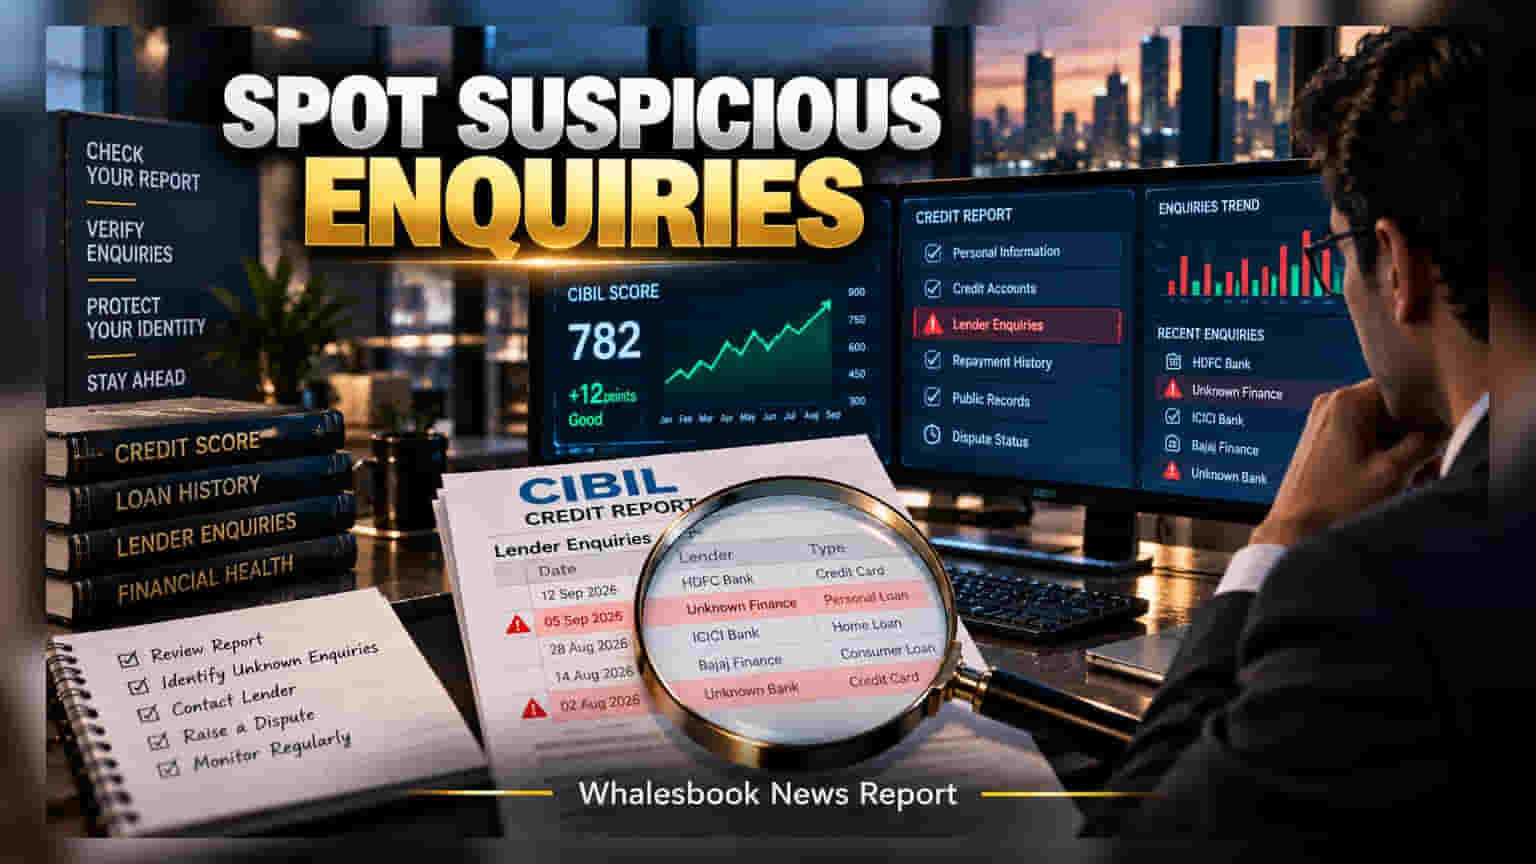
Regularly checking your TransUnion CIBIL credit report helps protect against identity theft and loan errors. Learn how to verify lender entries, understand why partner bank names appear, and follow the simple dispute process to keep your credit history accurate.
Many consumers view their CIBIL score simply as a number, but the real value lies in the detailed credit report behind it. This document acts as an early warning system for your financial health. By monitoring your repayment history, active loans, and lender enquiries, you can identify administrative errors or signs of identity theft before they lead to a loan rejection or higher interest rates on future borrowings.
Understanding Lender Enquiries
When a bank or financial institution accesses your credit file to review an application, it records a lender enquiry. Seeing these entries is normal if you have recently applied for a credit card or a personal loan. However, you might occasionally spot a bank name you do not recognize. Before assuming this is fraud, consider the nature of digital lending. Many buy-now-pay-later platforms and online loan marketplaces work through partner banks. The name on your credit report may be the underlying bank, not the digital brand you interacted with. Always cross-reference these enquiries with your recent financial activity.
Taking Action on Suspicious Entries
If you find an enquiry that cannot be explained, you must act immediately. Your first step should be to contact the listed bank or financial institution directly. Ask them about the nature of the credit search and confirm whether your credentials were used for an unauthorized application. If the institution confirms they did not interact with you, ask for written proof or an acknowledgement of the error.
Once you have verified that the entry is incorrect, initiate a formal dispute with TransUnion CIBIL. CIBIL functions as a facilitator that collects and reports data provided by banks; it cannot change information on its own. The bureau will verify your claim with the reporting bank, which generally takes about 30 days. If the entry is part of a larger issue, such as a loan account you never opened, you must document all evidence and correspondence to support your dispute. Consistent monitoring remains the most effective way to ensure your credit history reflects your true financial activity.