

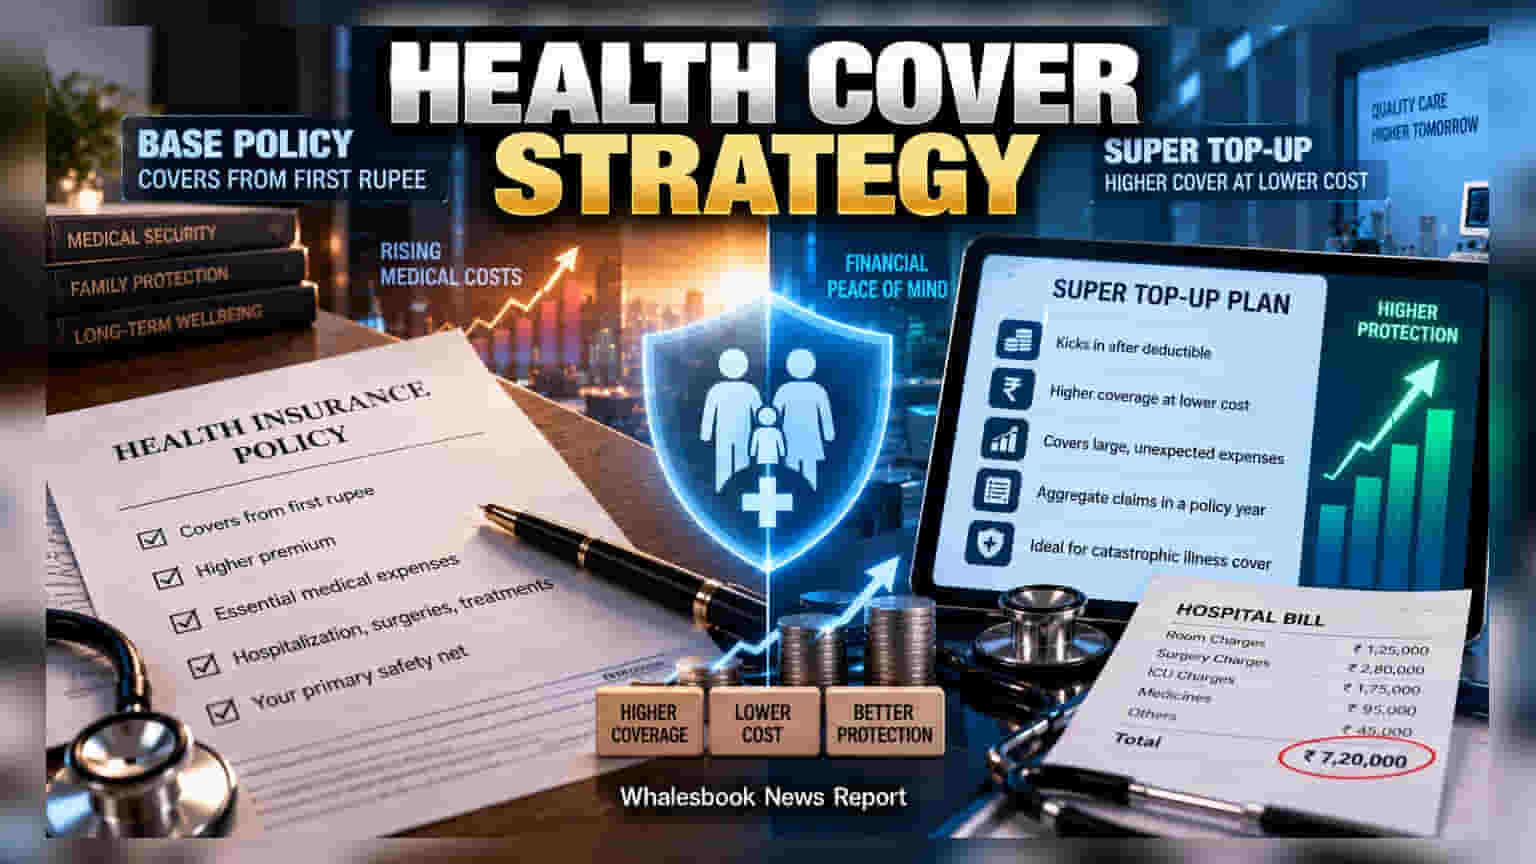
Policyholders must choose between increasing a base health insurance policy or adding a super top-up plan to manage medical costs. While base plans cover expenses from the first rupee, super top-ups offer high limits at lower premiums but require meeting a deductible threshold. Individuals should evaluate their existing base cover and available cash to avoid coverage gaps during a medical emergency.
Rising medical costs are pushing many individuals to reassess their health insurance coverage. When aiming for higher protection, policyholders typically face a decision: should they opt for a larger base policy or keep a modest base plan and add a super top-up cover? Understanding the mechanics of both is necessary to manage both medical risk and personal finances effectively.
The Role of Base Policies
A base health insurance policy acts as the primary safety net. It covers medical expenses from the very first rupee of an admissible claim. Because insurers are liable from the start, these policies tend to have higher premiums as the sum insured increases. For example, moving from a ₹5 lakh policy to a ₹20 lakh policy can lead to a sharp rise in annual premiums. This is where many individuals look for alternatives like super top-up plans to keep costs manageable.
How Super Top-Up Plans Work
A super top-up plan is designed to provide high-value coverage at a much lower cost compared to a traditional base policy. However, these plans come with a condition known as a 'deductible.' This is the amount the policyholder must pay or bear through their base insurance policy before the super top-up kicks in.
For instance, if you have a ₹5 lakh base policy and a ₹20 lakh super top-up with a ₹5 lakh deductible, the super top-up will only pay for expenses exceeding the first ₹5 lakh. Unlike standard top-up plans that apply a deductible to every single claim, super top-up plans usually aggregate all medical bills within a policy year. This means if you have multiple hospitalizations that collectively cross the deductible threshold, the super top-up plan will start paying the excess.
Risks and Financial Gaps
The primary risk in relying heavily on a super top-up plan is liquidity. If a medical event occurs and the base policy is not enough to cover the deductible, or if the base policy has exclusions like co-payments or sub-limits that aren't counted toward the deductible, the policyholder may have to pay the difference from their own pocket.
Furthermore, base policies and super top-up plans are often separate contracts. This can lead to complications if the terms differ. For example, one plan might include certain day-care procedures while the other excludes them, or they might have different lists of network hospitals. If a claim is rejected by the base insurer for a reason that the super top-up insurer also follows, the policyholder could find themselves without coverage when they need it most.
Evaluating Your Strategy
A balanced approach often involves maintaining a base policy large enough to handle standard, frequent medical needs, while using a super top-up as a cost-effective shield against catastrophic illness. Before selecting a plan, it is essential to check if the deductible on the super top-up aligns perfectly with the sum insured of the base plan. Reviewing the list of exclusions, waiting periods, and network hospital availability for both contracts is necessary to ensure there are no surprises during a claim. The goal is to avoid any situation where an unexpected expense falls into a coverage gap.