

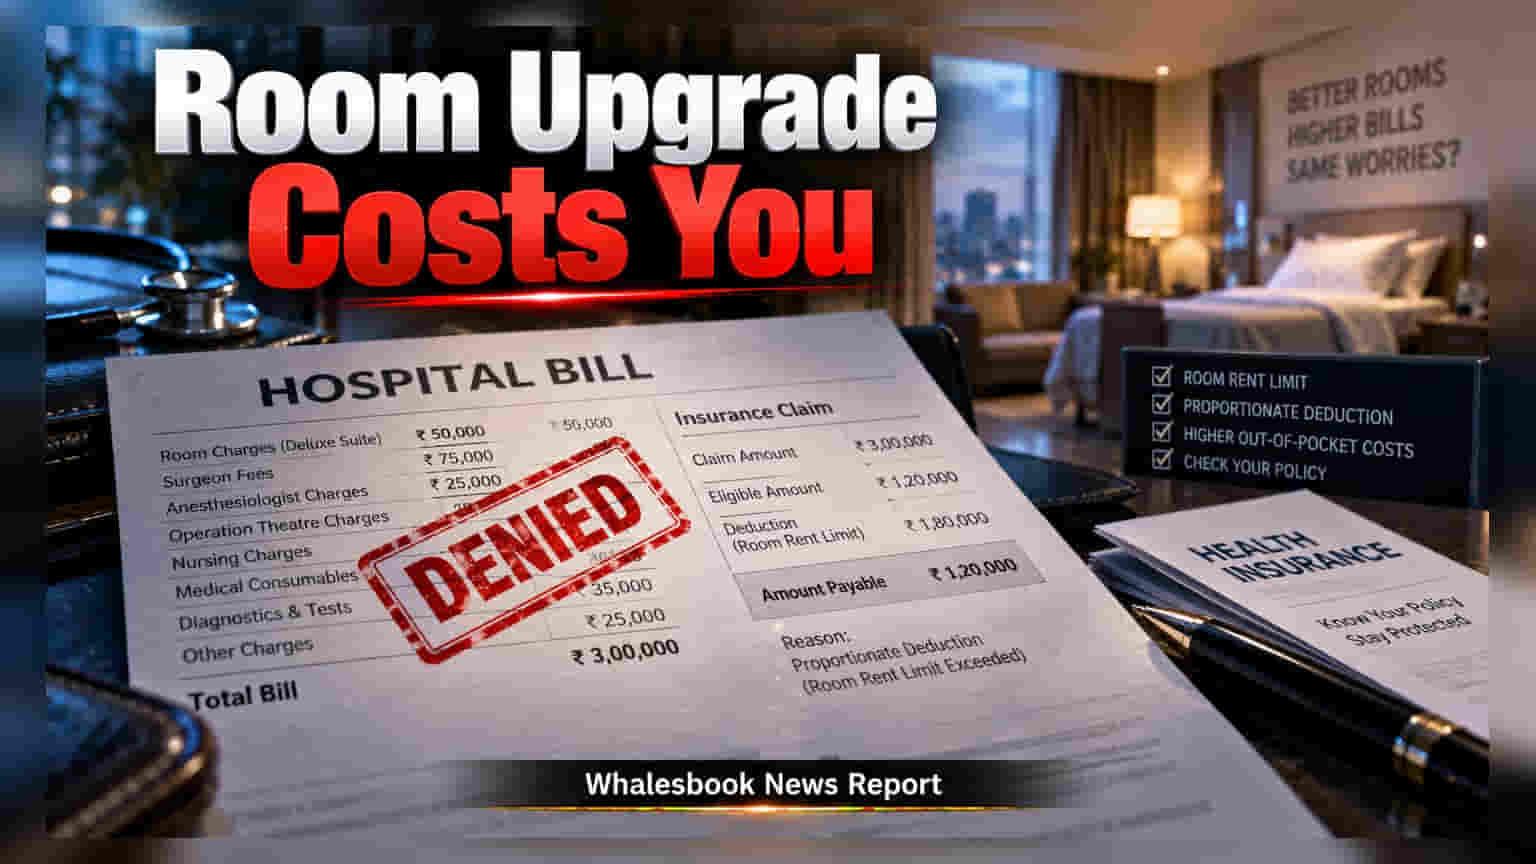
Upgrading your hospital room often triggers proportionate deductions in health insurance claims. This clause can slash your entire payout, including surgery and doctor fees, not just the room rent. Checking your policy for room rent limits before admission can help you avoid unexpected out-of-pocket costs.
When you are admitted to a hospital, your choice of room can significantly impact your insurance claim. Many policyholders believe that if they have a large insurance cover, all their hospital bills will be paid. However, if your policy includes a 'room rent limit,' opting for a premium room can lead to a 'proportionate deduction.' This is a hidden rule that reduces the payout for your entire hospital bill, not just the extra cost of the room.
How Proportionate Deduction Works
Insurance policies often link various hospital charges to the room category. Expenses such as surgeon fees, anesthesiologist charges, nursing costs, and operation theatre usage are frequently classified as 'room-linked.' If your policy limits room rent to, for example, 5,000 rupees per day, and you choose a 10,000 rupee suite, the insurer does not just deduct the difference in the room price. Instead, it applies a proportionate reduction to the entire claim amount. If you exceed the room rent limit, the insurer may only pay a percentage of the total bill, which is calculated based on the ratio of your entitled room rent to the actual room rent charged.
Why This Impacts Your Wallet
Because surgeon and professional fees are often tied to the room category in the hospital’s billing system, a small upgrade to your room can lead to a large reduction in your total claim payout. This can result in significant out-of-pocket expenses for the patient. For instance, a claim of 3 lakh rupees could be reduced by a substantial amount simply because the patient chose a room category that exceeded the policy’s predefined limit.
How to Protect Your Coverage
Before you get admitted to a hospital, it is essential to check your policy document for terms like 'room rent limit,' 'room rent capping,' or 'proportionate deduction.' For planned procedures, you should coordinate with the hospital’s billing department and your insurance provider to understand which rooms fall within your policy’s limit. Patients should also specifically ask about ICU charges, as these are often treated differently from standard room rents. Some modern or premium health insurance plans offer 'no room rent limit' or 'no sub-limit' features, which prevent these deductions. While these plans typically come with higher premiums, they provide greater protection against unexpected claim reductions. Comparing the cost of these plans against the potential financial risk of out-of-pocket payments is a critical part of planning your health insurance.