

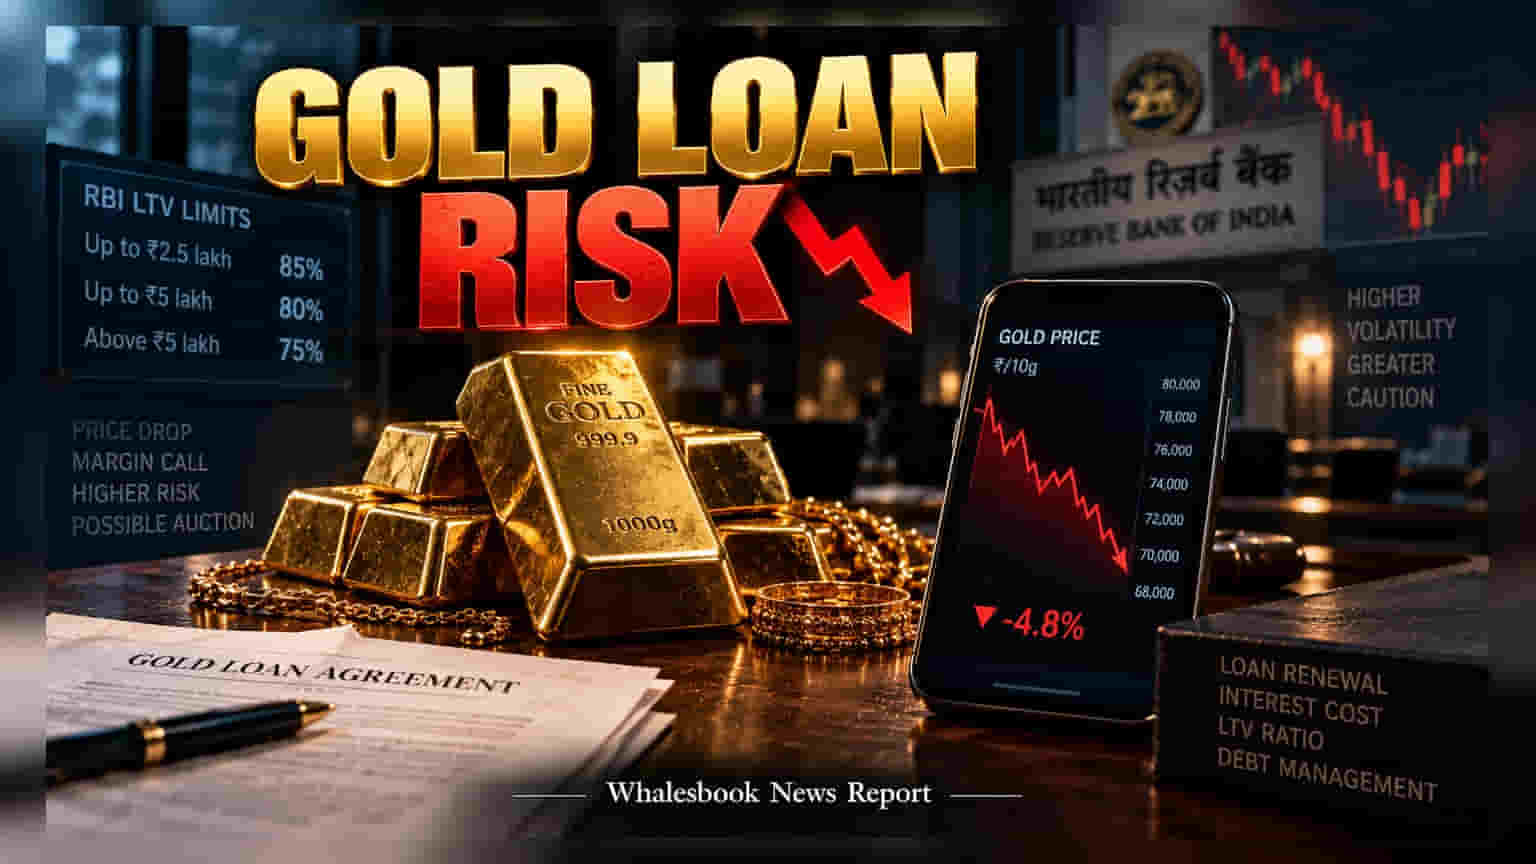
Falling gold prices can cause your loan-to-value (LTV) ratio to exceed RBI limits, triggering margin calls from lenders. Borrowers should assess their current collateral value before opting for loan renewals to avoid the risk of asset liquidation.
Gold loans are a common method for Indian households to access quick liquidity, but they involve a financial risk that is often overlooked: the volatility of gold prices. Because the loan is backed by physical gold, any decline in market prices directly reduces the value of the collateral. This can lead to a scenario where the loan amount exceeds the regulatory limits set by the Reserve Bank of India (RBI).
Understanding RBI Loan-to-Value Limits
The RBI has set specific loan-to-value (LTV) caps to ensure that lenders remain protected against market fluctuations. These rules restrict how much a lender can sanction against the value of the pledged jewellery. For loans up to ₹2.5 lakh, the LTV limit is 85 percent. For loans up to ₹5 lakh, the cap is 80 percent, and for loans exceeding ₹5 lakh, the limit is 75 percent. If the market value of the gold falls, these percentages can shift quickly, potentially breaching the regulatory ceiling.
The Risk of Margin Calls During Price Drops
When a borrower applies for a loan renewal, the lender must re-evaluate the collateral. Most institutions calculate the value based on the lower of the preceding 30-day average closing price or the previous day’s closing price. If the market price of gold has dropped significantly, the existing loan balance may suddenly represent a higher percentage of the collateral's value than allowed. When this happens, lenders may issue a margin call. This requires the borrower to either pay down a portion of the loan principal or provide additional gold jewellery to restore the required LTV ratio. Failure to meet this requirement can lead the lender to initiate an auction of the pledged assets to recover the dues, even if the borrower has been consistent with interest payments.
Strategic Debt Management
Borrowers often choose to renew loans to avoid the pressure of repaying the entire principal amount immediately. However, carrying debt forward through multiple renewals during a period of declining gold prices can lead to a cycle of rising interest costs. This makes it increasingly difficult to settle the loan in the future. Instead of simply extending the tenure, it is practical for borrowers to compare their outstanding balance with the current market valuation of their pledged gold.
If the value of the asset is trending downward, focusing on reducing the principal amount is often a more sustainable approach than extending the loan. Borrowers should contact their lender to obtain a detailed breakdown of the new interest rates, processing fees, and the updated tenure. Monitoring gold price trends and understanding these valuation mechanics is essential for maintaining control over pledged assets and avoiding the risk of liquidation.