

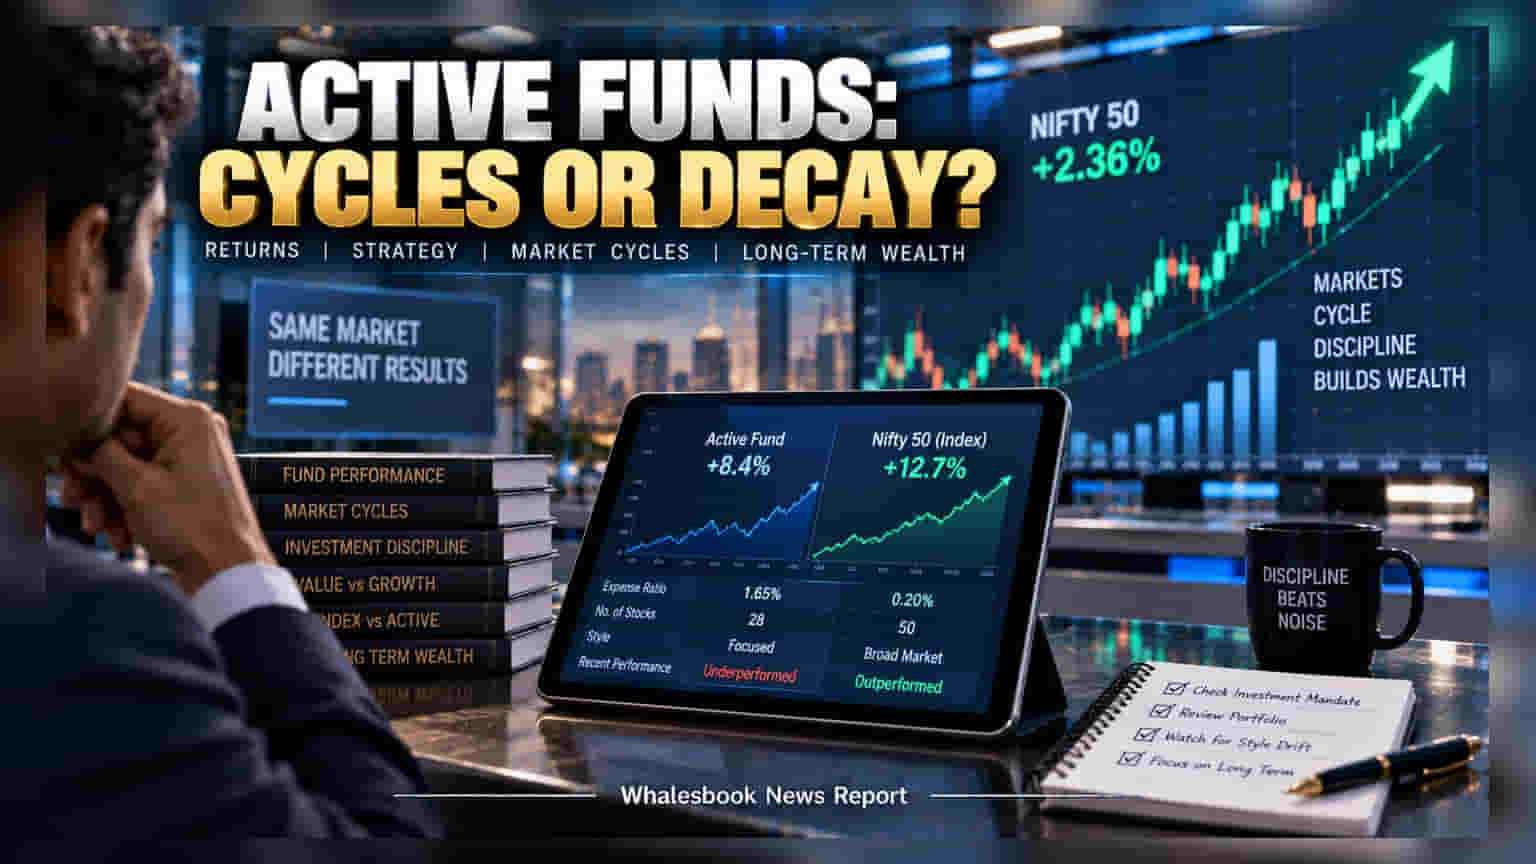
Many active mutual funds have struggled to beat market indices during the recent broad rally. Because passive funds track every stock in an index, they capture gains across the board, whereas active funds, which hold fewer stocks, may miss out. Investors should look for long-term consistency in a manager's strategy rather than reacting to short-term underperformance.
A growing number of Indian investors are noticing that their active mutual funds are failing to beat simple index benchmarks like the Nifty 50 or the BSE Sensex. This trend often becomes most visible when the stock market experiences a broad-based rally. When almost every sector and stock size—from large to small caps—is rising simultaneously, passive funds, which own almost everything in the index, naturally capture all that growth. In contrast, active fund managers operate with concentrated portfolios, typically holding fewer than 40 stocks. This approach is designed to beat the market by being selective, but it can backfire when the market rally is so widespread that even underperforming stocks contribute to the index gains.
Another significant factor for investors to consider is the cost of management. Active funds carry higher expense ratios because they require teams of analysts and fund managers to pick stocks. For an active fund to deliver value, it must beat the benchmark index by a margin larger than its extra fees. If a fund performs in line with the index, the investor actually earns less than they would have in a low-cost passive index fund after accounting for these management fees. This makes the hurdle for active managers significantly higher during periods where markets are efficiently rising.
Industry experts suggest that investors must distinguish between temporary cycle-based underperformance and a fundamental breakdown in a manager’s process. Every fund manager follows a specific style, such as value investing, growth focus, or quality-based stock picking. These styles rotate in and out of favor. A manager who focuses on undervalued, overlooked stocks may struggle during a bull market where high-growth, expensive stocks are leading the charge. If the manager sticks to their original strategy, this underperformance is likely just a reflection of the current market cycle rather than poor decision-making.
The real risk for investors appears when a manager begins to show signs of style drift. This happens when a manager, feeling pressure from underperformance, abandons their stated philosophy to chase whatever stocks are currently rising. This shift can be dangerous because it destroys the original investment thesis that the investor signed up for. A transparent manager who explains why their portfolio is lagging due to a specific market cycle is generally viewed as more trustworthy than one who changes their investment approach overnight to fix short-term returns.
Going forward, investors may want to evaluate their mutual funds not just by recent returns, but by looking at portfolio disclosures to ensure the manager is still following the stated investment mandate. Monitoring whether a fund’s performance aligns with its stated style during different market phases can help in deciding whether to stay invested or reconsider the allocation. The focus for long-term investors should remain on whether the underlying methodology is consistent and repeatable, rather than on short-term gaps against index benchmarks.