

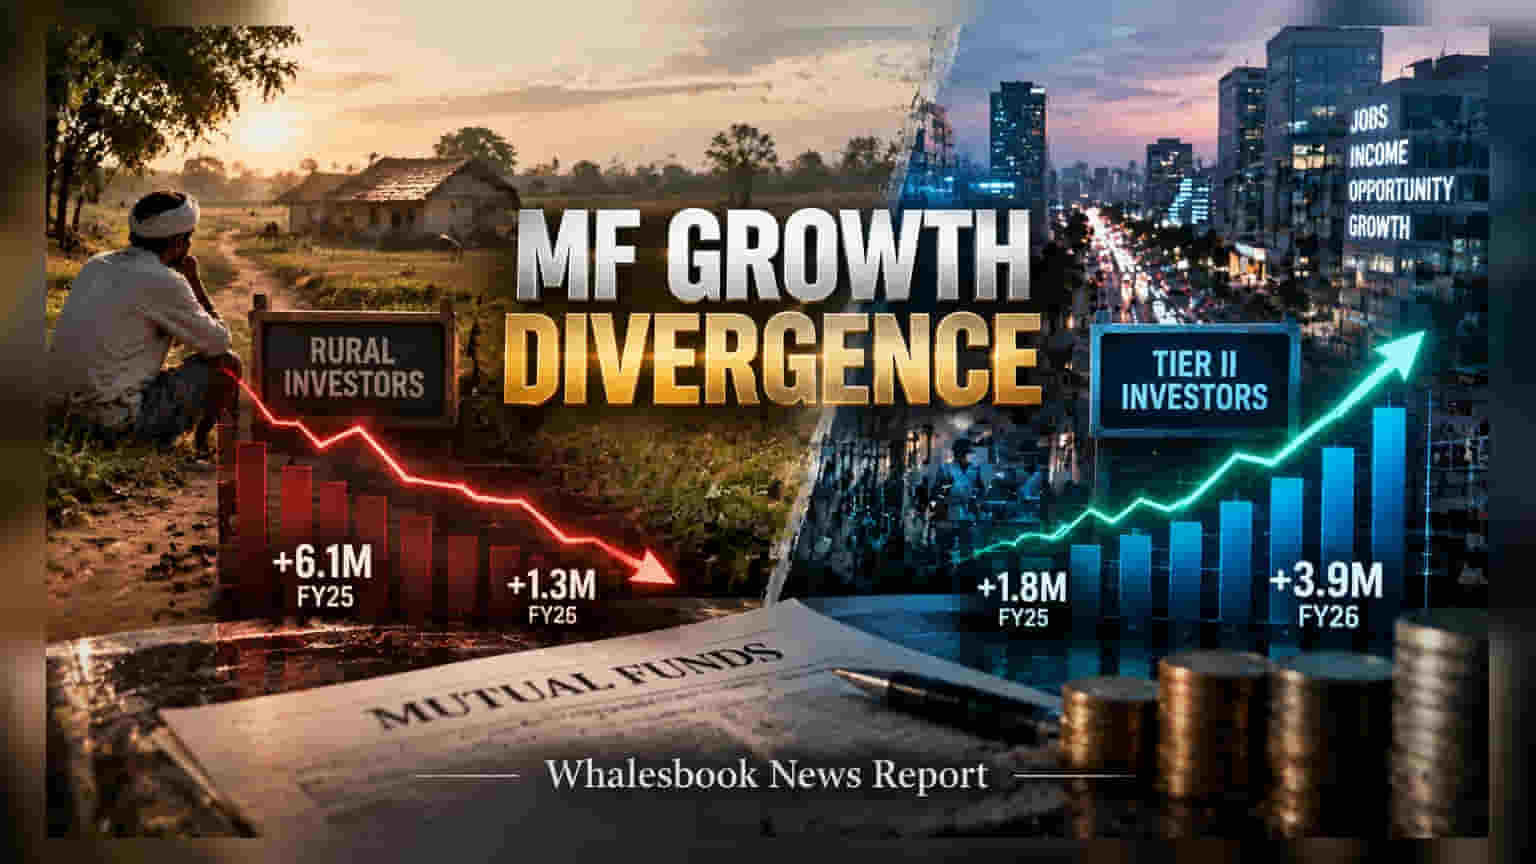
In fiscal year 2026, new mutual fund investor additions in rural India fell to 1.3 million from 6.1 million a year earlier, as market volatility impacted rural sentiment. Meanwhile, Tier II cities saw a strong surge, adding 3.9 million new investors. This divergence reflects a trend where more stable urban regions are becoming the primary driver for asset management firms, while smaller markets struggle with retention during market corrections.
The growth narrative for India's mutual fund industry experienced a sharp split during the 2026 fiscal year. While the sector has been expanding rapidly over the past few years, data released by the Securities and Exchange Board of India shows that the momentum in rural and semi-urban markets, classified as Tier III, significantly cooled. After a strong expansion in fiscal year 2025, where these regions added 6.1 million new investors, the count for fiscal year 2026 fell to just 1.3 million. By the end of March 2026, the total base of unique investors in these rural locations stood at 33.9 million, reflecting a modest growth of 3.8 percent.
The Rise of Tier II Investors
While Tier III markets faced a slowdown, Tier II cities—which include 104 large urban centers—became the new primary growth engine for the mutual fund industry. These cities added 3.9 million new investors in fiscal year 2026, more than double the 1.8 million added in the previous year. Industry analysis points to several factors behind this divergence. Tier II regions benefit from stronger job creation, more stable salary structures, and increased corporate activity, which provide a foundation for consistent long-term investing.
Investors in these urban centers appear better equipped to maintain their Systematic Investment Plans (SIPs) even when market conditions fluctuate. In contrast, the smaller, more volatile investment sizes typically seen in Tier III markets seem to have been more sensitive to the recent market corrections. Many rural investors entered the market during a phase of high performance, and the subsequent downturn tested their conviction. Without consistent professional guidance or a deeper understanding of market cycles, many of these newer participants may have opted for premature exits rather than continuing their investments.
Challenges in Rural Penetration
The decline in new rural investor additions highlights the limits of momentum-driven growth. When markets are rising, new investors are often attracted by high returns, but they may lack the coaching needed to navigate a correction. This vulnerability to short-term volatility suggests that the current penetration strategy in rural areas may need to evolve from simple acquisition to long-term investor education. For mutual fund companies, the challenge lies in balancing the drive for volume with the need to build a resilient investor base that stays invested through market ups and downs. As the industry moves forward, the ability to provide consistent advisory support in smaller regions will likely determine whether this slowdown is a temporary setback or a structural hurdle for rural financial inclusion.