

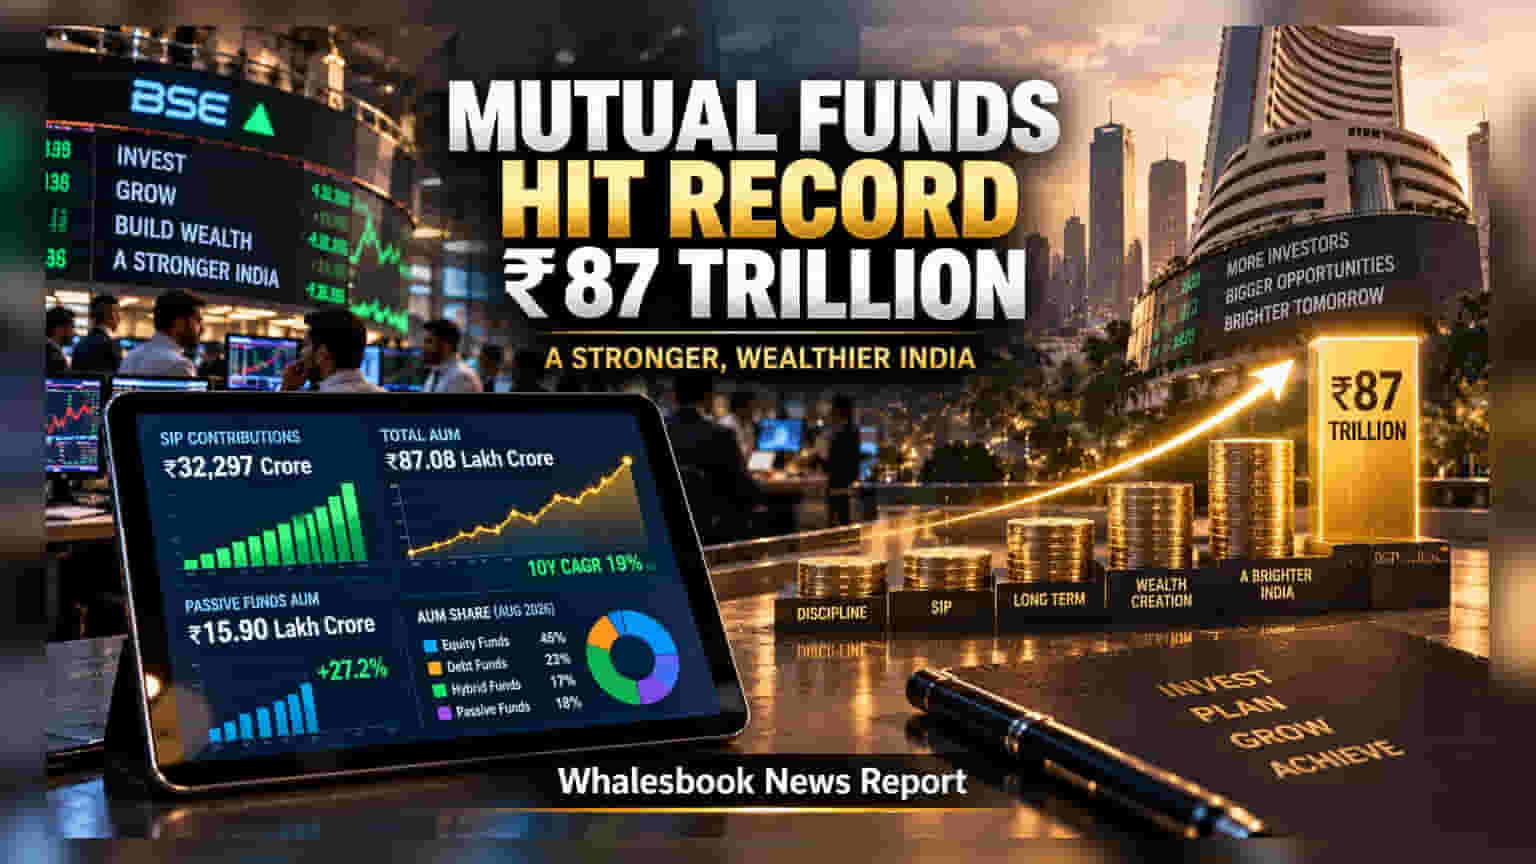
India's mutual fund industry reached an all-time high of Rs 87.08 lakh crore in assets under management in August 2026. This growth was driven by record SIP inflows of Rs 32,297 crore. While retail participation is rising, investors are shifting preference from large-cap funds toward mid- and small-cap segments, a trend that warrants attention due to potential volatility and regulatory oversight on liquidity management.
In August 2026, the Indian mutual fund industry reached a record high of Rs 87.08 lakh crore in total Assets Under Management (AUM). This milestone reflects the continued rise of domestic financial savings in equities and passive investments. Over the last decade, the industry has seen a 19% compound annual growth rate, signaling a structural change in how Indian households manage their wealth.
Systematic Investment Plans (SIPs) continue to drive this expansion. In August, SIP contributions reached a record Rs 32,297 crore, with an average ticket size per account of Rs 3,003. This indicates that retail investors are increasingly committing to long-term wealth creation, a trend further supported by data showing that 32% of SIP assets are now held for over five years.
The composition of these investments shows a clear shift in risk appetite. Equity funds held Rs 39.25 lakh crore in AUM, but the internal distribution shows investors are favoring smaller firms. Mid-cap and small-cap funds attracted net inflows of Rs 6,989 crore and Rs 7,973 crore, respectively. In contrast, large-cap funds saw net outflows of Rs 1,147 crore. This trend suggests that retail investors are currently looking for growth in higher-beta segments, which can be more volatile than stable, large-company stocks.
As capital pours into these segments, the regulatory environment remains focused on risk management. The Securities and Exchange Board of India (SEBI) has been emphasizing the need for robust liquidity management and stress testing in small-cap and mid-cap funds. These measures aim to ensure that fund managers can handle sudden redemption pressures without significantly impacting stock prices. Investors may note that higher inflows into these specific segments often necessitate careful portfolio monitoring by fund houses.
Passive funds, including index trackers, are also gaining significant traction, growing 27.2% to Rs 15.90 lakh crore. This trend reflects the rising popularity of low-cost strategies that track market indices, allowing investors to match market performance rather than relying on active fund management.
The reach of mutual funds is also expanding geographically. B30 cities—regions outside the top 30 financial centers—now account for 19% of the total industry AUM. With a 24% five-year compound annual growth rate, these regions are outpacing T30 cities in growth. This suggests that digital distribution and increased financial awareness are successfully penetrating smaller towns, reducing the industry’s reliance on major urban hubs.
Moving forward, the performance of these funds will depend on broader economic factors, including corporate earnings, interest rate trends, and global market stability. For investors, the focus remains on understanding the risks associated with the high allocation to mid- and small-cap segments and how these funds perform during periods of market volatility.