

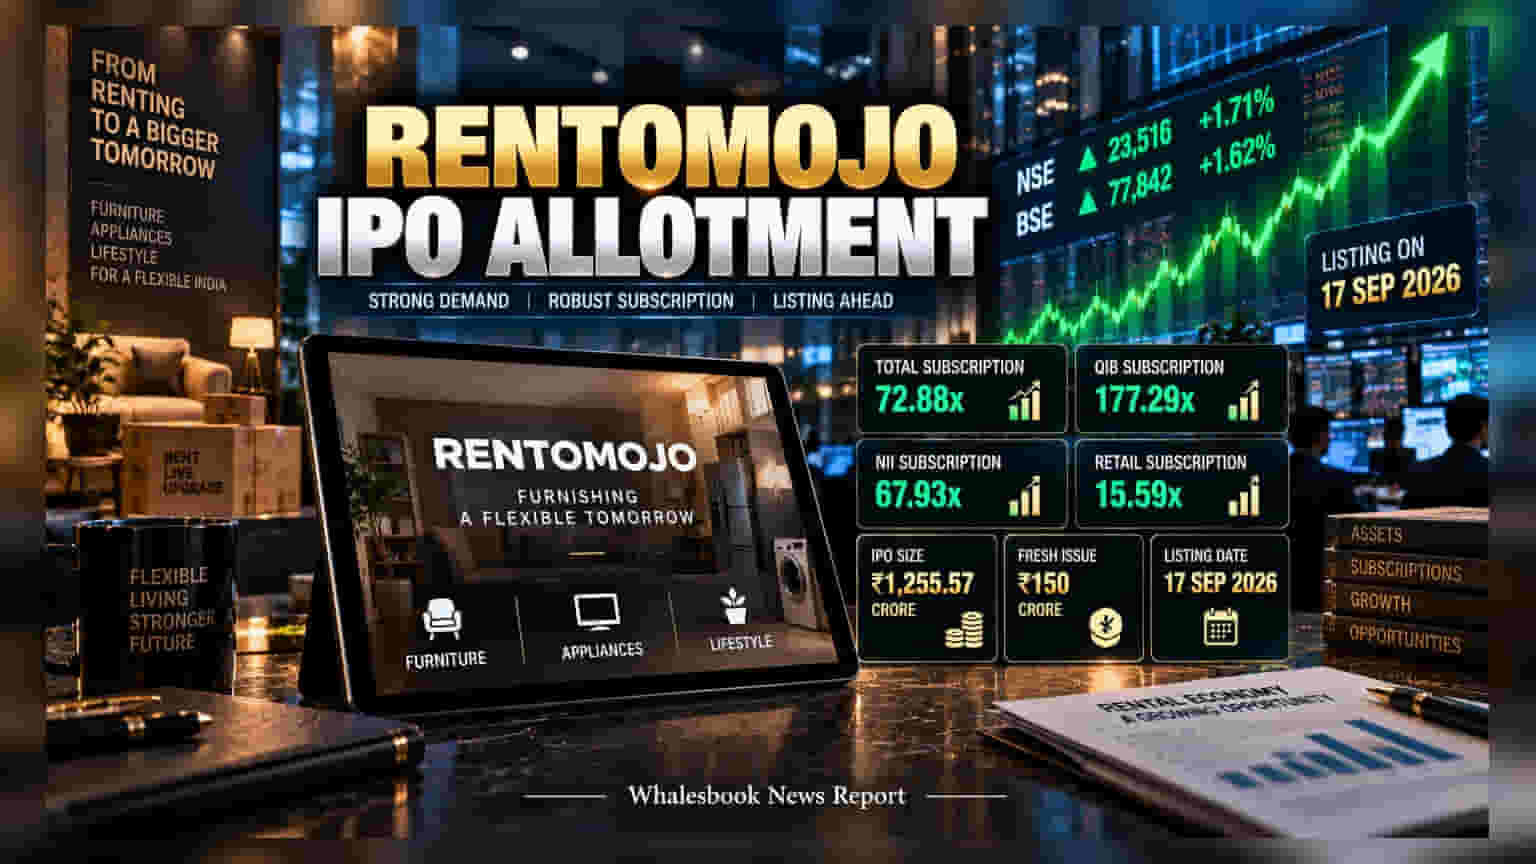
Rentomojo has finalized the allotment for its Rs 1,255.57-crore IPO after receiving bids 72.88 times the offer size. With the stock set to debut on September 17, unofficial market premiums suggest a potential listing gain of nearly 39%.
Rentomojo has completed the allotment process for its Rs 1,255.57-crore initial public offering (IPO), marking the final step before the stock hits the secondary market. Investors who applied for the issue can now verify their allotment status, with shares scheduled for credit to demat accounts by September 16. The company is set to begin trading on the National Stock Exchange (NSE) and Bombay Stock Exchange (BSE) on September 17, 2026.
Subscription and Institutional Backing
The IPO saw strong demand, with the total subscription reaching 72.88 times the shares on offer. Qualified institutional buyers, which include large professional investors like mutual funds and insurance companies, led the interest with a subscription of 177.29 times. Non-institutional investors and retail participants also showed significant interest, covering their portions 67.93 and 15.59 times, respectively. The company secured backing from prominent institutional investors, including BlackRock, Goldman Sachs, HDFC AMC, and ICICI Prudential AMC, who were allocated shares at the upper price band of Rs 404 per share.
Financial Context and Fund Usage
The IPO comprises a fresh issue of Rs 150 crore and an offer-for-sale (OFS) of Rs 1,105.57 crore. The fresh capital is primarily earmarked for debt reduction, with Rs 70 crore dedicated to paying down borrowings and interest, which may help improve the company's interest coverage ratio. Additionally, Rs 42.5 crore is allocated to cover lease and license obligations for its warehouse and experience store network. For the fiscal year 2026, Rentomojo reported a profit of Rs 104.3 crore on revenues of Rs 387 crore, reflecting the company’s recent growth trend.
Market Sentiment and Risks
Unofficial grey market trading—a private platform where shares change hands before the official listing—has indicated a potential listing gain of roughly 39%, based on a premium of about Rs 158 per share. Investors should note that grey market premiums are unregulated and not an official indicator of future stock performance, often fluctuating based on market sentiment rather than underlying fundamentals.
While the listing is highly anticipated, investors should consider the company's business structure. The offer-for-sale component is significantly larger than the fresh issue, meaning most of the money raised goes to existing shareholders rather than into the company's operations. The business model also carries inherent risks, such as high revenue concentration in the rental of furniture and appliances, potential challenges in managing working capital, and the need to scale operations profitably without needing constant equity dilution. The reliance on non-standard financial measures in past reports may also make it more difficult for investors to compare the company's performance directly with traditional retail peers. The key monitorable post-listing will be the company’s ability to sustain its profit margins while managing its debt and lease obligations.