

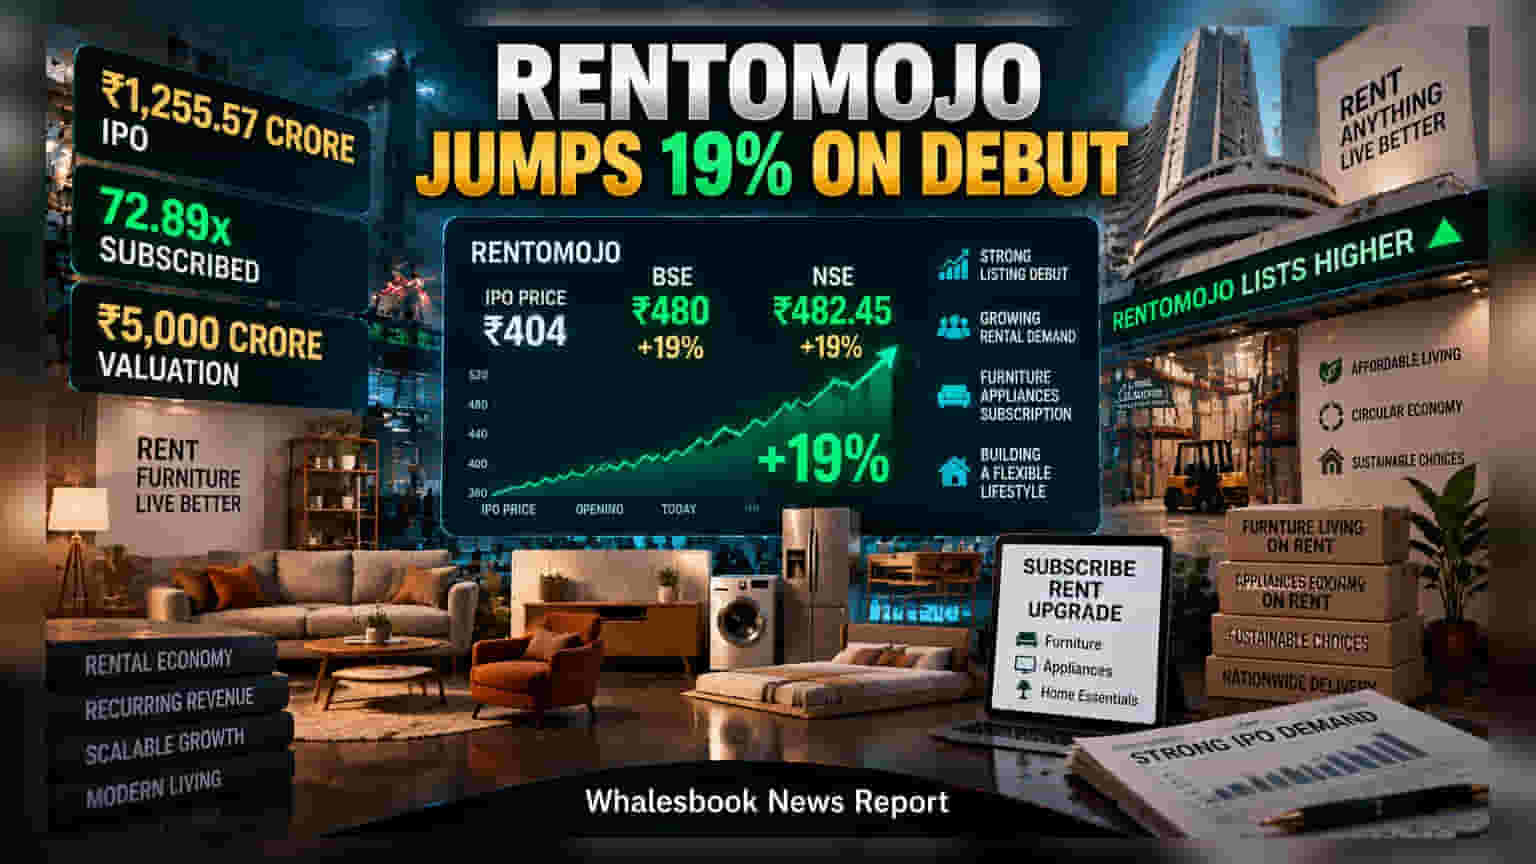
Rentomojo made a positive market entry on September 17, 2026, listing at a 19% premium over its ₹404 IPO price. Shares opened at ₹482.45 on the NSE, bringing the company's total market valuation to approximately ₹5,071 crore. Investors who participated in the highly oversubscribed IPO are now watching how the company manages its high post-listing valuation alongside its recurring rental business model.
Rentomojo successfully began its journey on the public markets today, listing at a notable premium over its initial offering price. On the National Stock Exchange, the stock opened at ₹482.45, while it started trading at ₹480 on the Bombay Stock Exchange. This marks a gain of roughly 19% for investors who were allotted shares at the IPO price of ₹404 per share.
The public offering had attracted significant interest prior to the listing, with the issue subscribed 72.89 times. This high demand was primarily driven by qualified institutional buyers. The market capitalization of the company now stands at approximately ₹5,071 crore, placing its valuation at a price-to-earnings ratio of roughly 48.62x based on recent performance metrics. For investors, this valuation puts the company in a position where market participants will look for consistent growth to justify the share price.
Business Model and Financial Context
Rentomojo operates a subscription-based model, renting out furniture and appliances. This business relies heavily on recurring rental demand, which accounts for over 97% of its operational revenue. In its latest financial performance for FY26, the company reported a profit of ₹104.3 crore on revenue of ₹387 crore, reflecting a year-on-year growth of 45.5%. However, investors should note the structure of the IPO itself. The transaction was largely an offer for sale, meaning most of the funds raised went to selling shareholders rather than into the company's bank account for future expansion. Only ₹150 crore of the total ₹1,255.57-crore issue was raised as fresh capital for the company.
Risks and Investor Monitorables
While the listing was positive, the company faces several operational and structural challenges that stakeholders are tracking. The business is capital-intensive, requiring steady investment in assets and maintenance of warehouses to support its rental inventory. Any supply chain dependency or disruption in these warehouse facilities could directly impact the company's ability to serve subscribers.
Beyond operations, there is ongoing litigation involving a co-founder, which remains a point of observation for investors concerned about governance and management stability. Furthermore, as a player in the subscription-based rental space, the company must manage the risk of customer churn and the high cost of acquiring and maintaining physical assets. Going forward, the key monitorable for the stock will be whether the company can maintain its profit margins and scale its subscriber base without requiring excessive capital, all while balancing the expectations that come with a 48.62x earnings multiple.