

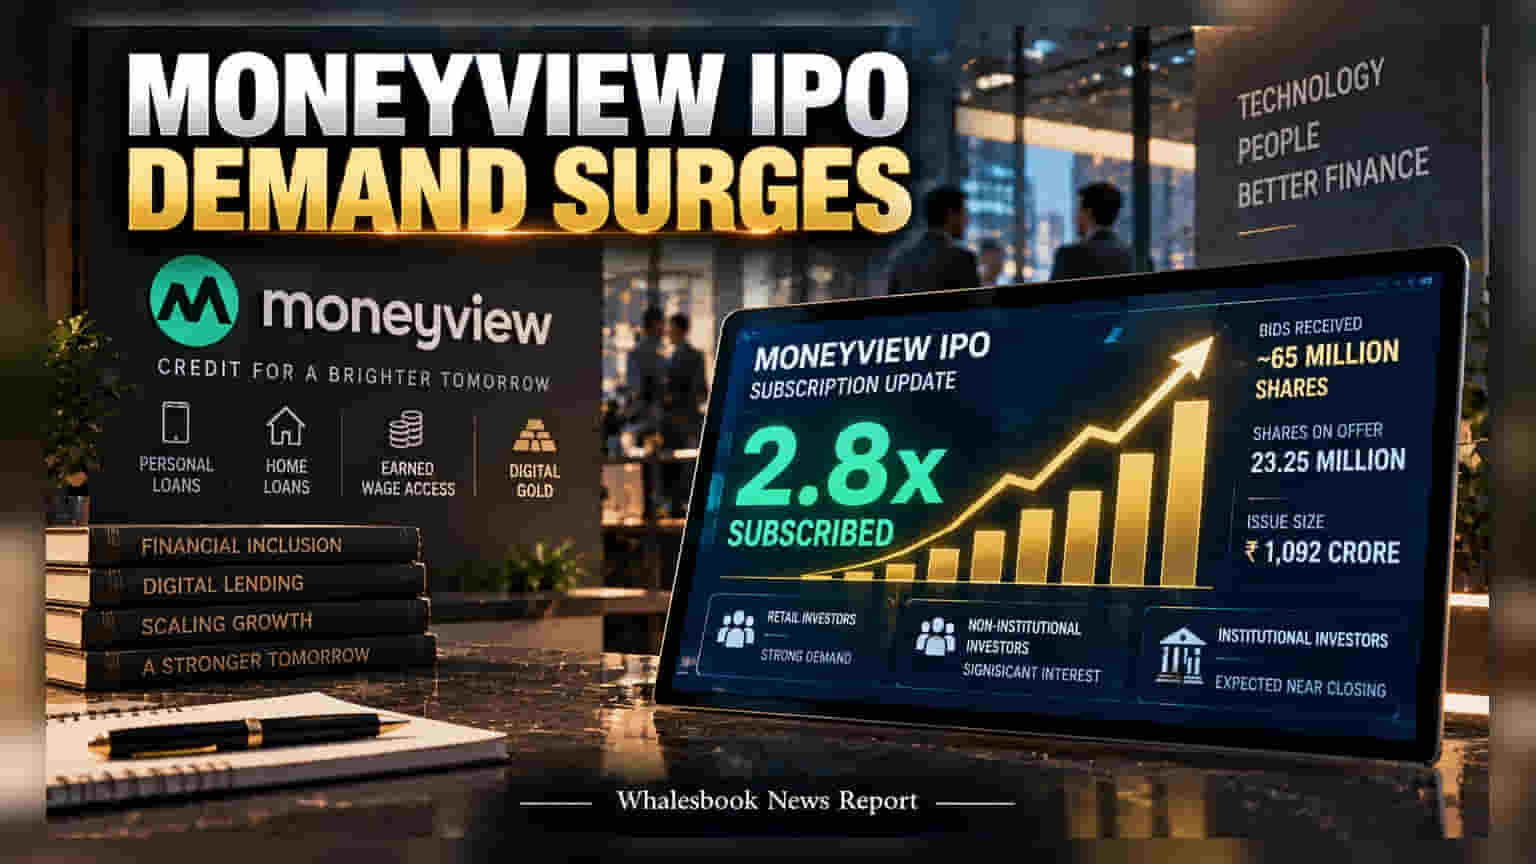
Digital lender Moneyview saw its Rs 1,092-crore IPO get subscribed 2.8 times by midday on its second day. Strong interest from retail and non-institutional investors is driving the demand. The company plans to use the fresh capital to expand its lending operations and strengthen its NBFC subsidiary.
Moneyview’s initial public offering gathered momentum on its second day, with subscription reaching 2.8 times by Friday midday. Investors bid for nearly 65 million shares against the 23.25 million shares on offer. The Rs 1,092-crore public issue has attracted interest primarily from retail and non-institutional investors, while the institutional segment is expected to finalize their participation as the issue approaches its closing date on September 28.
The IPO comprises a fresh issue of Rs 750 crore, which the company plans to utilize for business growth. A significant portion—Rs 325 crore—is earmarked for expanding its lending activities, while Rs 250 crore is set to strengthen the capital base of its non-banking financial company subsidiary. This capital injection is crucial for an NBFC, as it directly impacts the ability to leverage and grow the loan book in the competitive digital lending space.
Since its founding in 2014, Moneyview has built its business on a digital-first model, automating credit assessment using technology. While personal loans have traditionally been the main revenue source, the company is diversifying into home loans, earned wage access, and digital gold. For investors, this shift indicates an attempt to reduce concentration risk, but the digital lending sector in India remains sensitive to regulatory changes. The Reserve Bank of India has maintained close scrutiny of the unsecured lending segment, which includes personal loans, to manage systemic risks.
Potential investors should note that in the fintech NBFC space, asset quality is a critical metric. Tracking non-performing assets and how the company manages default risks in a fluctuating credit environment will be essential. Unlike traditional lenders with physical branches, the firm’s model relies on digital acquisition and credit scoring, which makes its technology infrastructure and data security practices important monitorables. The final outcome of the listing will depend on broader market sentiment regarding growth prospects versus regulatory conditions in the digital lending sector.