

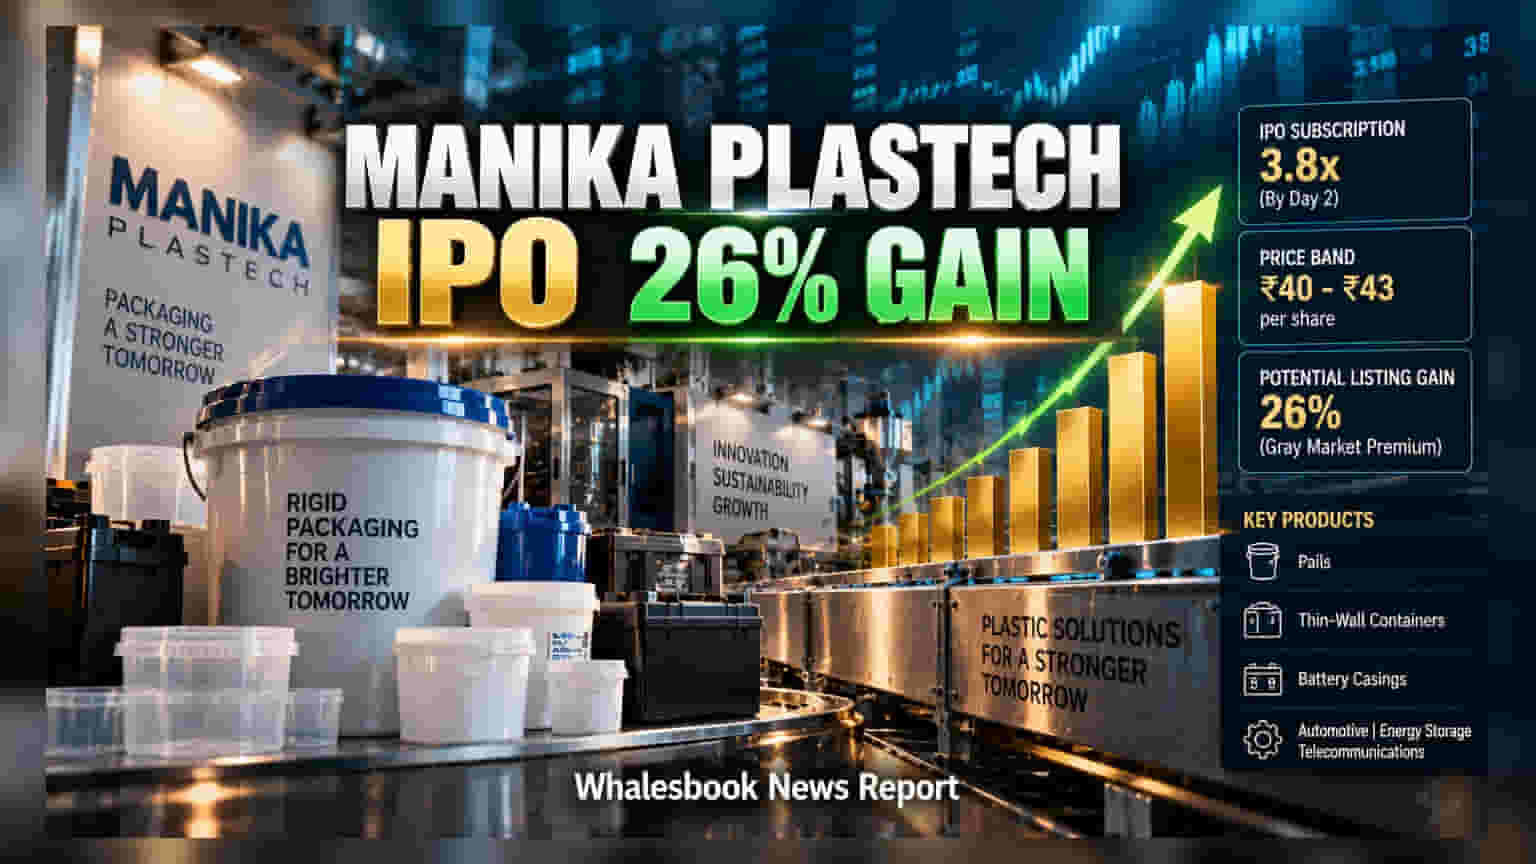
Manika Plastech's Rs 125.5-crore IPO continues to see strong investor interest, reaching 3.8x subscription by the second day. While grey market premiums suggest a 26% listing pop, investors should consider customer concentration risks and moderate revenue growth.
Investor interest in the Manika Plastech initial public offering remains active as the issue reached 3.8 times subscription by the second day of bidding. The company, which is looking to raise Rs 125.5 crore, opened its subscription window on September 11 with a price band set between Rs 40 and Rs 43 per share. The issue includes a fresh share issuance worth Rs 92.5 crore and an offer for sale component of Rs 33 crore.
Market sentiment for the listing appears optimistic, with the grey market—an unofficial trading platform—indicating a potential listing premium of approximately 26 percent. While this often reflects strong short-term demand, it is important for investors to remember that these premiums are unofficial and do not guarantee actual listing gains once the stock begins trading on the NSE and BSE, tentatively scheduled for September 21.
Manika Plastech operates in the rigid polymer packaging sector, manufacturing products like pails, thin-wall containers, and battery casings. These products are supplied to diverse industries including automotive, energy storage, and telecommunications. The company currently manages seven production facilities with an annual capacity of 29,200 metric tonnes. With this fundraising, the management plans to allocate Rs 54.9 crore toward upgrading plants and machinery to expand capacity, while using Rs 15 crore to reduce existing debt.
While the demand momentum is visible, a closer look at the company's financial profile reveals specific factors that investors should track. The company’s revenue growth has been relatively moderate, with a compound annual growth rate (CAGR) of approximately 7 percent recorded between the 2022 and 2026 financial years. Furthermore, the company faces customer concentration risk, with its top five clients accounting for nearly 58 to 63 percent of total revenue. This means that any business downturn or policy shift at these key clients could directly impact the company's performance. Additionally, the company is relatively new in some of its newer product segments, such as thin-wall containers, having entered these areas in 2024.
For those observing the IPO, the next key monitorable will be the final subscription levels by the time the issue closes on September 16, and the official allotment status. Long-term investors may also wish to track how effectively the company executes its planned capacity expansion and whether it can diversify its client base to reduce dependence on its top five customers.