

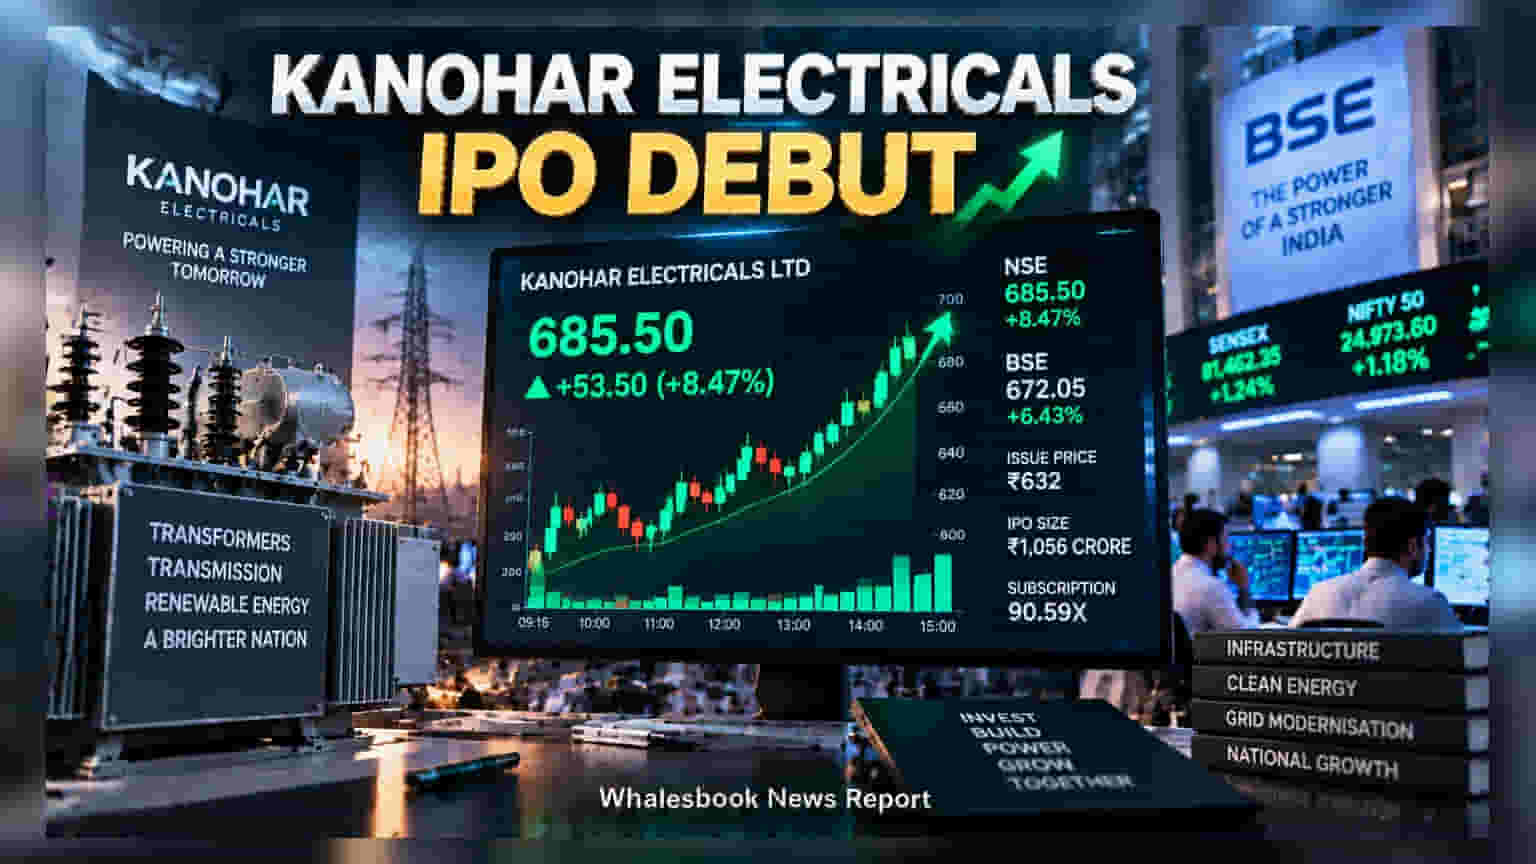
Kanohar Electricals made a modest market debut on Wednesday, with shares opening at ₹685.50 on the NSE against an issue price of ₹632. Despite a strong IPO subscription of 90.59 times, the listing failed to meet grey market expectations of 30-40% gains. This gap highlights a cooling in investor enthusiasm once the stock entered public trading.
Kanohar Electricals Ltd began trading on Indian stock exchanges today, September 16, 2026. The stock opened at ₹685.50 on the National Stock Exchange, marking an 8.47% premium over its issue price of ₹632. On the BSE, the shares opened slightly lower at ₹672.05, representing a 6.43% gain. While the positive start confirms interest, the performance fell short of the high expectations set by grey market trackers, which had earlier suggested potential returns in the 30% to 40% range.
The debut follows a highly anticipated IPO that was subscribed 90.59 times. This high subscription rate had fueled hopes for a stronger listing day pop, but the actual market opening suggests a more conservative approach from investors today. The total IPO size was ₹1,056 crore, which included a mix of a fresh issue of shares and an offer for sale by existing owners.
From a financial perspective, the company intends to use ₹300 crore from the fresh issue of shares to fund its growth. Specifically, management has allocated funds for new equipment at its Gangol facility and for day-to-day working capital needs. A larger portion of the IPO, roughly ₹756 crore, consisted of shares sold by the K Sons Family Trust, which means this money goes to the selling shareholders rather than into the company’s bank account for business development.
Kanohar Electricals operates as a manufacturer in the power transmission and renewable energy space, supplying equipment like transformers to railways and power utilities. Success in this field is deeply tied to government infrastructure spending and power grid upgrades. However, the business model comes with specific challenges that shareholders should monitor. Because it relies heavily on winning government and utility tenders, revenue can be unpredictable from one quarter to the next.
Additionally, the company faces exposure to raw material price fluctuations, particularly for copper and CRGO steel, which are essential for transformer production. If these input costs rise, the company’s profit margins could come under pressure. Investors should also be aware of the intense competition in the power equipment sector, where larger, well-established manufacturers often compete for the same infrastructure projects.
Looking ahead, the next few quarters will be important for understanding whether the company can maintain healthy margins and scale up its operations. Key monitorables for investors include the pace at which the company executes its order book, its ability to manage rising raw material costs, and updates on the capacity expansion at its Gangol manufacturing unit.