

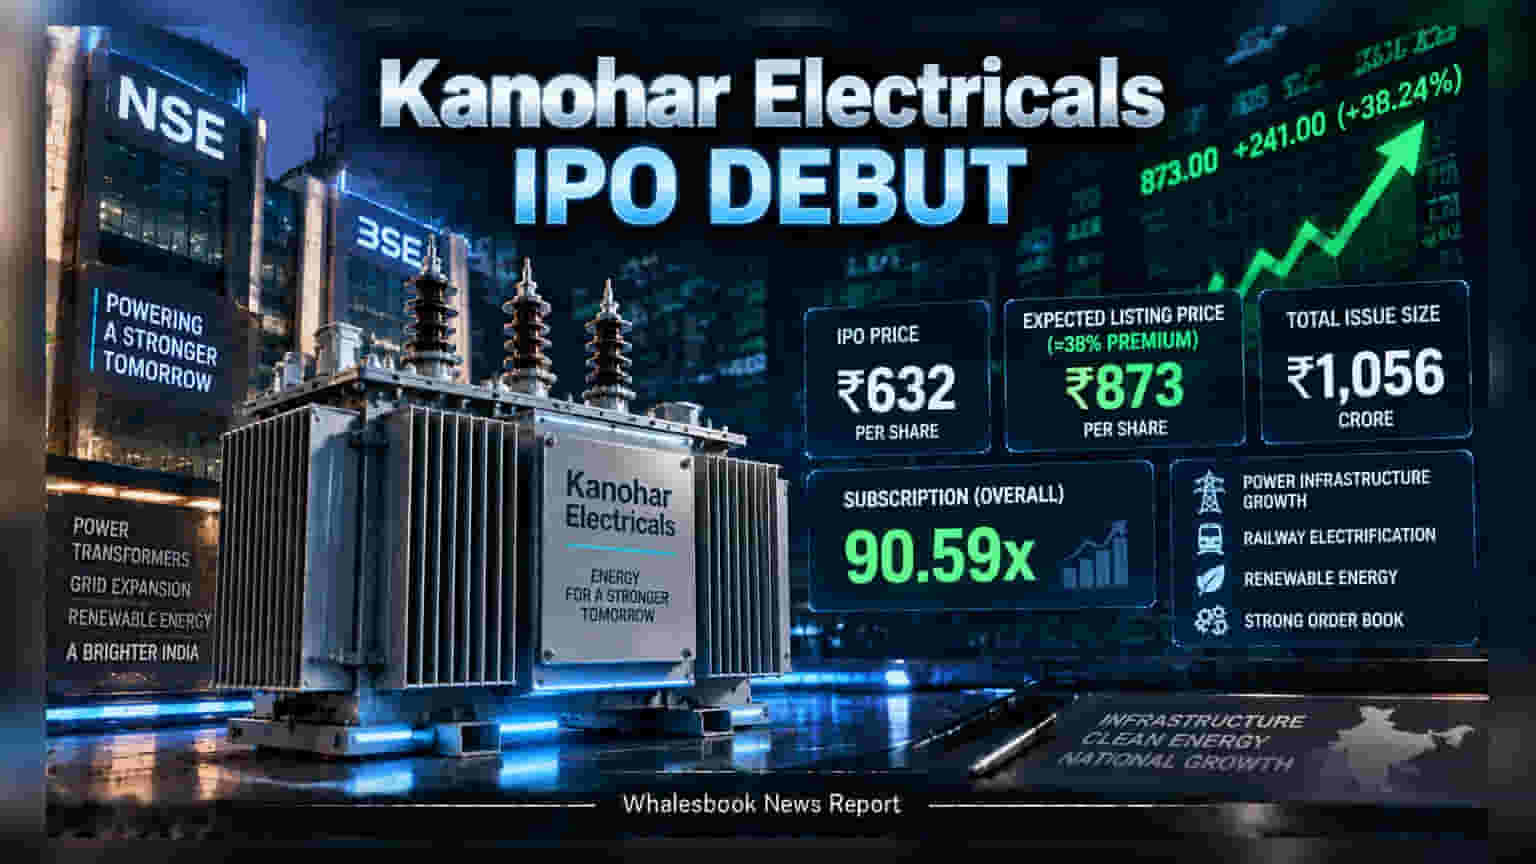
Kanohar Electricals is set to list on stock exchanges this Wednesday with an expected premium of nearly 38% over its ₹632 issue price. The ₹1,056-crore IPO witnessed strong demand, subscribing over 90 times. While a large order book and power sector tailwinds drive excitement, investors should carefully consider the company's high customer concentration and reliance on government tenders before tracking its post-listing performance.
Kanohar Electricals is scheduled to debut on the NSE and BSE on Wednesday, September 16, 2026. The company’s ₹1,056-crore initial public offering (IPO), which concluded last week, was priced at ₹632 per share. Based on current trends in the grey market, the stock is expected to list at a premium of approximately 38%, which would place its opening price near ₹873 per share.
The public offer saw high interest from investors, closing with an overall subscription of 90.59 times. Participation was particularly strong among Qualified Institutional Buyers (QIBs), who subscribed 215.37 times, followed by Non-Institutional Investors (NIIs) at 87.74 times and retail investors at 20.51 times. This high subscription level reflects positive market sentiment toward companies integrated into India’s power infrastructure expansion.
Financial and Operational Context
The company is a manufacturer of power transformers and provides engineering and construction services for transmission and distribution projects. As of March 31, 2026, the company reported revenue of ₹653.8 crore and a profit of ₹129.73 crore. Its order book stands at ₹1,818 crore, providing significant revenue visibility that is roughly 2.8 times its annual revenue for FY26. The firm’s growth is currently linked to major government initiatives in grid expansion, railway electrification, and renewable energy integration.
Risk Factors to Monitor
While the order book suggests a strong pipeline, investors should be aware of several operational risks. The company has a high level of customer concentration, with its top 10 clients accounting for approximately 93% of total revenue. This concentration means the loss of a major client or a change in their spending could impact the company's financial performance significantly.
Additionally, the business model relies heavily on government tenders and utility orders. This dependency exposes the company to risks such as policy shifts, project payment delays, or potential blacklisting, which could stall growth. Furthermore, the company faces execution risks inherent in Engineering, Procurement, and Construction (EPC) projects, where time delays or cost overruns can directly pressure profit margins.
Operational risks also include geographic concentration, as most manufacturing is centered around facilities in Meerut, and raw material price volatility. Since the company does not have long-term contracts with all its suppliers, fluctuations in the cost of copper, steel, or transformer oil can affect profitability. As the stock begins trading, the key monitorable for shareholders will be the company’s ability to execute its order book efficiently while managing these concentration and execution risks.