

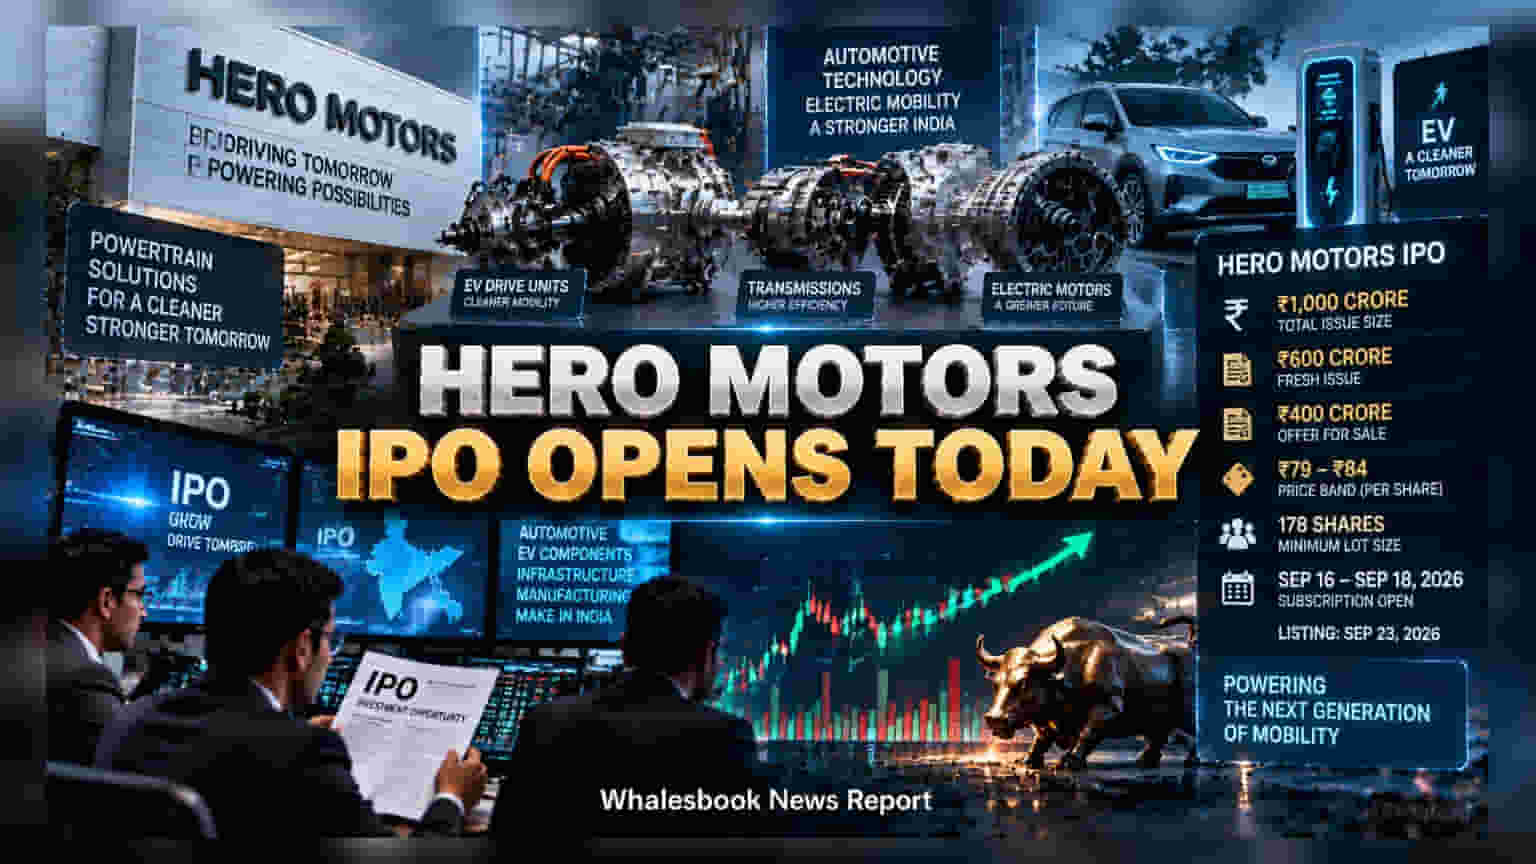
The ₹1,000 crore Hero Motors IPO opened for subscription on September 16, 2026, and will remain available until September 18. Priced at ₹79-84 per share, the issue combines fresh capital and existing shares. Investors should weigh the company's electric vehicle expansion plans against verified risks, including significant customer concentration, negative free cash flow, and premium valuation.
Hero Motors has launched its initial public offering (IPO) today, September 16, 2026, with the subscription window set to remain open until September 18. The company is aiming to raise ₹1,000 crore, consisting of a fresh issue of ₹600 crore and an offer-for-sale component of ₹400 crore. The price band for the issue has been fixed at ₹79 to ₹84 per share, with a minimum lot size of 178 shares, requiring a minimum investment of ₹14,952 for retail investors.
The company operates as a key player in the automotive technology space, focusing on powertrain solutions for both electric and conventional vehicles. Its product range includes electric drive units, transmissions, and motors. Ahead of the public issue, the company secured ₹300 crore through an anchor investor round, indicating institutional interest in its business model.
Financial performance shows steady growth, with FY26 revenue from operations reaching ₹1,188.4 crore, up from previous years. Profit after tax stood at ₹41.2 crore. While the company is positioning itself as a beneficiary of the global shift toward electric mobility, its business is still heavily dependent on conventional combustion engine technology, which accounts for 77% of its total revenue. This indicates that a substantial part of the company's current income is tied to legacy vehicle segments rather than electric vehicles.
Investors looking at this offering should consider several operational and financial risks. A major concern is client concentration; approximately 36% of the company's revenue comes from a single top customer, which introduces significant dependency. Additionally, the company has reported negative cumulative free cash flow over the last three years, suggesting that it has been spending more cash than it generates from its operations. This, combined with an underutilization of certain overseas manufacturing facilities, could impact future financial flexibility.
From a valuation standpoint, the IPO is being offered at a price-to-earnings (P/E) multiple of approximately 92x. This is notably higher than several peers in the automotive component sector, such as Sona BLW Precision Forgings, Uno Minda, Varroc Engineering, Endurance Technologies, and CIE Automotive. Investors may need to evaluate whether this valuation is justified by the company's growth outlook or if it carries a premium that requires careful consideration. The debt-to-EBITDA ratio, which was reported at 2.24x for FY26, is another metric that market participants typically monitor to gauge the company’s ability to manage its borrowings.
The proceeds from the fresh issue are intended for debt repayment and funding capital expenditure. The company’s ability to successfully execute its expansion plans, maintain its client relationships, and improve cash flow generation will be critical to watch after the stock lists. The tentative date for the company's listing on the NSE and BSE is September 23, 2026.