

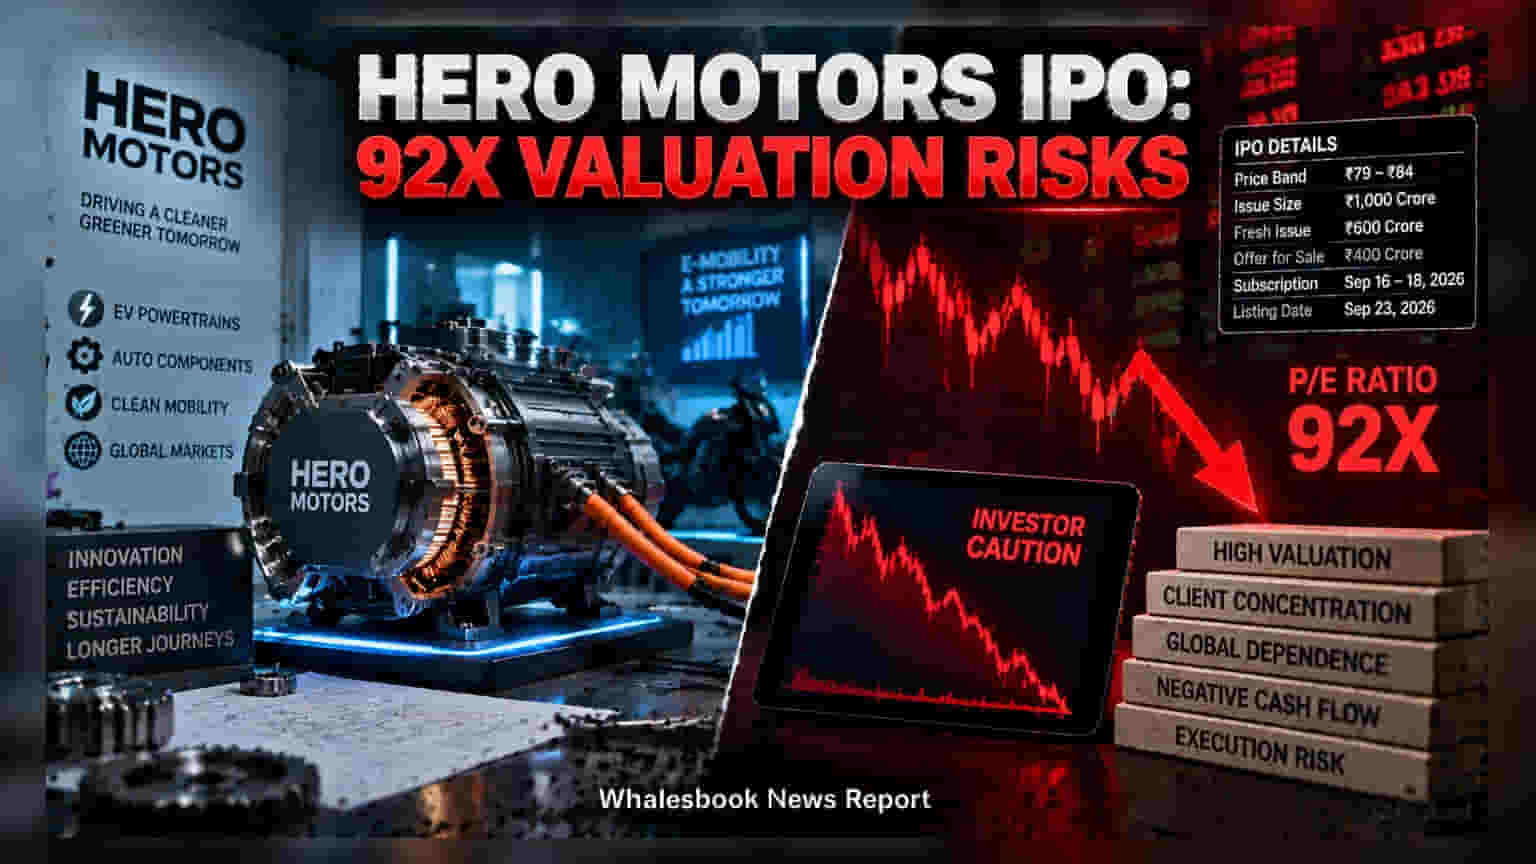
The Hero Motors IPO is open for subscription from September 16 to September 18, 2026, with a price band of ₹79–₹84. While the company is betting on its growing electric vehicle segment, investors are debating the high 92x valuation and business risks like heavy client concentration.
Hero Motors has launched its ₹1,000-crore Initial Public Offering (IPO), allowing the public to invest in the company for the first time. The subscription window for the IPO is open from September 16 to September 18, 2026. The company has set a price band of ₹79 to ₹84 per share, with a minimum lot size of 178 shares for retail investors.
The IPO consists of a mix of new shares being issued by the company to raise ₹600 crore and an offer for sale, where existing shareholders will sell shares worth ₹400 crore. The primary goal of the new share issue is to fund business expansion and manage working capital needs. The company is scheduled to list on the stock exchanges on September 23, 2026.
A central topic of discussion among market observers is the company's valuation. Based on the IPO price, Hero Motors is asking for a price-to-earnings (P/E) multiple of approximately 92 times its recent earnings. In financial terms, this is a premium valuation, meaning investors are paying a high price for every rupee of current profit. This valuation is notably higher than the median P/E ratio seen in many established auto component companies. Investors often compare this to the company's growth prospects, particularly its push into the electric vehicle (EV) segment.
Management is emphasizing a shift toward e-mobility. In the financial year 2026, EV-related business accounted for 23% of total revenue, which is an increase from about 12% in FY24. The company has also maintained a higher spending level on research and development compared to the typical 2-4% industry standard, as it attempts to secure a stronger position in the global EV component market. Despite this growth, the company's revenue remains largely tied to legacy products like internal combustion engines, which faces a long-term shift toward electrification.
There are specific risks highlighted in the company’s filings that investors should carefully consider. Customer concentration is a significant factor, as the top ten clients account for approximately 73% of the company's total revenue. Even more specifically, one major client contributes over 35% of revenue. If that client were to change its sourcing strategy, the company's financials could be materially affected. Furthermore, nearly 41% of revenue is generated from international markets, particularly Europe. This reliance makes the company sensitive to changes in trade policy, geopolitical shifts, and economic conditions in those regions.
Financially, while the company has seen top-line growth, it has reported a profit of ₹41.17 crore on a total income of ₹1,216.74 crore for FY26. Investors may also want to monitor the company's cash flow, as heavy capital spending on new manufacturing facilities has recently resulted in negative free cash flow. The company’s ability to use its new manufacturing capacity effectively will be a key factor to watch following the IPO.