

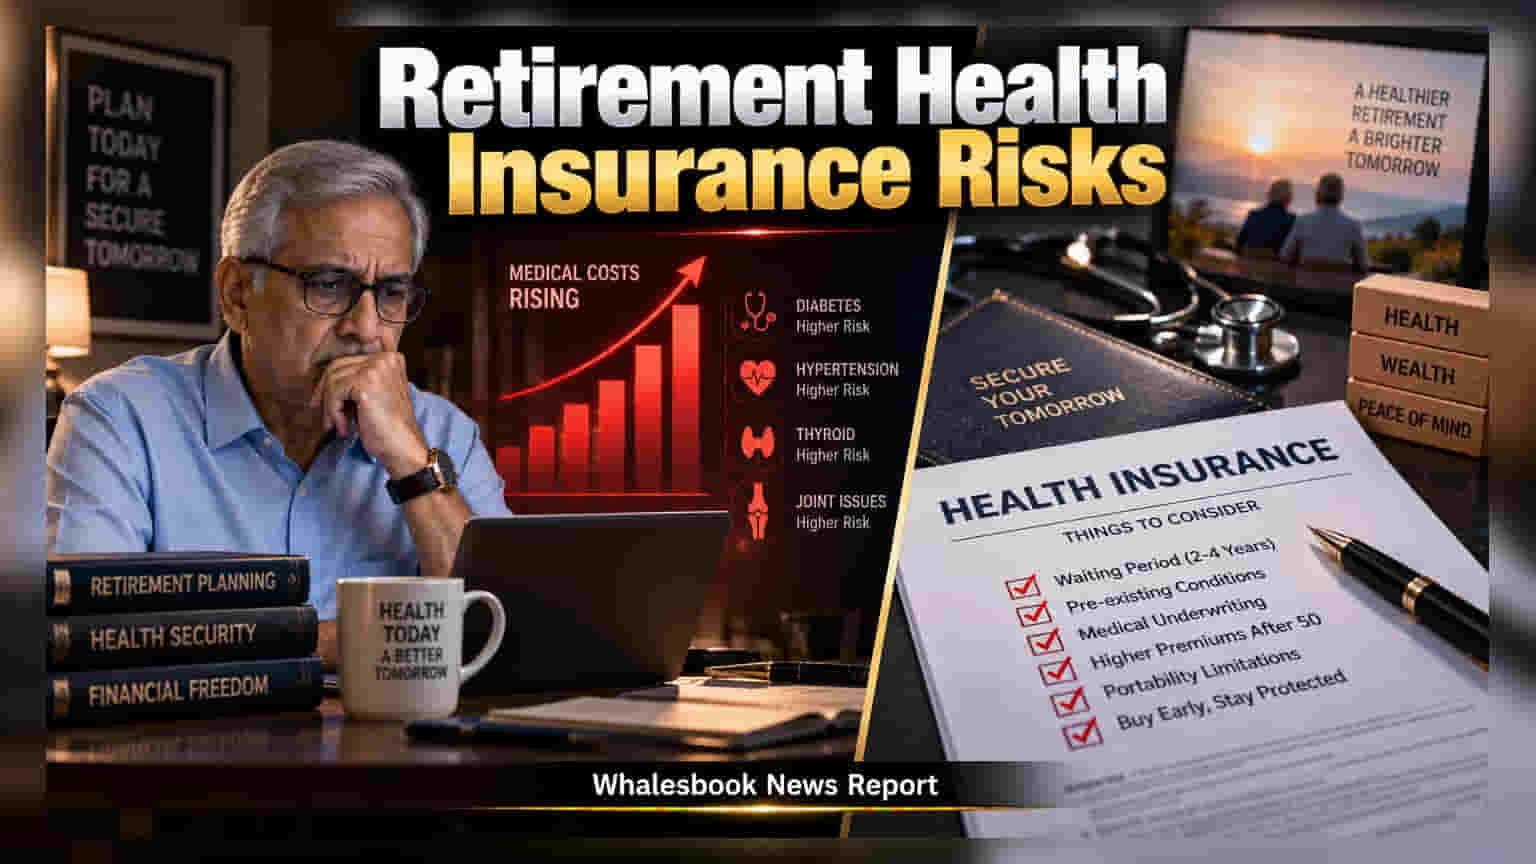
Many professionals rely solely on company-provided health insurance, failing to realize it stops the moment they retire. Transitioning to a private plan later often leads to higher costs, strict medical checks, and long waiting periods for existing health conditions. Securing an independent policy while still employed is a critical step to ensure lifelong coverage.
For many professionals in India, company-provided health insurance, often called Group Mediclaim, is a reliable safety net during their working years. However, this coverage is tied strictly to employment status. Once a professional retires, this insurance vanishes immediately. Relying on this plan as a primary safety net for retirement is a common financial mistake that leaves many seniors vulnerable to sudden medical costs.
The Waiting Period Trap
The biggest risk in waiting until retirement to buy personal health insurance is the waiting period for pre-existing conditions. When you buy a fresh retail health policy after age 50 or 55, insurers often apply a waiting period of two to four years before they will cover treatments for conditions you already have, such as diabetes, hypertension, or thyroid issues. By depending only on an office plan until the day of retirement, you delay purchasing a personal policy. If you develop a health condition while working, a new insurer may force you to wait years before covering it, creating a dangerous coverage gap during your golden years.
Medical History and Underwriting
Unlike group insurance, which typically offers 'no-questions-asked' coverage for all employees, individual or retail health plans require medical underwriting. This means the insurance company will assess your health history before accepting you. If you apply for insurance after retirement and have already been diagnosed with significant health issues, the insurer may increase your premium, exclude certain conditions entirely, or in some cases, reject the application. Securing a policy while you are younger and healthier ensures smoother acceptance and broader coverage.
Strategic Transitioning
One effective strategy is to purchase a base retail health policy while you are still employed. This allows you to complete the mandatory waiting periods for pre-existing conditions while you are still covered by your company's Group Mediclaim. Once you retire, you can continue with this personal policy, which provides uninterrupted protection. For those looking to manage costs, combining a base policy with a top-up or super top-up plan can provide a larger insurance cover at a more affordable premium.
Another option is the portability feature mandated by the IRDAI. This allows you to switch from one insurer to another or from a group policy to an individual policy while retaining the credit for waiting periods you have already served. However, portability has its own limits, and insurers often have the right to accept or reject these applications based on their own rules. Therefore, buying an independent policy early remains a more reliable approach than waiting to port a plan at the time of retirement. Before finalizing any policy, it is vital to be transparent about your medical history, as non-disclosure is the most common reason for claim rejections.