

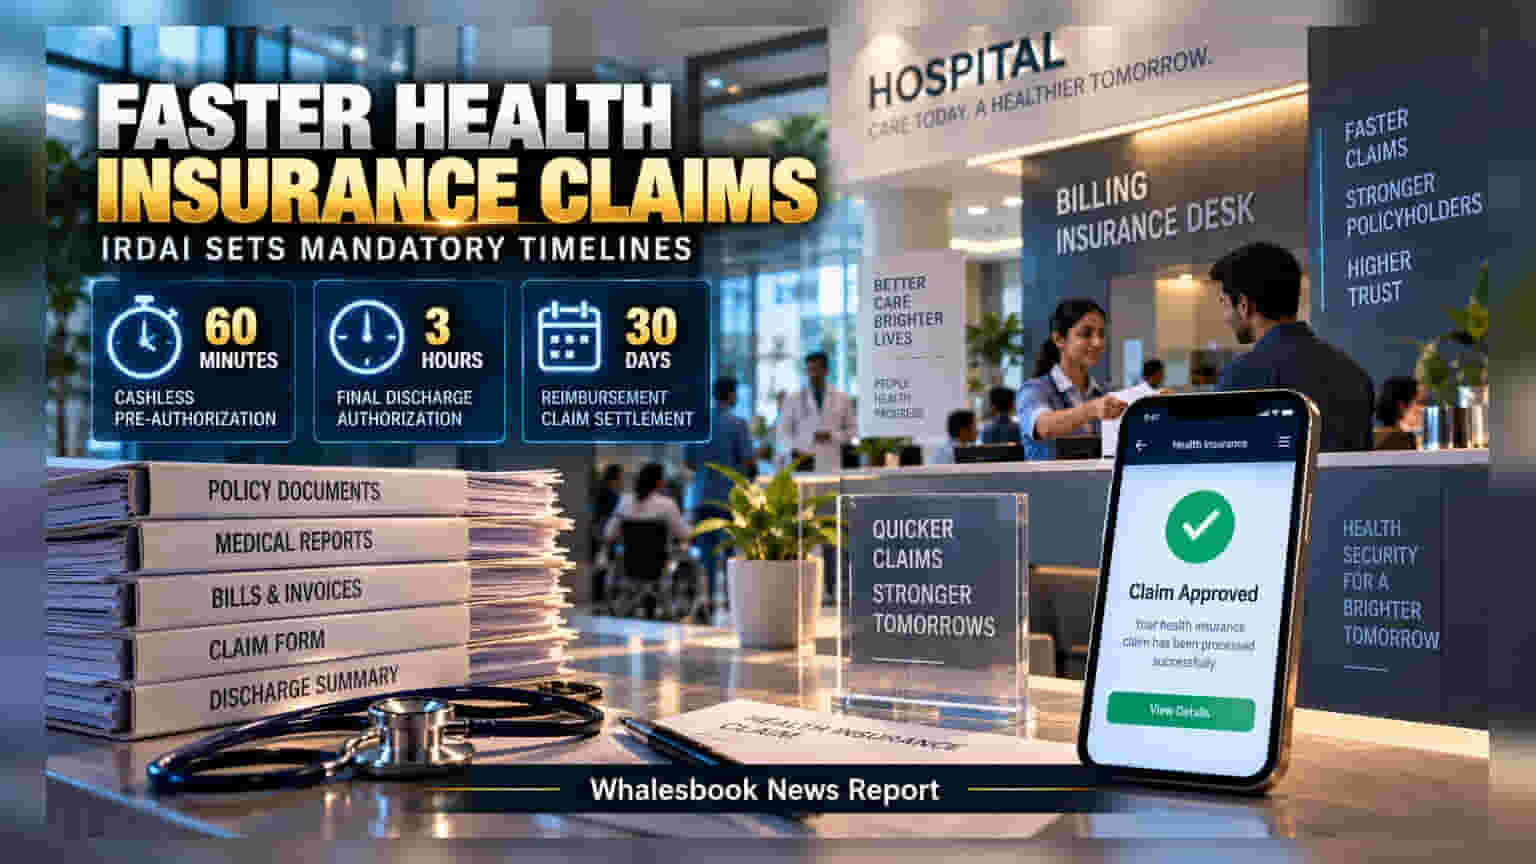
The Insurance Regulatory and Development Authority of India (IRDAI) has enforced strict new timelines for health insurance settlements. Cashless claims must now be authorised within one hour, with final discharge approvals within three hours. Reimbursement claims require settlement within 30 days. These rules aim to improve service efficiency but may increase operational compliance costs for insurance companies.
The Insurance Regulatory and Development Authority of India (IRDAI) has introduced mandatory timelines for health insurance claim settlements, aiming to reduce the administrative burden on policyholders. Under the new regulations, insurance companies must process cashless pre-authorization requests within 60 minutes of receiving the request. Furthermore, final discharge authorization must be provided within three hours after the hospital submits the necessary documentation. These timelines are designed to prevent delays at hospital billing counters during critical care moments.
For reimbursement-based claims, the regulator has set a 30-day window for insurers to either settle or reject the claim after receiving all required documentation. In cases where an investigation is necessary, this process must be completed within 45 days. To prevent the practice of frequent, fragmented requests for additional documents, the IRDAI now expects insurers to list all necessary paperwork upfront, shifting the burden of efficiency onto the companies.
Operational Impact for Insurers
These changes place pressure on the operational infrastructure of health insurance companies. Meeting such tight deadlines often requires significant investment in technology, automation, and additional support staff to manage the increased volume of real-time requests. Listed entities such as Star Health and Allied Insurance, along with large multi-line insurers like ICICI Lombard and HDFC Ergo, will need to enhance their digital capabilities to remain compliant. While these measures are expected to improve customer satisfaction and brand trust, investors may watch for any immediate impact on operational expenses and profit margins during the transition period.
Protecting Policyholders
Beyond speed, the regulator has strengthened protection against claim rejections. Insurers are now required to provide a detailed, written explanation citing specific policy conditions if they deny a claim, ending the practice of vague or verbal rejections. This creates a clearer path for policyholders to appeal to the Insurance Ombudsman if they believe a rejection was unfair. Additionally, the regulator has solidified the 60-month moratorium rule. After a policy has been active for five continuous years, insurers generally cannot contest claims on the grounds of non-disclosure, unless they can prove actual fraud. This provides long-term security for policyholders by reducing the risk of claims being denied years into the policy term.
What Investors Should Track
Investors may monitor how quickly insurance companies adapt their internal workflows to these mandates. The ability to process claims within these strict timelines without compromising on fraud detection will be a key performance indicator. While the regulator's push for efficiency is consumer-centric, the long-term impact on the sector will depend on how effectively insurers balance these strict service requirements with underwriting discipline and cost management.