

The insurance regulator has proposed new limits on distribution expenses to curb payouts that have outpaced premium growth. The plan targets high commissions in bancassurance, aiming to lower costs and protect policyholder value. Investors are watching to see how this impacts profit margins and new business sales for major life insurance companies.
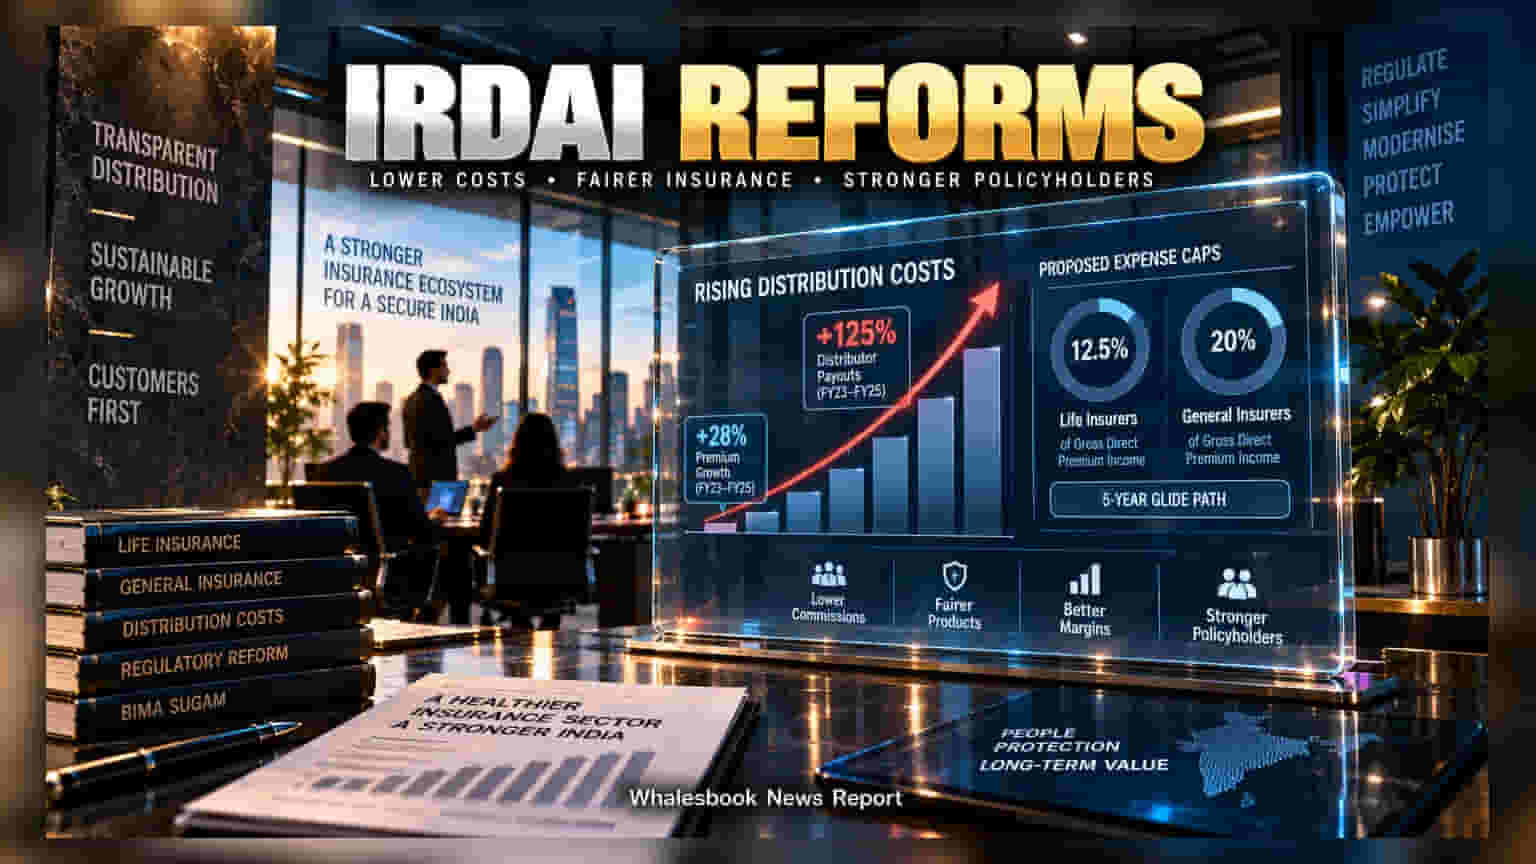
The Insurance Regulatory and Development Authority of India (IRDAI) has released a consultation paper proposing a strict cap on distribution costs. This move is designed to control rising expenses that the regulator says are eroding value for policyholders. Under the proposal, life insurance companies would see their operating expenses capped at 12.5% of their Gross Direct Premium Income, while general insurers would face a limit of 20%. The regulator plans a five-year glide path to help companies transition to these new limits.
The need for this regulation stems from a sharp rise in payments made to distributors, which include agents and banks. Data from the regulator shows that while premium growth for some corporate agents grew by 28% between FY23 and FY25, the total payouts to these distributors skyrocketed by 125%. Currently, these distribution costs consume roughly 27% of first-year premiums in the life insurance sector. The regulator notes that this business model has become unsustainable and inefficient.
Bancassurance—the practice of selling insurance through bank branches—is a major focus of these new rules. Currently, some group credit life products carry payouts as high as 72%, significantly higher than the average commission. Because these high incentives are often tied to loan sales, the regulator is concerned about consumer choice and product bundling. If the final rules cap these commissions, banks may have less incentive to push insurance products, which could challenge the sales volume for insurance companies that rely heavily on this channel.
For investors in listed life insurance companies, the impact of these changes is a critical monitorable. A reduction in commission costs could improve operating profit margins over time, as insurers would spend less to acquire new business. However, there is a risk that lower incentives could slow down the growth of new policies if distributors reduce their sales efforts. The market will be watching to see if insurers can maintain their sales momentum under the new, stricter cost structure.
Beyond cost caps, the regulator also plans to simplify the industry by consolidating various intermediary categories into new, structured entities. This, combined with the launch of the digital marketplace Bima Sugam, aims to move the industry toward a model where customers seek out products themselves rather than relying on high-commission-driven sales. Investors should track the final implementation of these rules and the management commentary from insurance firms regarding how they plan to restructure their distribution partnerships and maintain margins.