

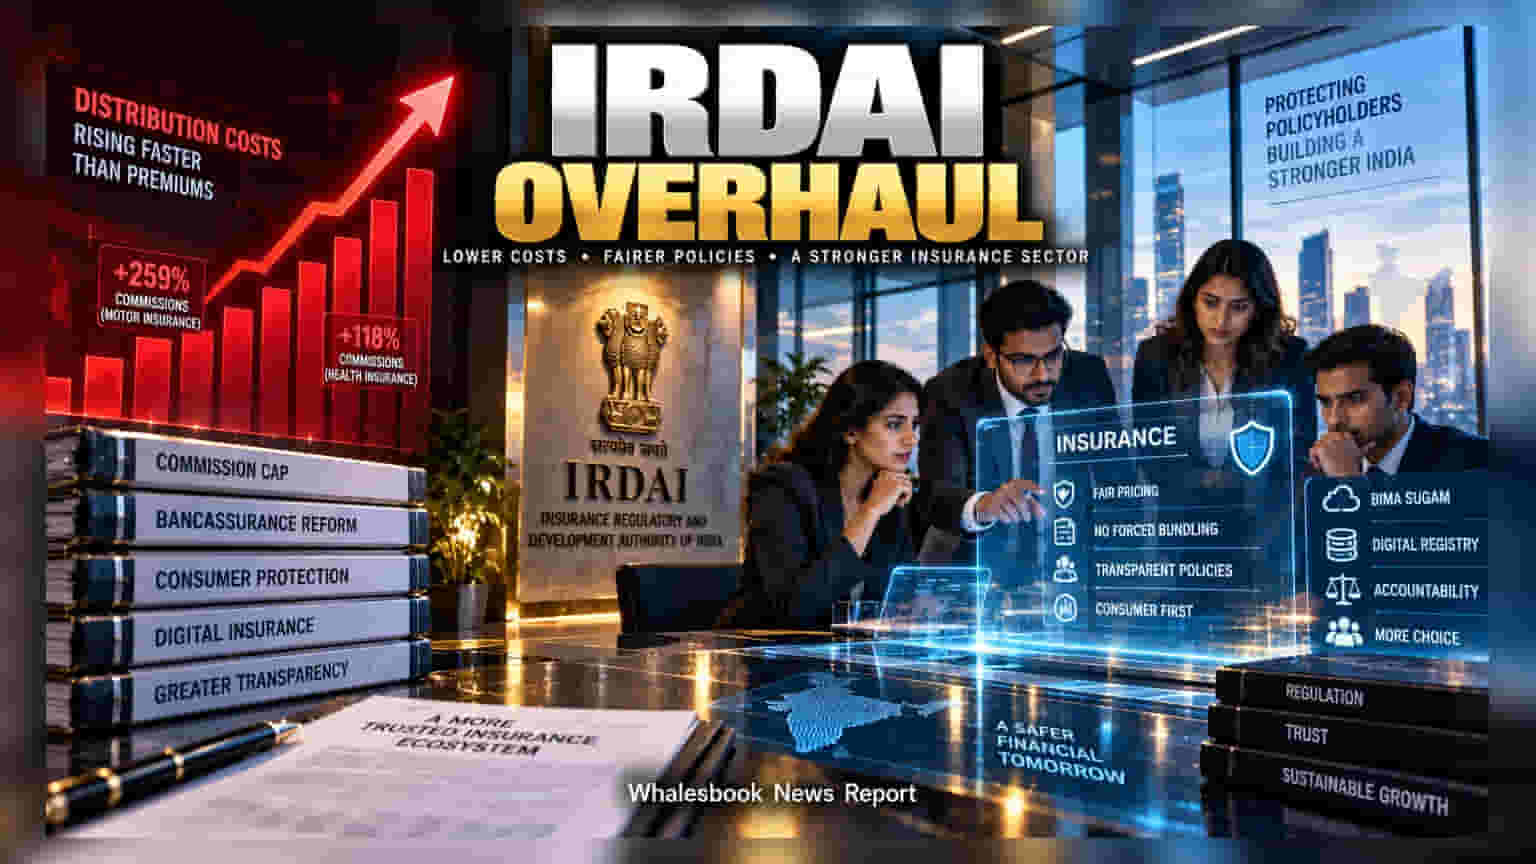
The IRDAI has released a consultation paper to cap rising insurance distribution costs after commissions significantly outpaced premium growth between FY23 and FY25. The proposals aim to end mandatory loan-linked insurance, tighten bancassurance rules, and introduce accountability for mis-selling. Investors may track how these changes impact bank fee income and insurance company margins.
The Insurance Regulatory and Development Authority of India (IRDAI) has proposed significant changes to the way insurance products are sold in the country. The regulator is seeking to control the rising costs of insurance distribution, which it argues have grown faster than the actual insurance premiums collected. These changes are part of a consultation paper issued to stakeholders, with feedback invited until October 25, 2026.
The regulator has flagged a wide gap between premium growth and the money paid out to distributors as commissions. Data shared by the IRDAI shows that between the 2023 and 2025 financial years, motor insurance premiums grew by approximately 34%, while commissions paid to distributors rose by 259%. Similarly, in the retail health insurance segment, premiums increased by 53%, but commissions jumped by 118%. To correct this imbalance, the regulator plans to introduce a singular commission cap that will include all types of incentives, rewards, and bonuses, ensuring that companies cannot bypass cost restrictions.
Impact on Bancassurance and Loan Bundling
One of the most significant changes proposed concerns the practice of bancassurance, where banks sell insurance products to their customers. Currently, banks contribute about 45% of private life insurance premiums. The regulator is now moving to ban the practice of making insurance purchase a mandatory condition for loan approval. Under the new rules, customers must be provided with clear, transparent pricing for loans both with and without insurance coverage.
Furthermore, the IRDAI plans to prohibit employees of banks and non-banking financial companies from receiving volume-linked rewards and non-monetary incentives, such as sponsored contest trips. For banks, these non-interest income streams often form a part of their fee income. If these practices are banned, it could lead to changes in how banks earn revenue from insurance distribution, and their reported fee income may come under pressure. For insurance companies, while the initial adjustment might be challenging, the shift aims to lower distribution costs, which could eventually help support profit margins.
Accountability and Digital Transformation
To address concerns regarding the quality of sales, the regulator is proposing a three-tier structure to classify distributors into Insurance Distribution Entities, Insurance Distribution Persons, and Market Infrastructure Institutions. This move is designed to make it easier to track the source of every policy sale. A key part of this accountability framework includes a provision for clawbacks, where insurers will be required to recover commissions if it is found that an agent misled a customer or sold a policy that the customer could not afford to maintain.
On the digital front, the IRDAI is pushing for the creation of a Public Insurance Registry to verify the history of insurers and distributors. It is also promoting the expansion of Bima Sugam, a platform intended to allow consumers to purchase insurance directly without intermediaries. The regulator hopes that by allowing entities like hospitals and independent automobile garages to participate in distribution under strict safety rules, the market will become more competitive and accessible for consumers. Investors should monitor the final version of these regulations and the timeline for implementation, as they will directly influence the cost structure of the insurance sector.