

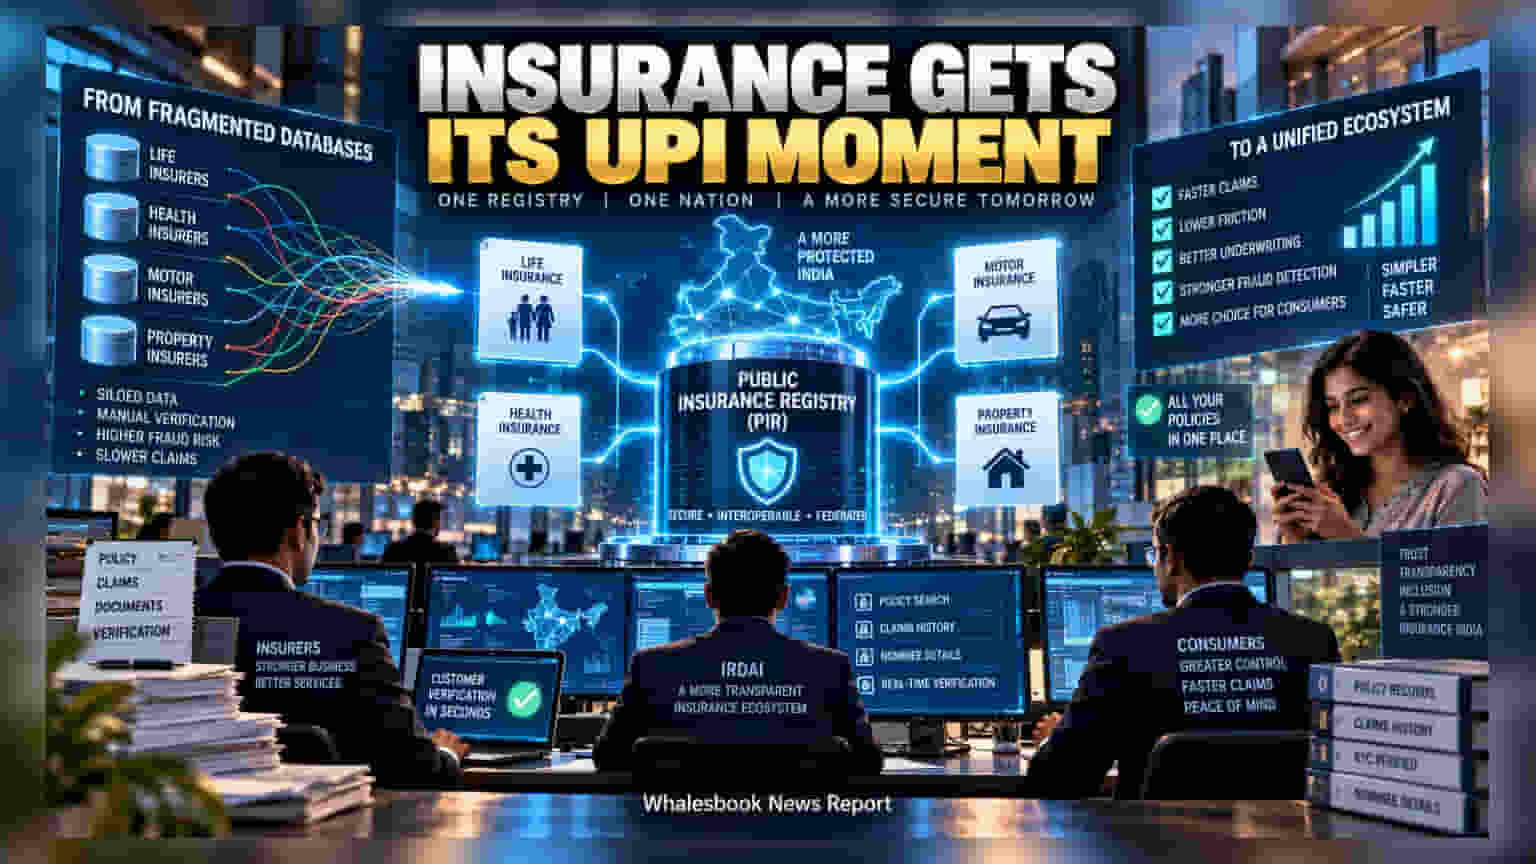
The IRDAI is planning a Public Insurance Registry to create a unified digital framework for life, health, motor, and property insurance records. The move aims to streamline KYC, curb fraud, and improve claims processing by linking fragmented data. For investors, this initiative could reduce operational costs and shift industry competition toward service and pricing, though successful execution remains the primary long-term challenge.
The Insurance Regulatory and Development Authority of India (IRDAI) is planning to launch a Public Insurance Registry (PIR). This initiative aims to create a unified digital framework that links records across life, health, motor, and property insurance. Currently, insurance data in India is fragmented, meaning a consumer’s policy records, claims history, and nominee details are often scattered across different insurers and disconnected systems. The PIR seeks to address these gaps by creating an interoperable layer, allowing for smoother data verification and policy management.
A key feature of this proposal is the use of a federated model. Unlike a central database that collects all customer information in one place, this system keeps raw data where it originates—at the insurance company. The registry acts as a digital bridge, allowing authorized entities to discover and verify information without moving sensitive records into a single location. This architecture is designed to balance the need for data transparency with privacy concerns, preventing the creation of a single point of failure or a massive, centralized store of sensitive personal information.
For investors tracking the insurance sector, this development holds significant implications for profitability. Insurance companies currently face challenges regarding fraud and the high cost of verifying customer identity. With a more consolidated view of claims history and policy status, insurers could improve their underwriting processes—the way they assess risk—and identify fraudulent claims more effectively. By reducing reliance on manual checks and manual documentation, companies could potentially see improved operational efficiency and reduced compliance costs.
The registry could also change the competitive dynamics within the Indian insurance industry. Historically, large insurers have held a competitive advantage due to the depth of their proprietary customer data. By standardizing information access, the PIR may level the playing field, allowing smaller, tech-focused insurers to compete more effectively by accessing verified historical data. This shift is expected to push competition away from who has better internal data toward who offers better products, pricing, and claims service.
As part of the governance structure, the Insurance Information Bureau is set to be restructured into a not-for-profit entity wholly owned by the IRDAI. This move is intended to ensure the registry operates with institutional neutrality, keeping the system distinct from the commercial interests of any single insurance provider.
While the vision is ambitious, the success of the PIR will depend on execution. The insurance industry must integrate its diverse and often legacy IT systems with this new digital architecture. Data quality, security, and the consent framework are critical. The key monitorable for investors will be how quickly insurers update their technology to connect with the registry. Furthermore, the system must be capable of handling long-term contract data, which is far more complex than the transaction-heavy data handled by systems like UPI. The industry's ability to adapt to these technological standards will be the deciding factor for the registry’s long-term impact.