

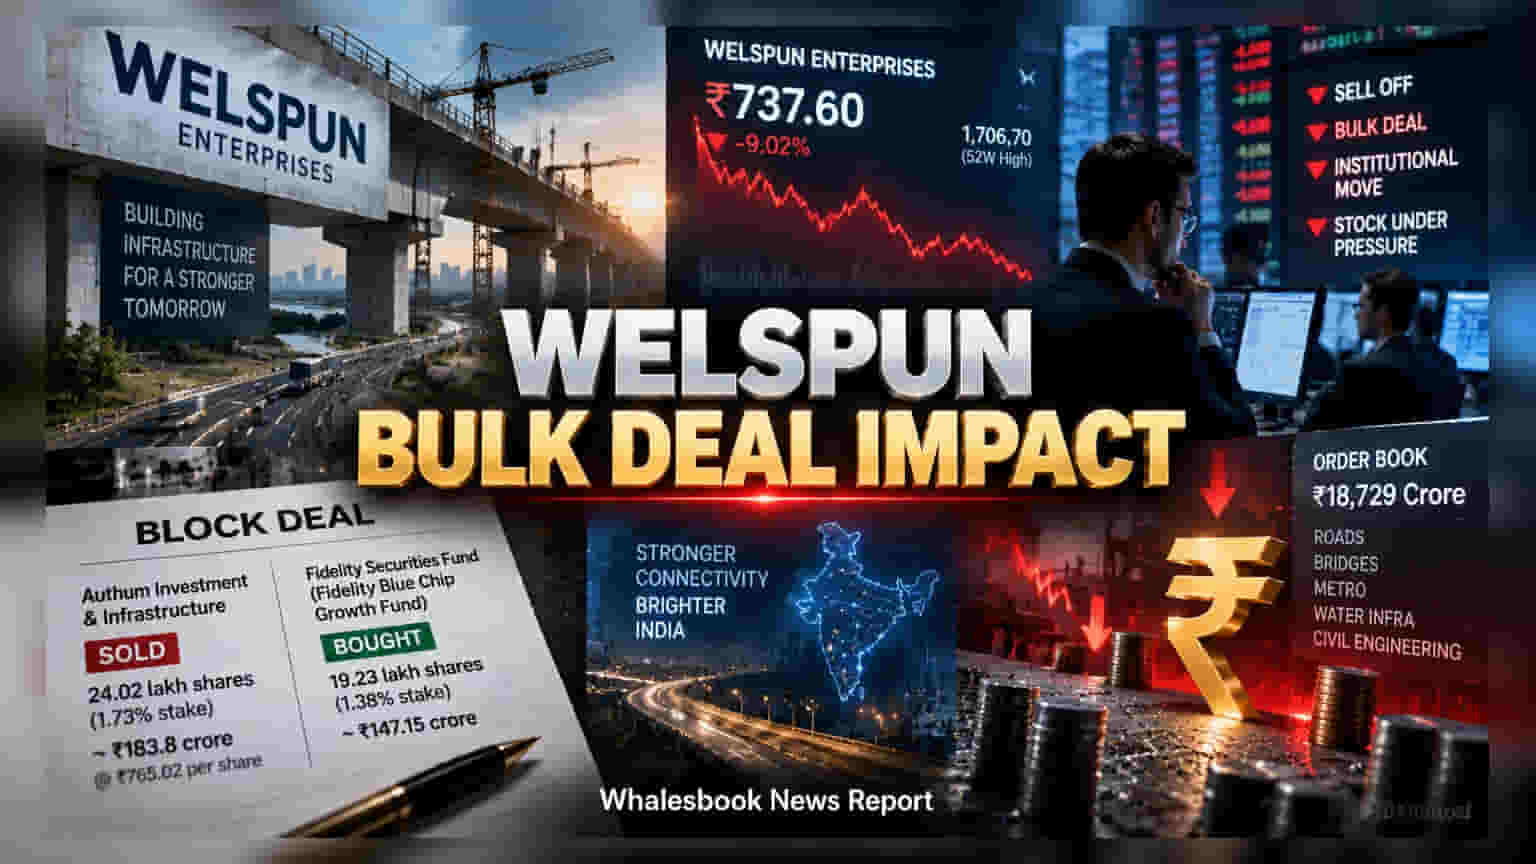
Welspun Enterprises shares fell 6.18% after Authum Investment & Infrastructure sold a 1.73% stake for ₹183.8 crore. Fidelity Securities Fund partially offset the selling pressure by purchasing a 1.38% stake. The price decline follows a recent cooling in the company's financial performance after a sharp rally in August.
Shares of Welspun Enterprises experienced a sharp decline on the National Stock Exchange, closing at ₹737.60 on September 15. The stock price adjustment followed a significant block deal where a major investor reduced its position. While the share price had rallied nearly 47% in August 2026, it has corrected by approximately 9% over the last few trading sessions.
Institutional Stake Shift
Authum Investment & Infrastructure offloaded 24.02 lakh shares, representing about 1.73% of the company's paid-up equity, in a deal valued at approximately ₹183.8 crore. The shares were sold at an average price of ₹765.02 per share. Despite this sell-off, institutional interest remained present. Fidelity Securities Fund, through its Fidelity Blue Chip Growth Fund, acted as a counter-party, acquiring 19.23 lakh shares for ₹147.15 crore, which equates to a 1.38% stake in the infrastructure firm. Such bulk deals often indicate rebalancing among institutional portfolios rather than a fundamental shift in business operations.
Financial Performance Context
Market participants are closely evaluating this share movement alongside the company's recent quarterly results. For the first quarter of fiscal year 2027, Welspun Enterprises reported a 44% decline in profit after tax to ₹56.36 crore, while revenue fell 8.44% to ₹773.72 crore. Consequently, the company has moderated its revenue growth forecast to a range of 10% to 20%. This recent financial contraction, contrasted with the strong stock rally seen earlier in the quarter, suggests that investors are adjusting their expectations regarding near-term profitability.
Order Book and Sector Risks
Despite the recent financial pressure, the company maintains a consolidated order book of ₹18,729 crore as of June 30, 2026. This backlog is vital for revenue visibility, but the ability to convert these orders into profits depends on several external and internal factors. The infrastructure sector faces ongoing risks, including volatility in the prices of raw materials like cement, steel, and bitumen, which can squeeze profit margins if not managed effectively. Furthermore, companies in this space operate in a highly competitive environment where bidding pressures are intense. Investors also keep a close watch on execution risks, such as potential delays in land acquisition and the receipt of necessary regulatory approvals, which can impact project timelines.
The next important monitorable for shareholders will be the company’s ability to improve margins and deliver on its existing order book in the upcoming quarters. Investors will also watch for further patterns in institutional buying or selling, as large block transactions can sometimes signal broader shifts in market sentiment regarding the stock’s valuation.