

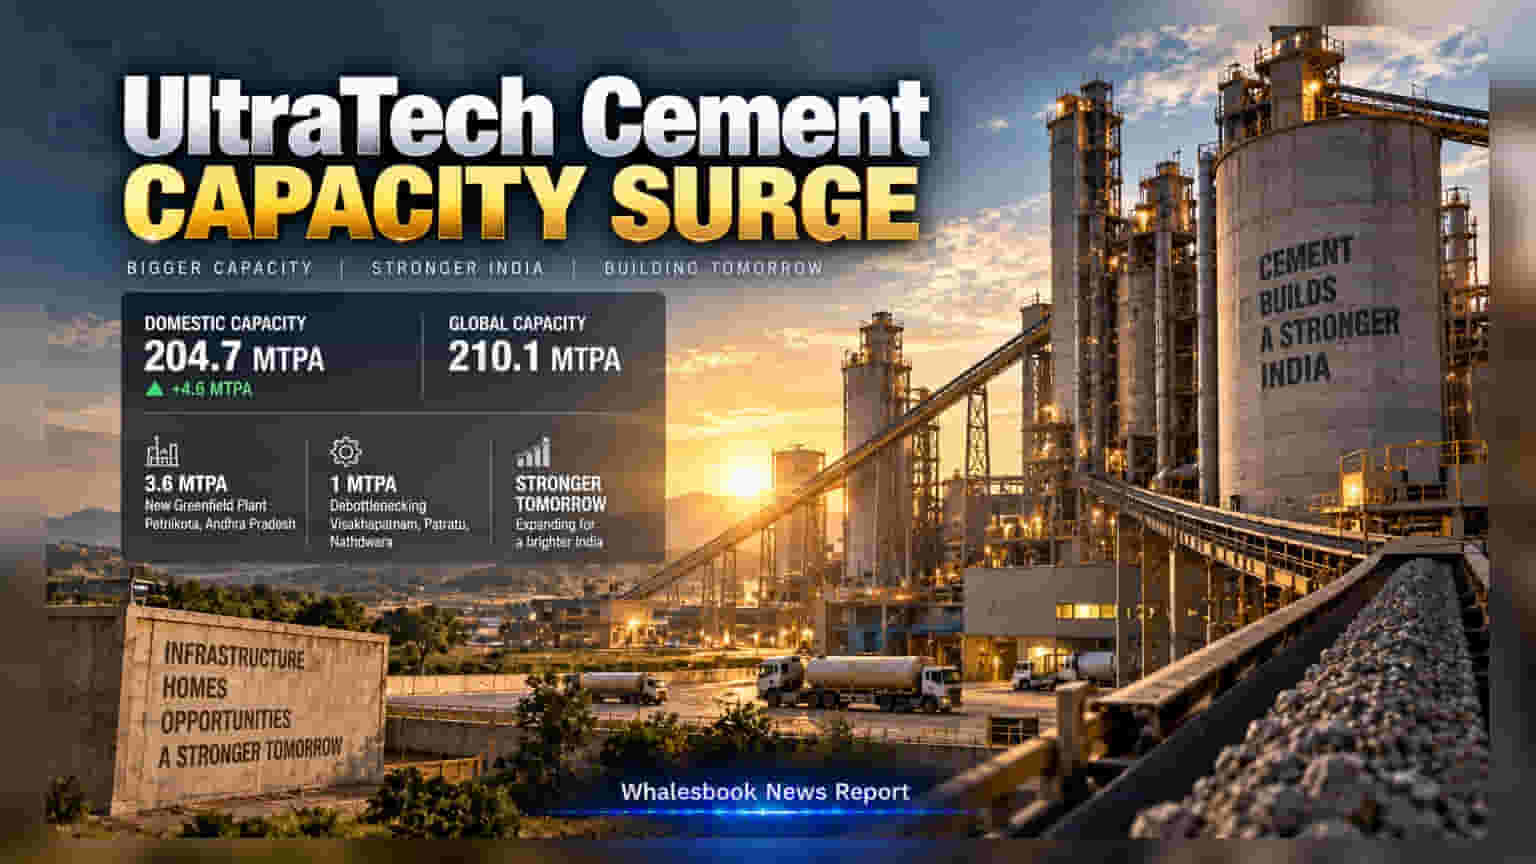
UltraTech Cement has increased its domestic grey cement capacity to 204.7 MTPA by adding 4.6 million tonnes through new facilities and efficiency upgrades. This expansion strengthens the company's leading market position but also increases the need for high capacity utilization. Investors may track whether the company can maintain pricing stability as it brings this large volume of new supply into the market.
UltraTech Cement, the flagship company of the Aditya Birla Group, has increased its domestic grey cement manufacturing capacity to 204.7 MTPA. This follows the successful commissioning of 4.6 million tonnes per annum (MTPA) of new capacity, which also brings its total global manufacturing footprint to 210.1 MTPA.
The recent capacity addition was achieved through a mix of new construction and efficiency improvements. A 3.6 MTPA greenfield integrated cement facility was commissioned in Petnikota, Andhra Pradesh, which serves as a significant contributor to this growth phase. Additionally, the company added 1 MTPA of capacity through debottlenecking initiatives at its existing plants in Visakhapatnam, Patratu, and Nathdwara. Debottlenecking is a strategic move for the company as it allows for increasing output from current facilities by improving operational flow and efficiency, often at a lower cost and faster timeline than building a new plant from scratch.
For investors, the primary consideration with such aggressive capacity expansion is the balance between volume growth and profitability. While this scale provides the company with significant supply chain and pricing leverage, the cement industry is highly capital intensive. The cost of building new capacity must be supported by adequate demand to ensure that the plants run at high utilization rates. If demand does not keep pace with the influx of new supply, profit margins across the sector can come under pressure due to increased competition and weaker pricing power.
In the Indian cement sector, companies often face cyclical risks where high-capacity expansion cycles coincide with slower-than-expected demand growth or rising costs of key inputs like pet coke and coal. UltraTech Cement's ability to maintain its market share while protecting its profit margins despite this expansion will be a critical factor. The company has a long history of expansion, but the ongoing impact of these capital-heavy projects on its cash flow and return on equity is something that market analysts regularly evaluate.
The next steps for investors will involve tracking the company's capacity utilization rates in its newly commissioned plants and monitoring the overall cement pricing trend in the Indian market. Additionally, management commentary regarding future capital spending and debt management will provide clarity on the long-term impact of this growth strategy on the company's financial health.