

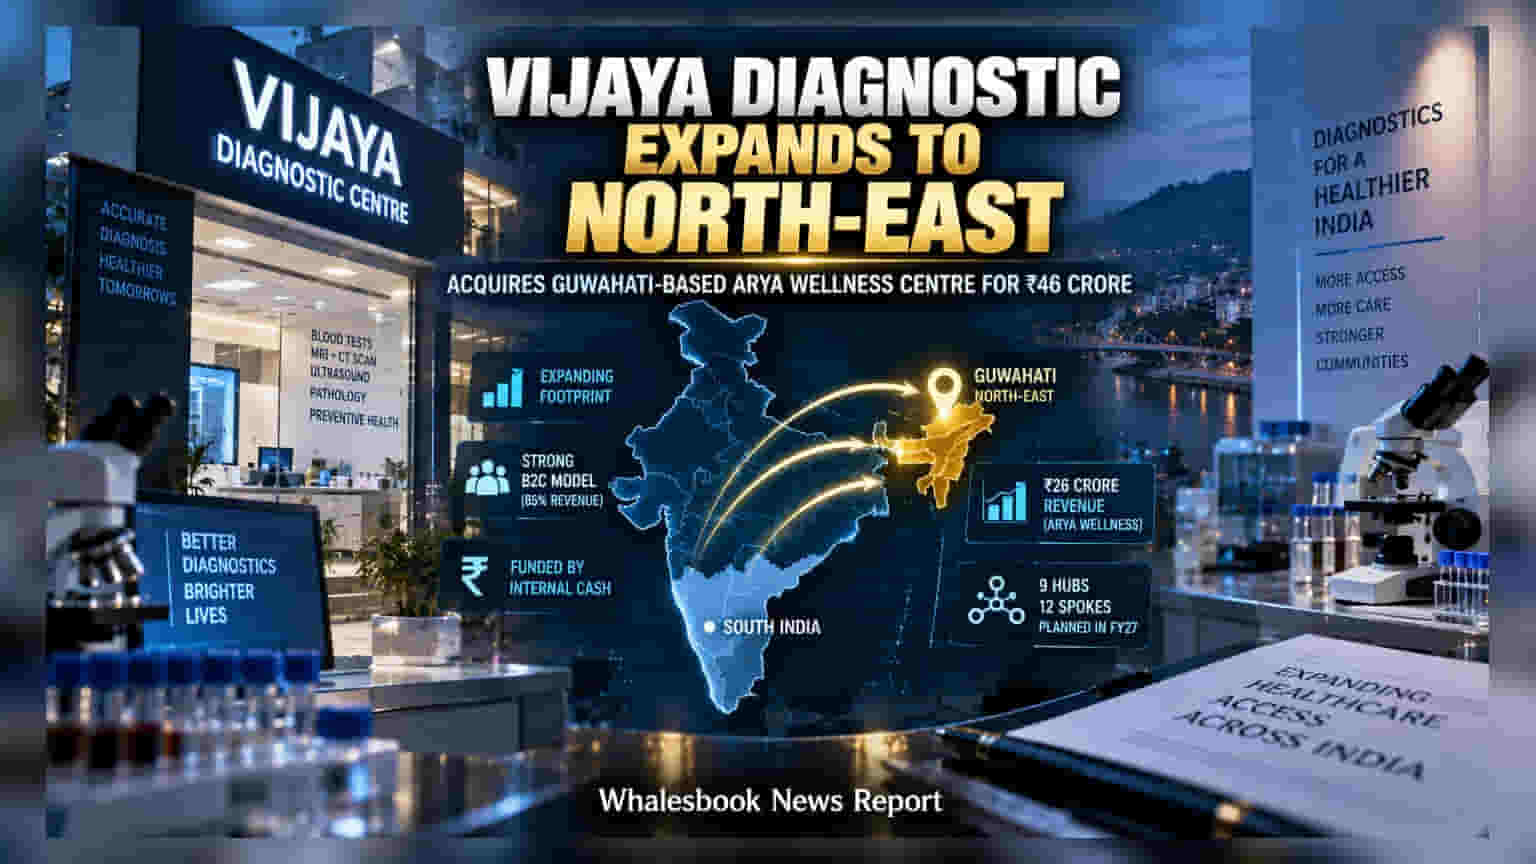
Vijaya Diagnostic Centre has acquired Guwahati-based Arya Wellness for ₹46 crore to expand its footprint into North-East India. The deal adds a network focused on patient-direct services, which aligns with the company’s existing business model. Investors should track how the company maintains its high profit margins while funding this expansion and managing its recent stock price premium.
Vijaya Diagnostic Centre is expanding its footprint from South India to the North-East with the acquisition of the Guwahati-based Arya Wellness Centre. The company announced it will pay ₹46 crore for the facility. This deal marks the diagnostics firm's first major step into the North-East, adding a business that reported ₹26 crore in revenue during the previous financial year.
A key reason for this purchase is the target company’s business model. About 85% of Arya Wellness’s revenue comes directly from patients, known as B2C business. This matches the model of Vijaya Diagnostic, which prefers this segment because it typically provides better profit margins compared to business from hospitals or corporate clients.
The company is funding this expansion using its own cash from past profits, avoiding the need for new loans or diluting value for existing shareholders. This financial discipline comes at a time when the company has shown strong results. In the first quarter of the 2027 fiscal year, Vijaya Diagnostic reported revenue of ₹147 crore, a 22.8% increase compared to the same period a year earlier. Its operating profit margin stood at 42.7%, highlighting its ability to control costs while growing.
While the expansion offers growth potential, it brings operational challenges. The company plans to add nine hubs and up to 12 spokes in the 2027 fiscal year. Similar expansions in the past have occasionally led to pressure on profit margins while the new centers stabilize. Investors will monitor whether the company can maintain its high-margin trajectory as it sets up its network in a new, competitive region.
The stock's recent performance is also a point of focus. Shares of Vijaya Diagnostic have risen 74% over the last six months. This rapid increase means the stock is currently trading at about 33 times its estimated operating profit for the 2028 fiscal year. This price is roughly 20% higher than the company's average valuation over the past five years. Moving forward, the key for investors will be to watch how the company integrates the new assets and whether it can continue to grow profitably in the North-East market while managing these valuation levels.