

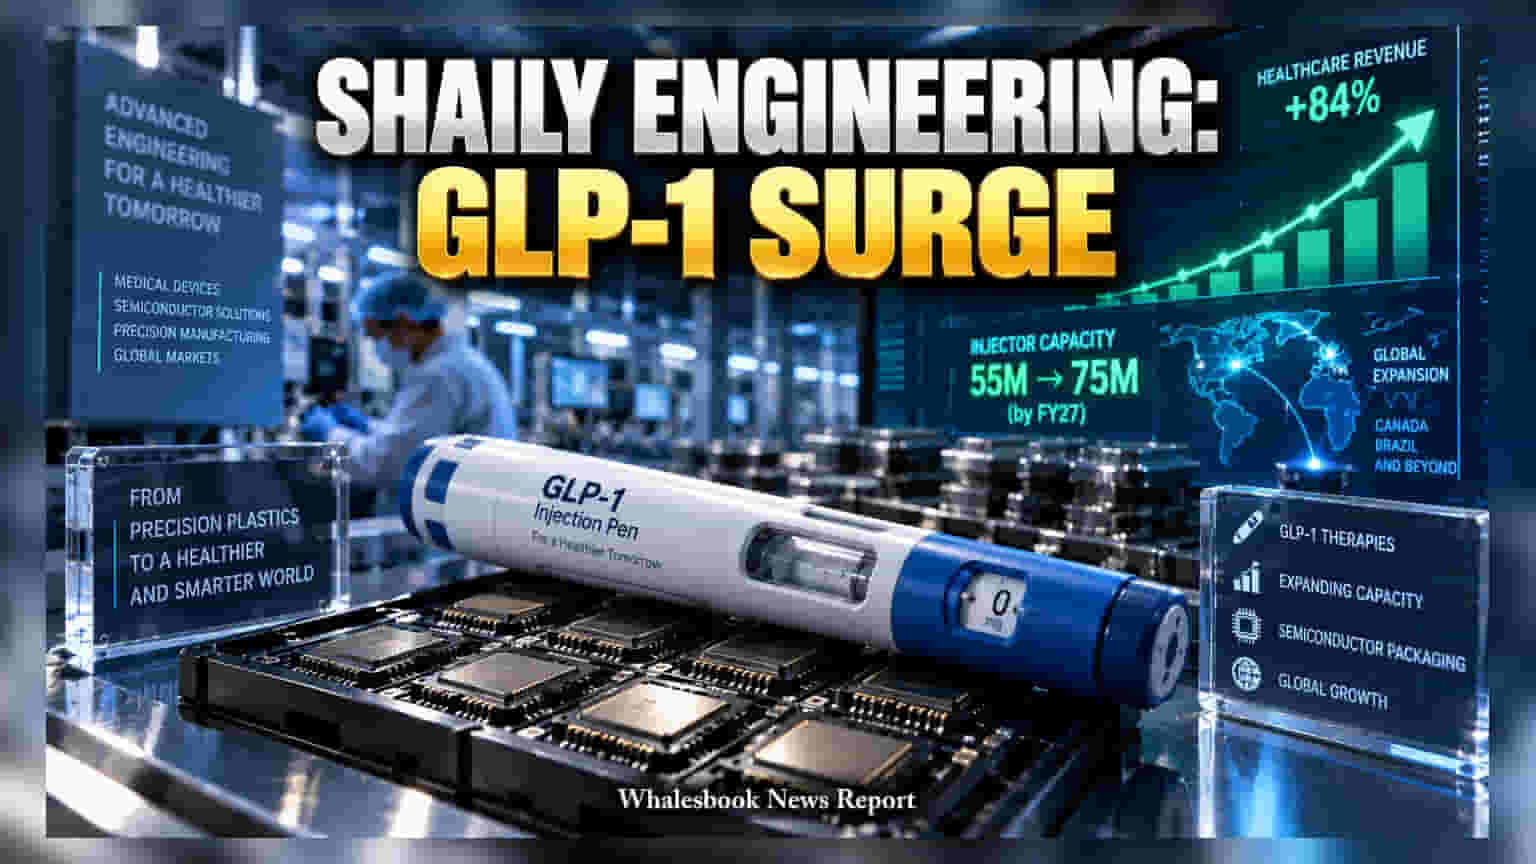
Shaily Engineering Plastics is scaling its medical device capacity to 75 million units by FY27, fueled by strong demand for GLP-1 drug-delivery pens. Despite an 84% jump in healthcare revenue, the company faces a 24% decline in consumer electronics and high valuation at 48x FY28 earnings. Investors are tracking whether this premium valuation can be justified by successful expansion into semiconductor packaging and continued growth in medical devices.
Shaily Engineering Plastics is shifting its business strategy, aiming to reduce dependence on traditional consumer electronics by scaling its healthcare and engineering divisions. While the company has seen strong demand for its medical injection pens, the transition comes at a time when its legacy electronics business has faced a 24 percent revenue decline due to weak demand from Western markets.
The company’s primary growth driver is its healthcare portfolio, specifically devices used for GLP-1 therapies, which are gaining popularity for diabetes and weight management. The company reported an 84 percent increase in healthcare revenue year-over-year. In the most recent quarter, it shipped 9 million devices. To keep up with this demand, the company is increasing its annual production capacity for injectors from 55 million units to 75 million units by fiscal year 2027. Shaily has noted that two-thirds of this new capacity is already secured by commitments from customers, which adds a layer of revenue predictability. The company has also expanded its reach, gaining regulatory approvals for Semaglutide pens in Canada and Brazil.
Operational performance has also seen a change. Rejection rates, which were a significant hurdle in the past, have dropped to approximately 8 percent, down from 30 percent. This improvement helps protect profit margins even when raw material or freight costs fluctuate.
In an effort to further diversify, Shaily is entering the semiconductor packaging market. It is developing conductive-plastic trays for global chipmakers. This sector has high barriers to entry, meaning fewer competitors. Revenue from this segment is expected to begin in late fiscal year 2027. This move is intended to balance the weakness observed in its consumer electronics segment.
While the shift toward high-value healthcare is clear, the stock is currently trading at roughly 48 times its projected fiscal year 2028 earnings. This valuation suggests the market has already factored in significant future growth, leaving little room for operational errors. The company faces specific risks, such as potential delays in customer-led regulatory approvals or a shift in medical preferences toward oral GLP-1 therapies, which could reduce the demand for injectable devices. For investors, the next important update will be the progress on commissioning the new medical capacity and whether the semiconductor packaging segment can successfully offset the current weakness in the electronics business.