

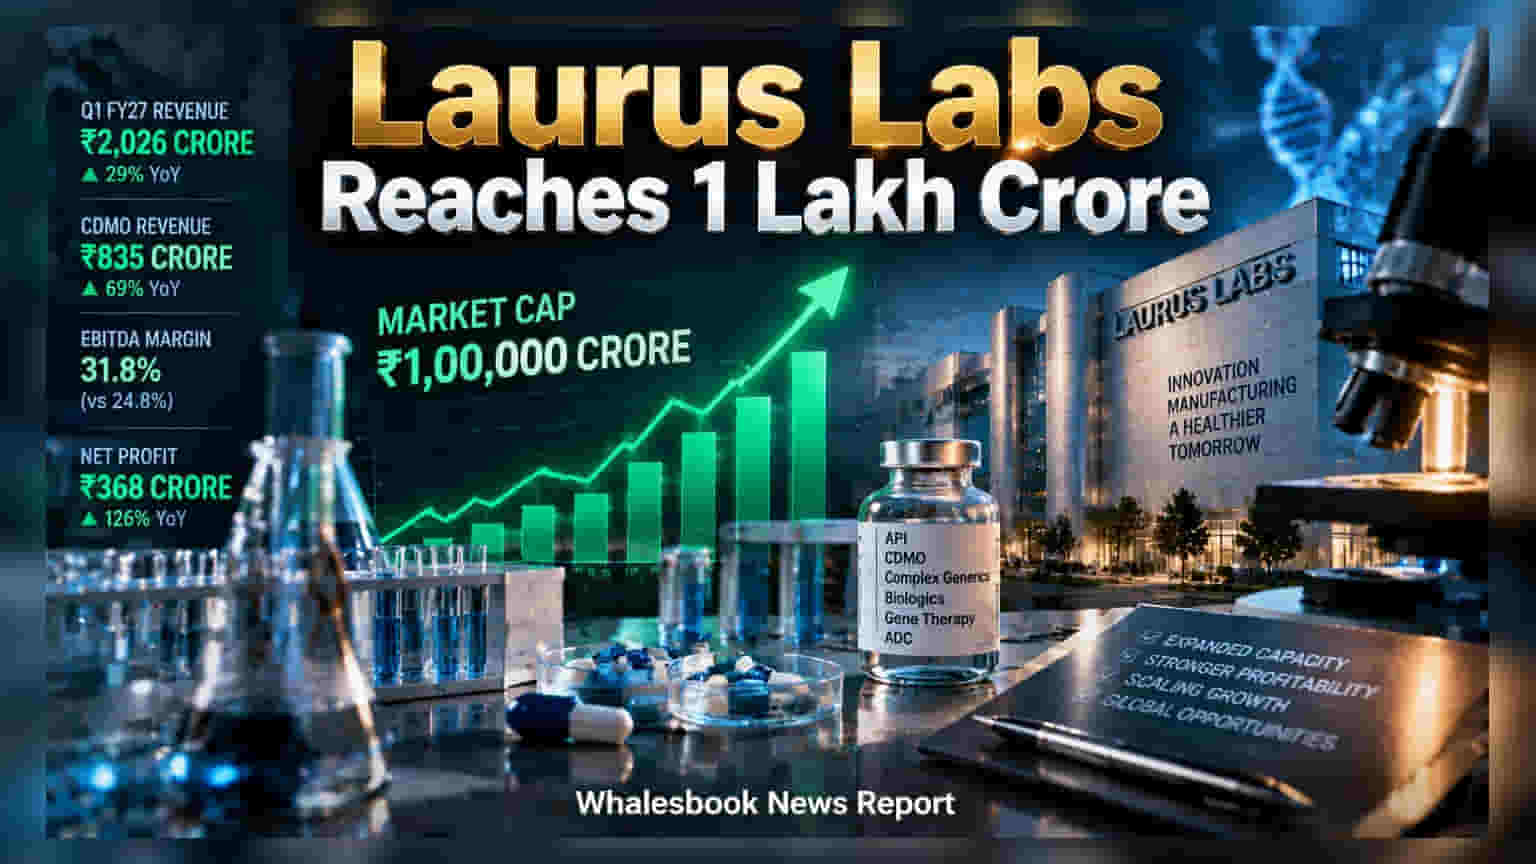
Laurus Labs reported a 69% year-on-year surge in CDMO revenue for the June quarter, helping it cross the ₹1 lakh crore market capitalization milestone. Driven by strong commercial scaling, the company raised its FY27 capital spending guidance to ₹2,000 crore. Investors may monitor whether this aggressive capacity expansion maintains current margins amidst execution and long-term gestation risks.
Laurus Labs crossed the ₹1 lakh crore market capitalization milestone following a strong financial performance in the first quarter of the 2027 fiscal year. The company reported a revenue of ₹2,026 crore, marking a 29% growth compared to the same period last year. A major driver of this performance was the Contract Development and Manufacturing Organization (CDMO) segment, which recorded a 69% year-on-year jump in revenue, reaching ₹835 crore. Commercial-stage supplies now account for 55% of this segment, suggesting the company is effectively transitioning from initial R&D spending to revenue-generating operations.
Strategic Capex Shift
This growth follows a multi-year investment phase that saw the company deploy over ₹4,700 crore between fiscal years 2022 and 2027. With the initial heavy spending cycle largely complete, management has shifted its focus toward scaling these assets. The company recently revised its FY27 capital expenditure guidance upward to ₹2,000 crore, up from an initial range of ₹1,000–1,500 crore, citing increased demand from existing partners. This increased allocation is intended to support the production of complex pharmaceutical products.
Operational efficiency has also improved, with the EBITDA margin expanding to 31.8% in the June quarter, compared to 24.8% in the previous year. This margin improvement reflects the company's ability to better absorb costs as production volume increases. Net profit for the quarter saw a significant 126% year-on-year surge, reaching ₹368 crore.
Risks and Investor Monitorables
While the company is scaling up, investors are tracking several operational and financial factors. The primary concern is execution risk; increasing the capex budget to ₹2,000 crore requires successful project commissioning and sustained demand to justify the outlay. Furthermore, the company is investing in high-tech areas such as gene therapy and antibody-drug conjugates (ADCs). These segments typically have long gestation periods, with management indicating it could take four to five years for these investments to yield significant returns.
Beyond internal execution, the company remains sensitive to global pharmaceutical demand and potential regulatory audit outcomes, which are common factors in the healthcare and biotech sector. Investors may watch for the upcoming analyst and investor interaction scheduled for September 22, 2026, which may provide more clarity on the timeline for these new projects and the outlook for capacity utilization.