

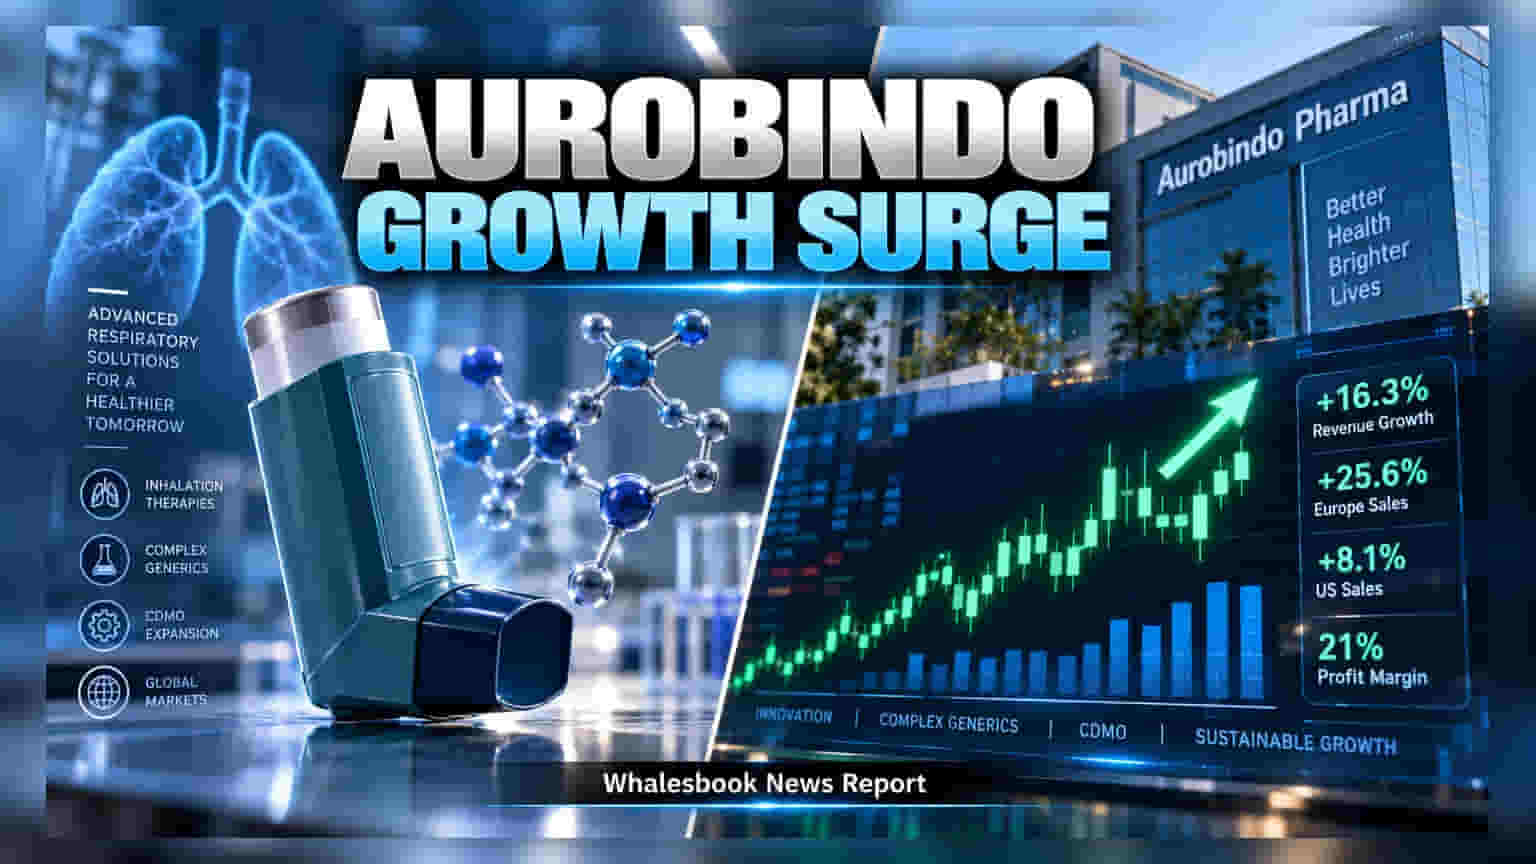
Aurobindo Pharma is pushing into the US respiratory inhaler market and scaling its CDMO business to diversify revenue. The company reported 16.3% revenue growth in the June quarter, supported by strong European sales. Investors are monitoring whether the company can maintain its 21% profit margins while balancing the execution risks of these new capital-heavy expansions against its current valuation.
Aurobindo Pharma is shifting its strategy toward specialized drug segments to secure long-term growth. The company is currently focusing on two main pillars: entering the complex respiratory inhaler market and scaling up its Contract Development and Manufacturing Organisation (CDMO) services. This move is part of an effort to reduce reliance on traditional generic medicines, which often face intense price competition.
The company’s entry into the respiratory market has already started with the launch of an inhalation product equivalent to Advair, a popular asthma treatment. This opening grants the company access to a market estimated at $650 million. Additionally, receiving final approval for a generic QVAR inhaler adds another $300 million market opportunity. These product launches are part of a broader strategy to establish a presence in the complex, high-value segment of the US pharmaceutical market.
Simultaneously, the company is aggressively expanding its CDMO operations. Management has set ambitious targets, aiming to increase formulation CDMO revenue from $20 million annually to over $200 million by the 2031 financial year. Plans also include growing revenue from active pharmaceutical ingredients and peptides to $50 million and $100 million respectively. If achieved, these segments could become the primary drivers of growth, potentially outpacing the company's traditional business in the coming years.
The company’s recent financial results show steady momentum. During the June quarter, Aurobindo Pharma reported 16.3% revenue growth, with its European business growing by 25.6% and US sales rising by 8.1%. Profit margins have held steady at 21%, a level the company aims to maintain through the 2027 financial year. Gross margins improved by 153 basis points year-on-year to 60.4%, partly due to internal cost control and captive sourcing of key materials.
Regulatory and execution risks remain factors for investors to watch. Following the integration of Lannett Company, a recent US FDA inspection of its facility resulted in four procedural observations. Management noted these as minor, viewing the inspection as a positive step for future filings. However, as the company scales its complex manufacturing and CDMO capabilities, the risk of project delays or cost increases in executing these expansions will be a key area for shareholders to monitor.
From a valuation perspective, the stock is currently trading at roughly 16 times its estimated earnings for the 2028 financial year. This has led some brokerages to maintain a cautious hold rating, reflecting concerns over whether current valuations fully price in the future growth from these new projects. Others remain more positive, citing the firm's pipeline of 896 pending generic filings as a source of stability. Moving forward, the key indicators for investors will be the actual revenue contribution from the new respiratory products and the ability to maintain profit margins while scaling the CDMO business.