

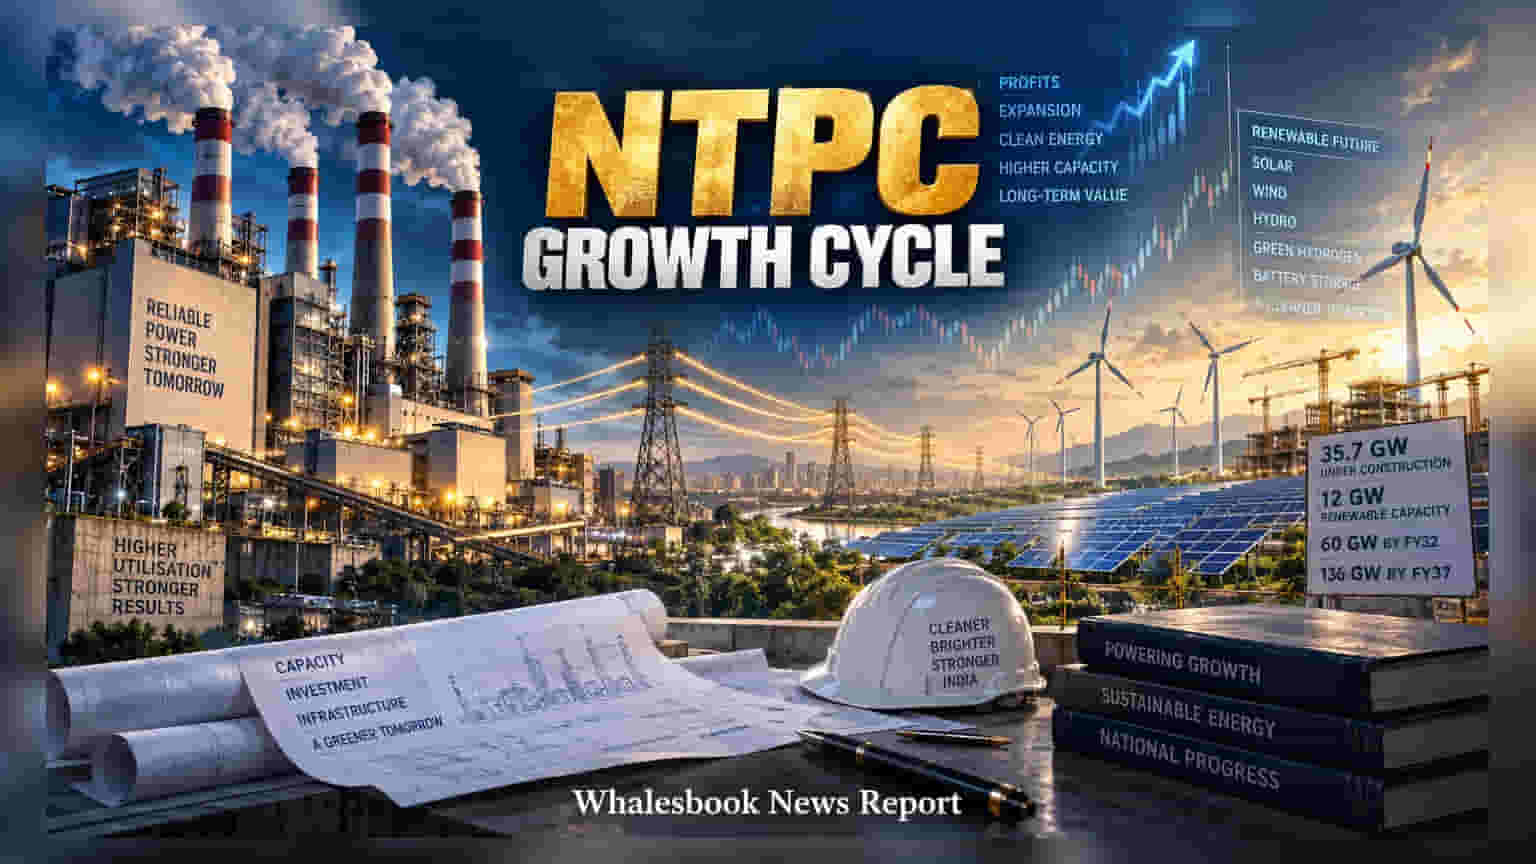
NTPC shares have corrected about 20% from May highs despite a 13% rise in Q1 FY27 net profit. While near-term power demand has cooled, the company maintains a massive 35.7 GW expansion pipeline, with $31 billion in planned investments through FY29 to drive long-term capacity growth.
NTPC Limited has experienced a stock price correction, falling from approximately ₹410 in May to around ₹329 as of September 2026. This decline reflects broader profit booking in public-sector energy stocks and market concerns over slower power demand and the pace of renewable project execution. Despite this market pullback, the company’s core business performance has shown resilience in the recent quarter.
In the first quarter of FY27, NTPC reported a 13% year-over-year growth in net profit, reaching ₹6,896 crore. A key driver for this stability is the company’s efficient management of its thermal power plants. Its coal-fired fleet operated at a plant load factor of 76.71%, which is notably higher than the national average of 70.32%. This efficiency is important for investors because a higher load factor translates into better utilization of assets and higher revenue from the regulated cost-plus business model.
Expanding the Growth Pipeline
NTPC is currently executing one of its largest expansion phases. The company has a massive 35.7 GW of power projects currently under construction, covering thermal, hydro, and renewable energy segments. This massive footprint is supported by a record capital expenditure of ₹55,986 crore spent in FY26. To sustain this, management has outlined a significant investment plan of nearly $31 billion for the FY27 to FY29 period. This heavy spending is designed to boost the company’s regulated equity base, which grew 9% year over year to ₹1,21,745 crore, providing a reliable foundation for future earnings.
The Shift to Clean Energy
Beyond traditional thermal power, the company is actively shifting its focus toward a greener portfolio. Its renewable energy capacity has reached 12 GW, with a pipeline of nearly 30 GW in development. The company aims to scale its renewable capacity significantly, targeting 60 GW by FY32 and 136 GW by FY37. This transition also includes investments in nuclear power through the joint venture NPUNL, alongside entry into green hydrogen and battery energy storage solutions.
Risks and Market Valuation
While the expansion plans are ambitious, investors should keep a close watch on potential risks. Large capital expenditure programs carry the risk of cost overruns and delays in project commissioning, which could put pressure on cash flows and debt levels. Additionally, if power demand remains soft in the near term, the utilization rate of new assets could be lower than anticipated. At current levels, the stock is trading at approximately 10 times estimated FY28 earnings and 1.3 times estimated FY28 book value. The long-term performance of the stock will likely depend on the company's ability to execute these projects on time and maintain its operating margins while balancing the heavy debt required to fund such a massive expansion.