

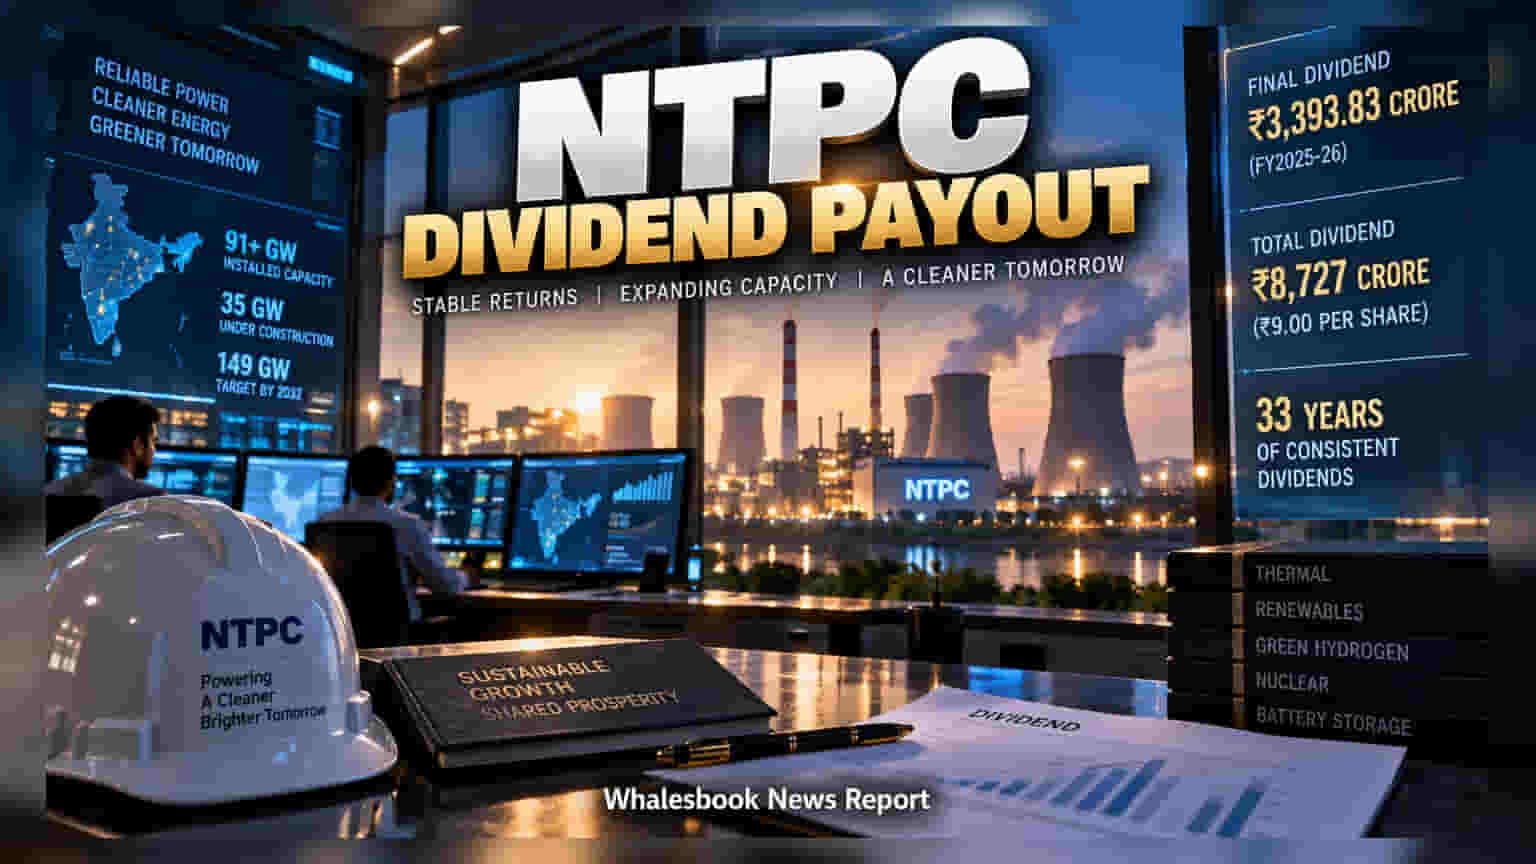
State-run power major NTPC has announced a final dividend of Rs 3,394 crore for FY26, bringing its total annual distribution to Rs 8,727 crore. This payout translates to Rs 9 per share. Investors are now watching how the company manages the balance between these regular cash returns and the massive capital spending required for its 149 GW capacity expansion target by 2032.
NTPC Limited has announced a final dividend of Rs 3,393.83 crore for the financial year 2025-26. This payout, processed on September 23, 2026, marks the 33rd consecutive year of dividend distribution by the state-run power producer. With this final tranche, the total dividend payout for the fiscal year reached Rs 8,727 crore, which comes to Rs 9.00 per share on a face value of Rs 10.
Balancing Growth and Returns
The consistent dividend payment reflects the company's focus on maintaining stable cash flow for shareholders, even as it undergoes a major transition in its business model. NTPC is currently shifting its focus from being a traditional thermal power producer to an integrated energy company. The company currently manages an installed generation capacity of over 91 gigawatts. To meet future energy demands, it has an additional 35 gigawatts of projects under construction, with a long-term goal to reach a total capacity of 149 gigawatts by 2032.
Renewables and Execution Risk
A key part of this expansion is a plan to add 60 gigawatts of renewable energy capacity, alongside investments in emerging fields such as green hydrogen, nuclear energy, and large-scale battery storage. While this expansion is necessary for long-term growth and aligns with national energy goals, it also requires significant money spent on expansion. Investors should track whether the company can execute these projects within the planned timelines and budgets. Any delay in commissioning large infrastructure projects or cost overruns can put pressure on the company's financial health, despite its strong current earnings. Additionally, as the company enters competitive areas like e-mobility and waste-to-energy, its ability to maintain profit margins will be an important factor to monitor.
Ultimately, the sustainability of these shareholder returns will depend on the company's ability to balance its heavy capital requirements with efficient project execution. The market will look for updates on the commissioning status of the 35 gigawatts currently under construction, which will be the primary driver for revenue and profit growth in the coming years.